Does everyone in Florida need flood insurance: 1 Vital Choice
The Short Answer vs. The Smart Answer
Does everyone in florida need flood insurance? The short answer is no – not every home is legally mandated to have flood insurance. But here’s the smart answer: Florida’s unique geography makes nearly every property vulnerable to flooding, and standard homeowners insurance doesn’t cover flood damage.
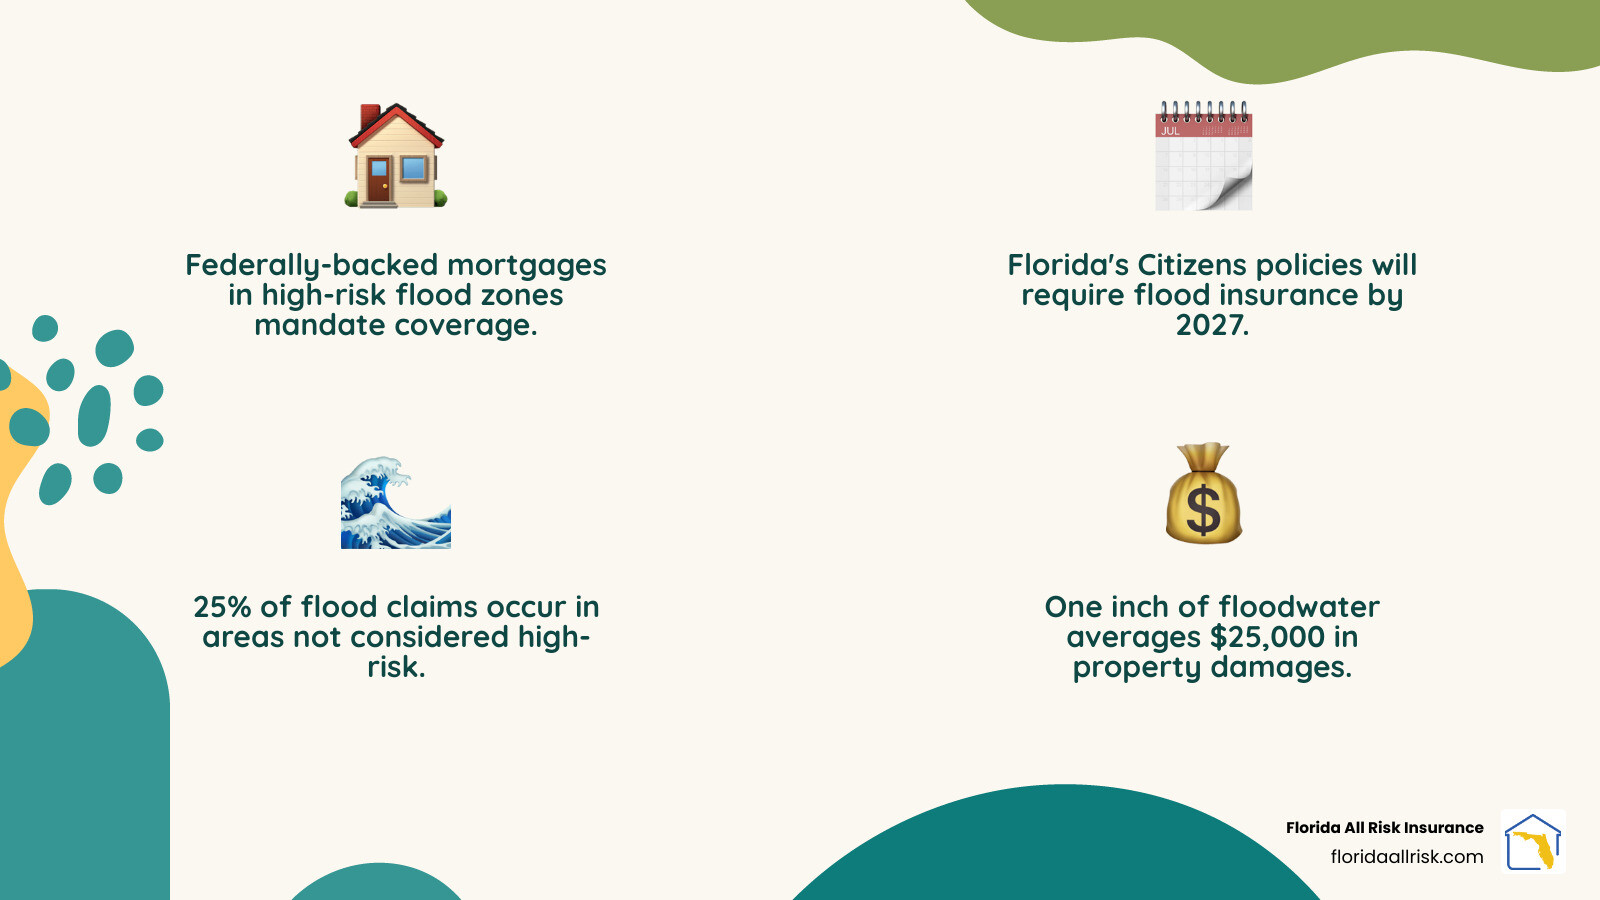
Quick Facts:
- Legally Required: Homes with federally-backed mortgages in Special Flood Hazard Areas (SFHAs)
- State Mandate: All Citizens Property Insurance policyholders must have flood insurance by 2027
- Practical Reality: 25% of flood claims come from “low-risk” areas
- Financial Risk: Just 1 inch of floodwater causes $25,000 in damage on average
- Coverage Gap: Standard homeowners insurance excludes flood damage
While not every Florida resident faces a legal requirement, the state’s flat terrain, heavy rainfall, and extensive coastline create flood risks that extend far beyond designated flood zones. Hurricane Ian in 2022 caused over $100 billion in damage, with an estimated $10 billion to $16 billion being uninsured flood losses—a stark reminder that proper coverage can mean the difference between quick recovery and financial devastation.
As a second-generation insurance professional with over 20 years of experience in Florida, I’m Jason Miller. I’ve witnessed how proper flood coverage protects families from catastrophic loss. In this guide, I’ll walk you through the requirements, risks, and smart choices to safeguard your biggest investment.
Easy does everyone in florida need flood insurance word list:
- Flood insurance requirements Florida
- FEMA flood zone map
- Does flood zone AE require flood insurance in Florida?
The Shifting Tides: Florida’s Evolving Flood Insurance Requirements

Florida’s insurance landscape is constantly evolving. Recent legislative changes and federal mandates are reshaping who needs flood insurance. While not every homeowner is required by law to have it, new state and federal rules mean more Floridians than ever must carry this crucial coverage.
Who Is Required to Have Flood Insurance by Law?
Flood insurance is legally required if you have a federally-backed mortgage and your home is in a Special Flood Hazard Area (SFHA). These high-risk zones (like Zones A and V on FEMA maps) have a 1% or greater annual chance of flooding, which translates to a 26% chance over a 30-year mortgage. Lenders mandate coverage through the National Flood Insurance Program (NFIP) or an equivalent private policy before closing. This is a non-negotiable requirement for these homeowners. For more details, see our guide on flood insurance requirements Florida.
The Citizens Insurance Mandate: A Game-Changer for Florida Policyholders
A major change impacting many homeowners is the new Citizens Property Insurance mandate. Due to Senate Bill 2A, Florida’s state-backed insurer now requires most policyholders to carry flood insurance, regardless of their flood zone. This is a phased-in requirement that began in 2024 and expands annually.
The timeline is as follows:
- Jan 2024: Homes valued at $600,000+
- Jan 2025: Homes valued at $500,000+
- Jan 2026: Homes valued at $400,000+
- Jan 2027: Nearly all Citizens policies, regardless of value.
This move aims to reduce financial risk for the state-backed insurer. As a result, many Floridians who were not previously required to have flood insurance now find it mandatory. Understanding your property’s risk, such as whether it’s in a Special Flood Hazard Area (SFHA), is more important than ever.
Are There Any Exemptions to These Requirements?
Some exemptions to these mandates exist. For example, upper-floor condominium units may not require building coverage, as it’s typically handled by the association’s master policy (though a contents-only policy is still wise). Renters are not required to insure the building, but their personal belongings are not covered by the landlord’s policy. The Citizens mandate also primarily applies to policies that include wind coverage; those without it may be exempt, though such policies are rare in Florida. Crucially, standard homeowners policies always have policy exclusions for flood damage. Understanding what your policy does and does not cover is vital to avoid financial disaster.
Why Every Floridian Should Consider Flood Insurance (Even If It’s Not Required)
Even if you aren’t legally required to have flood insurance, the practical reasons to get it are overwhelming. Florida’s unique geography and climate create flood risks that extend far beyond designated zones, catching many homeowners by surprise.
The Unseen Risk: When “Low-Risk” Zones Flood
Florida’s flat terrain, low elevation, extensive coastline, and heavy rainfall create widespread flood risk. Intense storms and runoff from new construction can cause flooding even in areas not considered high-risk. The statistics are sobering: approximately 25% of all flood claims occur in moderate-to-low-risk areas. This means one in four payouts goes to someone who likely thought they were safe. Hurricanes like Ian and Idalia demonstrated this reality, inundating communities far from the coast. Many homeowners are shocked to find their standard policy offers no coverage for this type of damage. To better understand your property’s vulnerability, see our flood insurance risk assessment page.
The High Cost of Going Uninsured
The financial devastation of an uninsured flood can be life-altering. A sobering fact from FEMA is that just one inch of water can cause $25,000 in damages. This includes replacing drywall, flooring, electrical systems, and ruined personal property. Rebuilding costs can easily reach hundreds of thousands of dollars, a catastrophic expense for most families, especially when they find their homeowners policy provides no coverage. When you compare this risk to the average flood insurance premium in Florida (around $888 per year), the value of the protection becomes clear. It’s a small price to pay to avoid financial ruin.
Federal Disaster Assistance vs. Flood Insurance: A Reality Check
Many people mistakenly believe federal disaster assistance will cover them after a flood, but disaster assistance is not a substitute for insurance. This aid typically comes as a low-interest loan that must be repaid, not a grant. The average FEMA assistance payment is around $5,000, while the average flood insurance claim payout is over $40,000. Furthermore, federal aid is only available after a Presidential Disaster Declaration, which isn’t guaranteed for every flood event. The process can be slow and complex. Flood insurance provides a reliable and substantial path to recovery without relying on government declarations or taking on new debt.
Understanding Your Flood Risk and Insurance Options
To decide if you need flood insurance, you must understand your specific risk and the policy options available to protect your financial security.
How to Determine Your Property’s Flood Risk
Start by checking the official FEMA Flood Zone Map to find your property’s classification. You can check your address at the FEMA Flood Map Service Center. Key zones include:
- Zones A and V: High-risk areas where flood insurance is often mandatory for mortgage holders. Zone V includes the additional hazard of storm-driven waves.
- Zone AE: A high-risk zone with a determined Base Flood Elevation, which helps predict floodwater height.
- Zone X: Moderate-to-low-risk areas. Insurance isn’t federally mandated here, but these zones account for 25% of all flood claims, highlighting the widespread risk.
Local county planning departments can also offer historical flood data.
Homeowners Insurance vs. Flood Insurance: What’s Actually Covered?
A critical point of confusion for many is the difference between homeowners and flood insurance. Your standard homeowners policy covers many perils, including certain types of water damage like a burst pipe. However, it explicitly excludes damage from flooding, defined as rising surface water. After a hurricane, this leads to complex wind-versus-water damage issues. For example, rain entering through a wind-damaged roof is typically covered by homeowners insurance. But water rising from the ground and entering your home is considered a flood and requires a separate flood policy. To be fully protected, you need both types of coverage. Be aware that you will have separate deductibles for each policy.
The National Flood Insurance Program (NFIP) vs. Private Flood Insurance
You can buy flood insurance through two main channels: the National Flood Insurance Program (NFIP) or the private market.
- The NFIP is a federal program offering standardized coverage, sold through authorized agents. It has building coverage caps of $250,000 and contents caps of $100,000. It generally has a 30-day waiting period and limited additional coverages like loss of use.
- Private flood insurance is offered by private companies and often provides more flexibility. It can feature higher coverage limits, shorter waiting periods (10-14 days), and extra options like Additional Living Expenses (ALE). Rates can be competitive, particularly for lower-risk properties.
While the NFIP is a foundational program, the private market in Florida has grown, offering more custom solutions. An independent agency can help you compare both NFIP and private options to find the best fit for your needs and budget.
So, Does Everyone in Florida Need Flood Insurance? The Practical Answer
After exploring the legal requirements and practical risks, let’s get to the heart of the matter. The answer to does everyone in florida need flood insurance depends on your specific situation and risk tolerance. However, for most Floridians, the smart choice leans heavily toward obtaining coverage.
For Homeowners: Does Everyone in Florida Need Flood Insurance?
For homeowners, the question shifts from legal mandate to financial necessity. If you don’t fall under the mandatory requirements (e.g., SFHA mortgage, Citizens policy), consider the risk. Your home is likely your largest asset, and in Florida, the risk of flood damage is widespread. For most, the risk of catastrophic loss far outweighs the annual premium cost. A simple rule of thumb: if you cannot afford to rebuild your home out-of-pocket, you cannot afford to go without flood insurance. It’s an essential tool for protecting your financial future. For more on high-risk zones, see our guide on Does Flood Zone AE Require Flood Insurance in Florida?.
For Renters: Protecting Your Personal Belongings
Renters often mistakenly believe their landlord’s insurance covers their possessions. This is false. The landlord’s policy covers the building only, not your personal belongings. Renters should get flood insurance to protect their furniture, electronics, and other valuables. The NFIP offers affordable contents-only policies, providing up to $100,000 in coverage for personal property. Considering the high cost of replacing everything you own, a small annual premium is a wise investment. For more details, see FEMA’s Flood Insurance For Renters guide.
For Business Owners: Safeguarding Your Livelihood
For business owners, flood insurance is about safeguarding your livelihood. A flood can destroy not just your building and inventory but also lead to lost income and potential closure. Commercial flood insurance protects your physical assets (building, equipment, inventory) and is a critical component of any business continuity plan in flood-prone Florida. The cost of coverage is minimal compared to the risk of losing your entire operation. Learn more on our Flood Insurance for Businesses page.
Navigating the Cost and Process of Getting Flood Insurance
Understanding the financial aspects and timelines is the final step before securing coverage. The good news? It’s often less complicated and less expensive than many people assume when they first ask does everyone in florida need flood insurance.
How Much Does Flood Insurance Cost in Florida?
The average flood insurance premium in Florida is around $888 per year, but your actual cost is highly personalized. Several factors determine your rate:
- Flood Zone: High-risk zones (A, V, AE) cost more than moderate-to-low-risk X zones.
- Property Elevation: Homes built higher above the Base Flood Elevation typically have lower premiums.
- Deductible & Coverage Amount: A higher deductible lowers your premium, while higher coverage limits increase it.
- Building Characteristics: The age, construction type, and prior claims history of your property all impact the cost.
Because pricing is so specific, premiums can range from a few hundred to several thousand dollars. For a detailed breakdown, see our guide on How Much Does Flood Insurance Cost in Florida?
The Waiting Game: How Long Until Your Policy Is Active?
A crucial detail is the policy waiting period. Most NFIP policies have a 30-day waiting period before coverage becomes active. This safeguard prevents people from buying insurance just before a storm hits, ensuring the program’s stability. There are exceptions, such as when flood insurance is required for a mortgage closing, in which case the waiting period is often waived. Private flood insurance can also offer shorter waiting periods, sometimes just 10 to 14 days. The key takeaway is to plan ahead. Don’t wait for a storm to be on the horizon to secure coverage.
Your Next Steps to Secure Peace of Mind
The question isn’t just “does everyone in florida need flood insurance?” but rather, “Can I afford the financial devastation of a flood without it?” For the vast majority of Floridians, the answer is no. Protecting your largest asset is a critical financial decision. An independent insurance agency can be your greatest ally, helping you compare policies from both the NFIP and private markets to find the right fit for your needs and budget. The experts at Florida All Risk Insurance are equipped to steer these complexities for you, ensuring you have the right protection in place before the waters rise.
Ready to protect your home and finances? Explore your options on our comprehensive Florida flood insurance page and get the peace of mind you deserve.
Contact Us
Getting the right flood insurance coverage shouldn’t be a guessing game. Whether you’re wondering does everyone in florida need flood insurance or you’re ready to secure protection for your home, business, or personal belongings, we’re here to help you steer every step of the process.
At Florida All Risk Insurance, we understand that insurance decisions can feel overwhelming, especially when you’re trying to balance legal requirements, financial protection, and peace of mind. That’s why we take the time to explain your options clearly, compare policies from both the National Flood Insurance Program and private carriers, and help you find coverage that fits your specific needs and budget.
Our team has helped thousands of Florida families and businesses secure the right flood insurance protection. We know the ins and outs of FEMA flood zones, the Citizens Property Insurance mandate timeline, and how to make sure you’re covered before the next storm season arrives.
Ready to protect what matters most? Give us a call, send us an email, or stop by our office in Saint Petersburg. We’ll review your property’s flood risk, explain your coverage options, and help you get the protection you need – all with the personal touch that only an independent agency can provide.
Florida All Risk Insurance
Address: 777 9th St N, Saint Petersburg, FL 33701
Phone: (727) 498-5554
Email: [email protected]
Additional Resources:
Word count: 2,847 words