

Why Understanding Classic Car Insurance Costs Matters for Florida Collectors
If you’re wondering how much does classic car insurance cost, the answer might surprise you. Specialized classic car insurance is often significantly less expensive than a standard auto policy, with average annual premiums ranging from $400 to $1,000. This coverage is designed for collector vehicles, recognizing they are driven sparingly and maintained with exceptional care.
Unlike a daily driver, a classic car is often an appreciating asset. Standard auto insurance isn’t built for vehicles that gain value. Classic car policies use an “Agreed Value” approach, which guarantees a predetermined payout if your vehicle is totaled. This protects your car’s true worth, unlike a standard policy’s “actual cash value” that factors in depreciation.
The lower premiums reflect the reduced risk associated with classic cars. Owners are typically careful enthusiasts who store their vehicles securely, drive them infrequently (often under 5,000 miles per year), and keep them in excellent condition. However, the exact cost depends on your vehicle’s value, your driving history, your storage arrangements, and your location in Florida. Coastal areas like St. Petersburg may see different rates due to unique factors like weather risks. At Florida All Risk Insurance, we help you steer these details to ensure your passion is properly protected.
What is Classic Car Insurance and How Does It Differ from Standard Auto Insurance?
Owning a classic car is a unique experience, blending passion with a significant investment. This is why classic car insurance is not just a different name for regular auto insurance—it’s specialized coverage designed to protect these irreplaceable assets. It’s custom-built for collector’s items, antiques, and vintage models that are used for pleasure, not as daily drivers.
For more information on how we can protect your unique vehicle, explore our Classic Car Insurance Florida services.
The Crucial Difference: Agreed Value vs. Actual Cash Value (ACV)
The most important distinction lies in how your vehicle’s value is determined after a total loss.
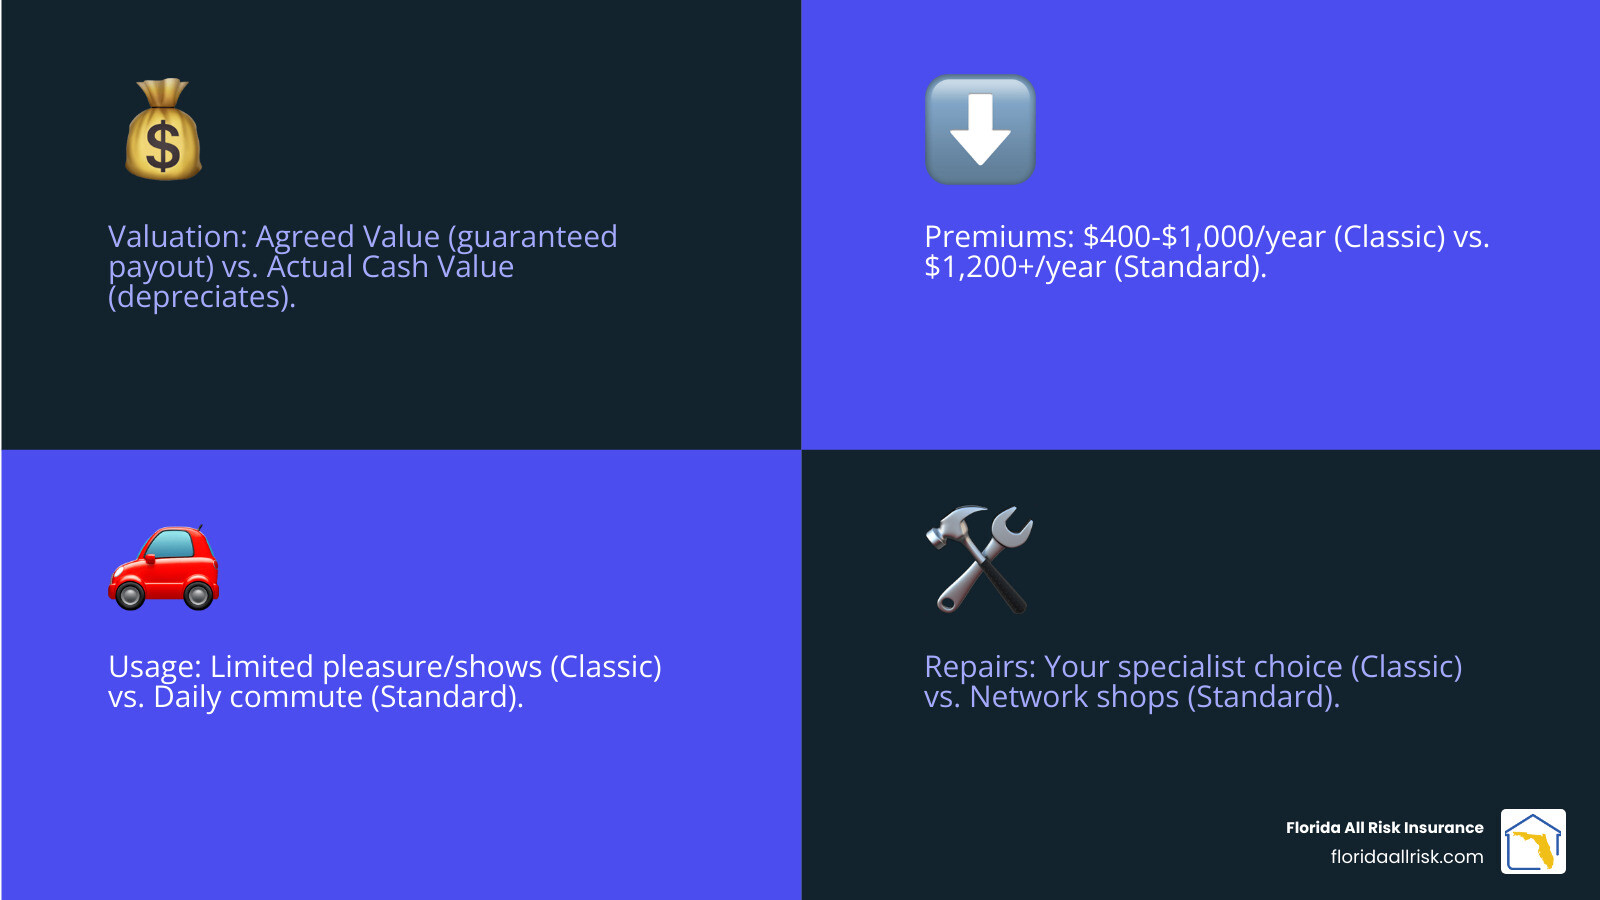
Agreed Value: With classic car insurance, you and the insurer agree on a specific value for your car when the policy is written. If your car is declared a total loss, this agreed-upon amount is the exact sum you will receive, minus any deductible. There are no surprises or deductions for depreciation, which is crucial for cars that often increase in value.
Actual Cash Value (ACV): Standard auto policies use ACV, which pays the vehicle’s replacement cost minus depreciation. As vehicles lose value over time—with some models declining about 20% in a single year according to data from Black Book and Fitch Ratings—an ACV policy can be disastrous for a classic car owner. Your appreciated classic could be valued at a much lower, depreciated amount, leaving you with a significant financial loss.
Why Standard Policies Fall Short for Classic Cars
Beyond valuation, standard policies are ill-suited for classics because they are built around depreciation and daily use. Classic cars are driven infrequently, limiting their risk exposure. They also require specialized, often expensive, parts and repairs from expert mechanics. Standard insurers might push for generic parts or non-specialist repairs, compromising the vehicle’s authenticity and value. A standard policy would also charge higher premiums by assuming daily use, meaning you’d pay more for inappropriate coverage.
| Feature | Classic Car Insurance | Standard Auto Insurance |
|---|---|---|
| Valuation Method | Agreed Value (Guaranteed Payout, No Depreciation) | Actual Cash Value (Depreciated Value) |
| Premium Cost | Lower (often 50-75% less) | Higher (for similar coverage limits) |
| Usage | Limited, Pleasure (Car Shows, Parades, Weekend Drives) | Daily Commute, Errands, Regular Transportation |
| Repair Options | Choice of Specialist Repair Shop | Network Shops, Standard Parts |
How Much Does Classic Car Insurance Cost on Average?
Many classic car enthusiasts in Florida are pleasantly surprised to learn that insuring their prized possession is often more affordable than they think. When asking how much does classic car insurance cost, the answer is quite favorable for collectors.
On average, a classic car insurance policy costs between $400 and $1,000 per year. While specific premiums vary, this highlights a significant cost advantage over standard auto insurance. In many cases, classic car insurance can be up to 75% less expensive than a regular policy, a direct result of the unique risk profile of these vehicles.
Why is Classic Car Insurance More Affordable?
It may seem counterintuitive that a valuable vehicle costs less to insure, but the reasons are logical:
- Lower Risk Profile: Classic cars are not daily commuters. They spend less time on the road, reducing exposure to accidents and theft.
- Infrequent Use: Most policies include mileage restrictions (e.g., 5,000 miles per year), which lowers the statistical probability of a claim.
- Careful Owners: Enthusiasts tend to drive more cautiously, maintain their cars carefully, and use secure storage.
- Secure Storage: A key requirement is secure storage in a locked garage or similar facility, which reduces theft and weather-related risks.
The savings can be impressive. Industry data consistently shows that specialized classic car policies offer substantial discounts compared to standard insurance. Opting for this coverage can lead to considerable cost savings while providing superior, custom protection for your vehicle.
Key Factors That Influence Your Classic Car Insurance Premium
When we determine how much does classic car insurance cost for your vehicle, we consider several factors that shape your premium. Understanding these can help you make informed decisions.
For a personalized assessment, Learn more about Florida Classic Car Insurance.
Vehicle Value, Age, and Rarity
The characteristics of your car are a primary driver of cost:
- Agreed Value: This is the most important factor. A higher agreed-upon value means a higher potential payout, which typically results in a higher premium.
- Make, Model, and Age: Certain makes and models are rarer or have higher performance, influencing their value and insurance cost. A 1965 Ford Mustang has different considerations than a 1980s sedan.
- Collectibility: Rarity increases value. A limited-production vehicle will command a higher agreed value and premium than a mass-produced classic.
- Exotic and Muscle Cars: These high-value, high-performance categories may have slightly higher premiums than more conventional classics.
Usage and Mileage Restrictions
How you use your classic car is critical:
- Pleasure Use Only: Classic car insurance is designed for pleasure driving, such as weekend cruises, club activities, and car shows.
- Mileage Limits: Most policies include annual mileage limits, commonly around 5,000 miles. Exceeding this limit can void your coverage.
- No Daily Commute: This is a strict requirement. Your classic cannot be your primary vehicle for daily transportation. Insurers require proof of a separate, daily-use vehicle, which is a major reason for the affordable premiums.
Vehicle Storage and Condition
Where and how you store your car significantly impacts risk:
- Secure Storage: Insurers require classic cars to be stored in a secure, enclosed space like a locked garage or dedicated storage facility to protect against theft and damage.
- Vehicle Condition: A well-maintained vehicle in excellent, restored condition is seen as a lower risk. Cars undergoing restoration may require specific “vehicle under construction” coverage.
Your Driving Record and Experience
Your personal driving history is as important as it is for a standard policy:
- Clean Driving Record: A record free of major accidents and traffic violations is essential. Insurers look for responsible drivers.
- Experience: Many insurers prefer policyholders with at least 10 years of driving experience. Mature, experienced drivers are often seen as lower risk.
- No Major Violations: A history of DUIs or reckless driving will likely make it difficult to obtain classic car insurance.
Location and How Much Does Classic Car Insurance Cost in Florida
Your geographic location, especially in Florida, plays a role:
- Local Factors: In areas like St. Petersburg, we consider local theft rates and traffic density.
- Weather Risks: Florida’s climate, with its hurricane season and potential for flooding, is a key consideration. While secure storage helps, the risk of damage from natural disasters can influence premiums.
- Repair Costs: The regional cost of specialized classic car repairs can also affect the premium.
Understanding Your Classic Car Insurance Policy
It’s not just about how much does classic car insurance cost; it’s about understanding what you’re paying for.
For a detailed look at options for older vehicles, Explore Antique Car Insurance.
Eligibility Requirements for Classic Car Insurance
Not every old car qualifies. Insurers have specific criteria:
- Vehicle Age: Generally, a vehicle must be at least 20 to 25 years old. Some insurers consider newer, highly collectible models.
- Collector Status: The vehicle must be considered a collector’s item due to rarity, historical significance, or unique features.
- Condition: The car should be well-maintained and in good working order.
- Secure Storage: The vehicle must be kept in a locked, enclosed garage or facility.
- Limited Usage: The car is for pleasure use only, with annual mileage limits.
- Primary Daily Driver: You must own and insure a separate vehicle for daily transportation.
What Does a Typical Policy Cover?
A classic car policy includes fundamental coverages adapted for your vehicle:
- Liability Coverage: This is legally required in Florida and covers damages you cause to others (bodily injury and property damage) in an at-fault accident.
- Comprehensive Coverage: Protects your car from non-collision incidents like theft, vandalism, fire, and natural disasters (hail, floods, hurricanes).
- Collision Coverage: Pays for damages to your classic car from a collision with another vehicle or object.
- Uninsured/Underinsured Motorist (UM/UIM): Protects you if you’re hit by a driver with little or no insurance.
Special Benefits and Add-On Coverages
One of the greatest advantages of classic car insurance is the availability of specialized benefits:
- Spare Parts Coverage: Protects your collection of unused spare parts against theft or damage.
- Cherished Salvage / Buy-Back Option: In a total loss, some policies let you buy back the damaged car after receiving the agreed value payout.
- Vehicle Under Construction Coverage: Protects your car during a restoration project, with some policies automatically increasing the value as work progresses.
- Inflation Guard: Automatically increases your agreed value by a small percentage annually to keep pace with appreciation.
- Roadside Assistance with Flatbed Towing: Ensures your vehicle is transported on a flatbed truck to prevent damage.
- Trip Interruption Coverage: Helps with expenses like lodging and food if your car breaks down far from home.
- Memorabilia Coverage: Can protect valuable associated items like vintage license plates or historical documents.
How to Save Money on Your Classic Car Insurance
While protecting your classic is paramount, finding affordable rates is always a priority. There are several smart strategies to reduce your costs without compromising coverage.
For specific options, please see our Insurance Collector Car services.
Bundling Policies and Choosing the Right Deductible
- Multi-Policy Discounts: One of the most effective ways to save is by bundling your classic car policy with your homeowners, flood, or standard auto insurance. As an independent agency, we can find a carrier that provides competitive rates across all your needs.
- Deductible Options: Your deductible is the amount you pay out-of-pocket before coverage begins. Choosing a higher deductible typically lowers your premium. We can help you find a balance that fits your budget and risk tolerance.
Taking Advantage of Discounts
Classic car insurers offer several discounts for responsible owners:
- Car Club Membership: Members of recognized classic car clubs often receive discounts, as they are viewed as dedicated enthusiasts.
- Anti-Theft Devices: Installing approved anti-theft or tracking systems can qualify you for a discount by reducing theft risk.
- Defensive Driving Course: Completing an approved course demonstrates your commitment to safety and may earn you a discount.
- Mature Driver Discount: Experienced drivers with a clean record often qualify for lower rates.
How to Determine How Much Classic Car Insurance Cost You’ll Pay
The best way to understand how much does classic car insurance cost for your vehicle is to get a personalized quote. As an independent agency, Florida All Risk Insurance works with a wide range of top-rated carriers specializing in classic car insurance. We do the legwork for you, comparing multiple quotes to find the best coverage at the most competitive price. Our priority is finding the right solution for you, and we provide free, no-obligation quotes to help you explore your options without pressure.
Frequently Asked Questions about Classic Car Insurance Costs
Can I use my classic car as a daily driver?
No. Classic car policies are specifically designed for limited, pleasure-use vehicles, not for daily commuting or errands. This restriction is a key reason why premiums are so much lower. You are typically required to have a separate, standard-insured vehicle for daily use.
Do I need a professional appraisal for my classic car?
While not always mandatory, a professional appraisal is highly recommended. It provides certified documentation to help establish the “Agreed Value” of your vehicle, ensuring you are adequately insured. An appraisal simplifies the claims process and prevents disputes over your car’s true value.
Can I get insurance for a modified classic car or a hot rod?
Yes, many specialty insurers offer coverage for modified vehicles, hot rods, and custom builds. It is crucial to fully disclose all modifications to your insurer. This ensures your changes are included in the agreed value and that your policy remains valid.
Protecting Your Passion with the Right Coverage
In conclusion, the cost of classic car insurance is surprisingly affordable, often ranging from $400 to $1,000 annually. Insurers recognize that these vehicles are driven sparingly and maintained with exceptional care. The key is the “Agreed Value” policy, which protects your car’s full worth without depreciation—a feature standard auto insurance can’t match. By understanding the factors that influence your premium, you can secure a policy that provides robust protection for your prized investment.
As an independent agency, Florida All Risk Insurance helps you steer the nuances of classic car coverage. We compare options from multiple top-rated carriers to find the perfect policy for your unique vehicle and needs, serving clients in St. Petersburg and throughout Florida.
Ready to protect your classic car with a policy as unique as it is? Request a free, no-obligation quote for your Florida classic car insurance today!
Contact our specialists to discuss your classic car and find the best coverage options available.
Contact Us
Florida All Risk Insurance
Address: 123 Main Street, Saint Petersburg, FL 33701
Phone: (727) 555-1234
Email: [email protected]

