

St. Petersburg commercial auto insurance: Top 5 Reasons
Why Your St. Pete Business Needs Commercial Auto Insurance
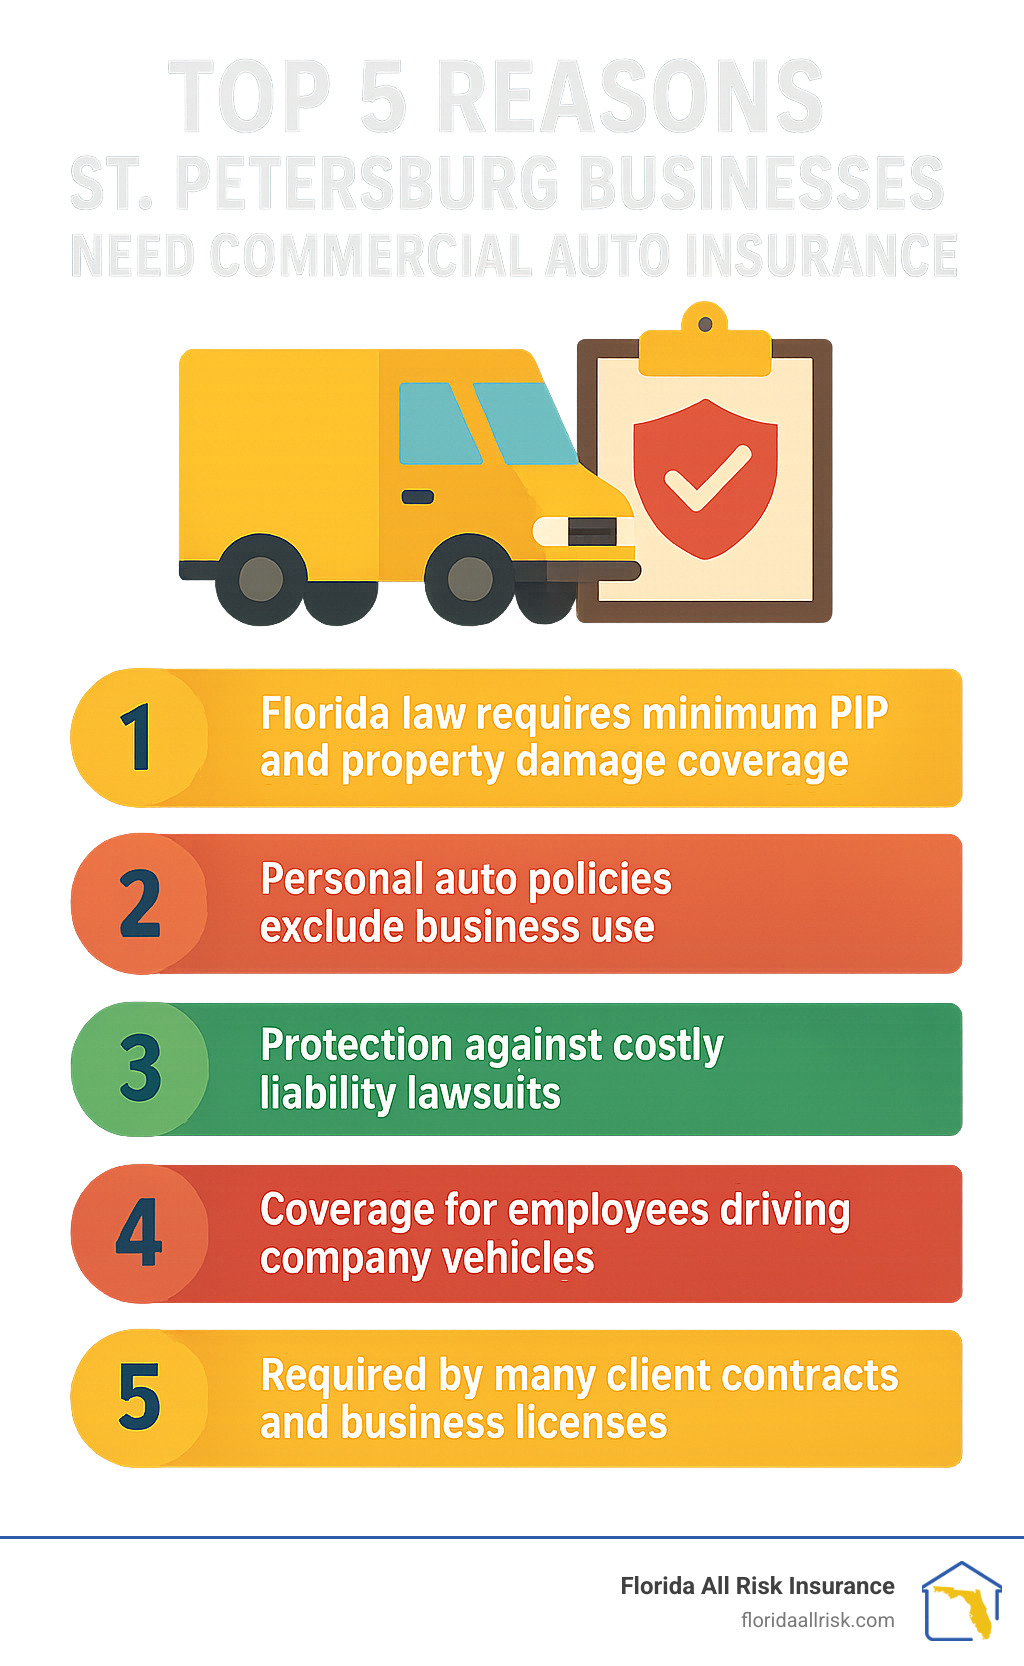
St. Petersburg commercial auto insurance is essential protection for any business that uses vehicles for operations. Whether you’re a contractor hauling tools, a food truck serving downtown, or a real estate agent driving clients, commercial auto coverage shields your business from costly liability claims and vehicle damage.
Here’s what St. Petersburg businesses need to know:
- Required by law: Florida mandates minimum coverage including $10,000 in Personal Injury Protection (PIP) and $10,000 in Property Damage Liability.
- Personal policies don’t cover business use: Using your personal auto policy for work can result in denied claims.
- Protects against lawsuits: Commercial liability coverage protects your business assets if you cause an accident.
- Covers employee drivers: Protection extends to employees operating company vehicles.
- Essential for client contracts: Many clients require proof of commercial auto insurance.
The stakes are high for St. Petersburg businesses. Without proper commercial coverage, a single incident could devastate your finances and reputation. Many business owners mistakenly believe their personal auto policy covers work-related driving, but this is rarely the case. Personal policies typically exclude business use due to the higher liability exposure.
As a second-generation insurance agency with over 20 years of experience, Florida All Risk Insurance has guided thousands of St. Petersburg businesses through the complexities of St. Petersburg commercial auto insurance. Our team understands the local market and Florida’s specific requirements, making the process straightforward for busy business owners.
Basic st. petersburg commercial auto insurance terms:
What is Commercial Auto Insurance?
Commercial auto insurance is designed to protect your business from the financial fallout of vehicle accidents. It acts as a shield for your business assets, specifically for vehicles used in your operations. Unlike a personal policy, a commercial policy accounts for the higher risks associated with business use, such as more miles driven, heavier loads, and varied drivers.
This policy helps cover the costs of an auto accident caused by you or an employee while conducting business, including property damage, medical expenses, and legal fees. It acknowledges that when a vehicle is used for business, the potential for liability is much greater. If a delivery driver causes an accident, the business can be held responsible—a key differentiator from personal auto insurance, which isn’t equipped for business-level risks.
Businesses and Vehicles That Require Coverage
If your business relies on vehicles, you likely need commercial auto insurance. It’s not just for large fleets; even a small business with a single car used for client visits needs this protection. The rule is simple: if a vehicle is used primarily for business, owned by the business, or regularly driven by employees for work, a commercial policy is essential.
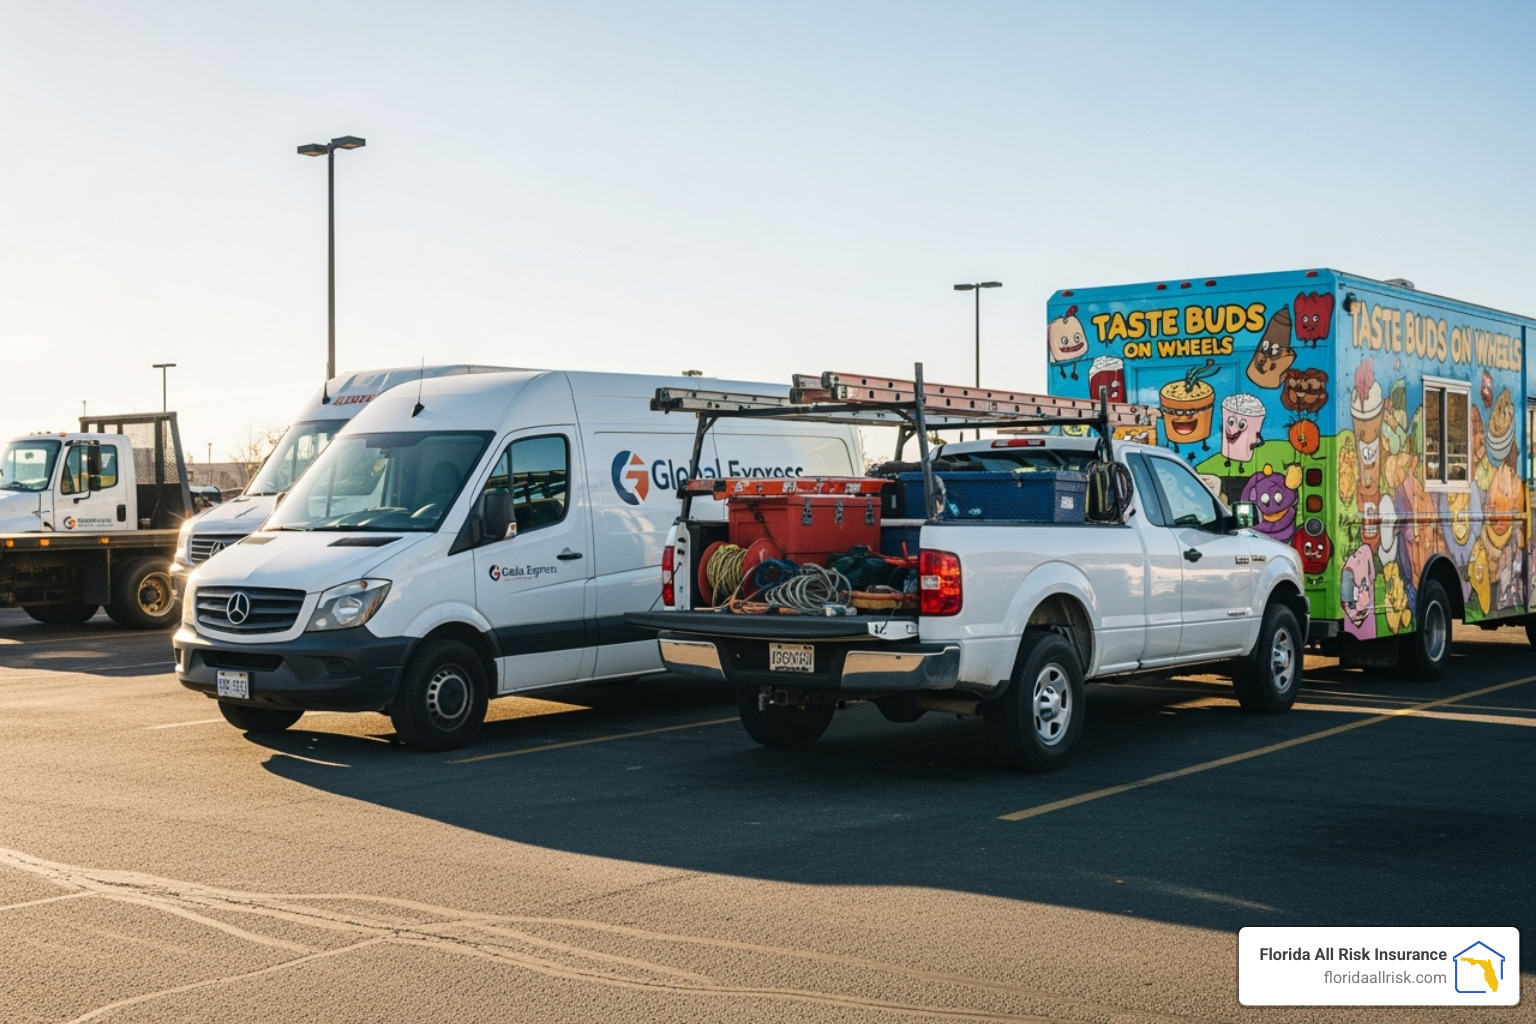
Consider the diverse range of operations that fall under the commercial auto umbrella:
- Contractors & Trades: Plumbers, electricians, roofers, painters, and HVAC technicians using trucks and vans to carry tools and equipment.
- Food & Delivery Services: Food trucks, caterers, local couriers, and florists making regular deliveries.
- Professional Services: Real estate agents, cleaning services, and others who transport clients or supplies.
- Landscapers: Trucks hauling trailers, mowers, and other heavy equipment.
- For-Hire Livery: Taxis, limousines, and rideshare services that transport passengers for a fee.
- Heavy Vehicles: Dump trucks, semi-trucks, and tow trucks with unique and higher liability exposures.
In Florida, state law often requires commercial vehicles to carry a minimum level of liability protection. We help businesses of all sizes find the right policy for their specific needs, whether it’s a single van or an entire fleet.
Decoding Your Commercial Auto Policy: Core & Optional Coverages
Think of your St. Petersburg commercial auto insurance policy as a custom-built shield. Every business has unique risks, and your policy should reflect that reality. A food truck owner faces different risks than a landscaping contractor, and their coverage should reflect those differences. This customization is essential risk management that protects your assets.
Understanding your policy components helps you make informed decisions. When you know what each coverage does, you can choose the right limits and deductibles for your situation. For businesses looking at comprehensive protection, our Business Insurance St. Petersburg solutions can work in tandem with your auto coverage for complete peace of mind.
Essential Coverages for Every Policy
Every commercial auto policy is built on a foundation of core coverages that provide basic protection. These are the essential building blocks that keep your business safe on Florida’s roads.
- Bodily Injury Liability: Covers medical bills, lost wages, pain and suffering, and legal defense costs if your business vehicle is at fault in an accident that injures someone. In today’s litigious environment, a single serious injury claim can easily exceed six figures, making this coverage the cornerstone of your financial protection. Without it, your business assets, and potentially your personal assets, are on the line to satisfy a judgment.
- Property Damage Liability: Pays for the repair or replacement of someone else’s property—like a car, storefront, or fence—that your business vehicle damages. Considering the high cost of vehicles and property repairs, the state minimum is often insufficient, making higher limits a wise investment.
- Personal Injury Protection (PIP): Mandatory in Florida, this no-fault coverage pays for 80% of medical expenses and 60% of lost wages up to $10,000 for you and your passengers, regardless of who caused the accident. It ensures immediate medical care is available without waiting for a fault determination.
- Collision Coverage: Protects your business vehicle when it hits another object or is damaged in a collision. It covers repair costs to get your vehicle back on the road, minus your deductible. For any business that cannot afford to simply replace a vehicle out-of-pocket, this coverage is vital.
- Comprehensive Coverage: Handles damage to your vehicle from non-collision events. For a St. Petersburg business, this is non-negotiable. It covers losses from theft, vandalism, falling objects, fire, and weather-related events like hail, flooding from tropical storms, or damage from a hurricane. Imagine a severe thunderstorm knocks a tree branch onto your work van, or your vehicle is stolen from a job site overnight—comprehensive coverage pays for the repairs or replacement.
- Uninsured/Underinsured Motorist Coverage: Protects you when an at-fault driver has no insurance or not enough to cover the damages to your vehicle and occupants. With a high percentage of uninsured drivers in Florida, this is crucial backup protection that covers your own medical bills and vehicle repairs when the other party can’t.
Popular Add-Ons and Endorsements
While core coverages handle the basics, specialized endorsements can address unique situations and prevent major business disruptions.
- Hired and Non-Owned Auto Liability: This essential endorsement protects your business when you rent a vehicle for a job or an employee uses their personal car for a business errand, like a trip to the post office or a client meeting. If that employee causes an accident, the injured party will likely sue your business. Hired and Non-Owned Auto (HNOA) liability steps in to cover the liability, protecting your company from a lawsuit that their personal policy would deny.
- Roadside Assistance: Provides help for breakdowns, flat tires, or dead batteries, minimizing downtime and keeping your operations running smoothly. For a business on a tight schedule, waiting for help can mean lost revenue and unhappy clients.
- Rental Reimbursement: If your work vehicle is in the shop after a covered accident, this pays for a rental so you can continue serving customers without interruption. This is especially critical for businesses like delivery services or contractors who rely on their vehicle daily.
- Medical Payments Coverage: Supplements your required PIP coverage, offering additional protection for medical expenses for you and your passengers. It can help cover deductibles and co-pays not covered by PIP or health insurance.
- Specialized Equipment Coverage: Protects permanently attached equipment, such as a food truck’s kitchen, a contractor’s custom tool setup, or a landscaper’s lift gate. Standard policies often exclude these expensive modifications, creating a significant coverage gap without this endorsement.
The key is matching your coverage to your actual business risks. We help St. Petersburg businesses identify potential gaps and build comprehensive protection. When combined with Commercial General Liability Insurance, these coverages create a robust safety net for your business.
Staying Compliant: Florida’s Commercial Auto Insurance Laws
Running a business in St. Petersburg means complying with Florida’s vehicle insurance laws. These rules are designed to protect everyone on the road and ensure you are financially responsible and legally protected when operating commercial vehicles.
Florida is a “no-fault” state with specific requirements that can catch business owners off guard. Understanding these laws isn’t just about avoiding penalties—it’s about protecting your livelihood. The state’s Department of Highway Safety and Motor Vehicles (FLHSMV) actively monitors compliance, and the consequences of falling short can be severe. You can find complete details on Florida Auto Insurance Requirements. Getting your st. petersburg commercial auto insurance right from the start is crucial.
Florida’s Minimum Liability and PIP Requirements
Florida’s no-fault system creates specific obligations for commercial vehicle owners to ensure immediate coverage is available after an accident.
- $10,000 in Personal Injury Protection (PIP): Every commercial vehicle must carry this. It pays for 80% of medical expenses and 60% of lost wages for you and your passengers, up to the $10,000 limit, regardless of who is at fault.
- $10,000 in Property Damage Liability (PDL): This covers damage your vehicle causes to someone else’s property. Given that the average new car costs far more than $10,000 and a minor accident can easily damage a building or fence, this minimum often falls short of real-world repair costs, leaving your business to pay the difference.
- Bodily Injury Liability (BIL): Requirements vary based on vehicle type and use. While the base minimum for some vehicles is a “split limit” of 10/20/10—$10,000 per person for bodily injury, $20,000 per accident for bodily injury, and $10,000 for property damage—this is dangerously low for any business. For-hire passenger vehicles, like taxis or limos, are often required to carry much higher limits, such as $125,000/$250,000/$50,000. Commercial trucks involved in interstate commerce are subject to Federal Motor Carrier Safety Administration (FMCSA) regulations, which can mandate liability limits of $750,000 or more, depending on the cargo.
For businesses with larger vehicles, exploring Florida Commercial Truck Insurance is essential, as federal and state regulations mandate significantly higher coverage limits.
The Consequences of Inadequate Coverage
Ignoring Florida’s insurance requirements is a business-ending risk. The state imposes serious penalties that can devastate a St. Petersburg business.
- License and Registration Suspension: The FLHSMV can immediately suspend your vehicle’s registration and your driver’s license, grinding your operations to a halt. You cannot legally operate your vehicles until the insurance is reinstated and all fees are paid.
- Financial Penalties: Reinstatement fees start at $150 for a first offense and increase to $250 for a second and $500 for subsequent violations within a three-year period. These costs are per vehicle and can add up quickly for a fleet.
- Personal Liability: If you cause an accident without adequate coverage, you become personally liable for all damages and injuries. The corporate veil of your LLC or corporation may not protect you if you were negligent in securing proper insurance. This can lead to lawsuits that bankrupt your business and force the liquidation of your personal assets—your home, savings, and investments—to pay for the judgment.
- Reputation Damage: An uninsured accident can destroy customer trust and your business’s reputation in the St. Petersburg community. Being known as a business that doesn’t meet its legal obligations can be incredibly difficult to overcome, making recovery a long and difficult process.
Operating without proper St. Petersburg commercial auto insurance is a gamble that’s simply not worth taking when affordable, comprehensive coverage is accessible.
Navigating St. Petersburg Commercial Auto Insurance Costs and Factors
Understanding how St. Petersburg commercial auto insurance costs are calculated can save you money and ensure you get the right protection. Insurance companies use sophisticated models to assess the risks associated with your specific business operations.
While we always work to find affordable rates, our primary goal is ensuring you have comprehensive protection. Commercial auto insurance reflects the unique risks your business faces. A food truck in downtown St. Pete faces different challenges than a landscaper in the suburbs, and insurers price policies accordingly based on decades of claims data. While commercial policies differ, you can learn about local personal auto costs at Cheap Car Insurance St. Petersburg.
Key Factors That Influence Your Premium
- Business Type: Your industry is a major factor. A construction company with heavy trucks carries more risk than a real estate agent using a sedan. Businesses in hazardous material transport, for-hire passenger services, or long-haul trucking typically see higher premiums due to the liftd risk.
- Vehicle Type and Usage: A heavy-duty pickup truck loaded with tools presents more risk and potential for damage than a small sedan used for occasional errands. How the vehicle is used also matters; daily deliveries across Tampa Bay carry more risk than weekly supply runs within a few miles of your office.
- Employee Driving History: The driving records of all employees who operate company vehicles are scrutinized. Insurers will pull Motor Vehicle Records (MVRs) for every driver. A history of clean driving records helps keep costs down, while multiple speeding tickets, at-fault accidents, DUIs, or other serious violations can significantly increase rates or even make a driver ineligible for coverage under the policy. Proactively managing your team’s driving safety is a direct way to control your insurance costs.
- Location and Travel Radius: Your rates are affected by where your vehicles are garaged and how far they travel. A business operating only within St. Pete faces different risks (e.g., dense urban traffic) than one covering the entire state, as longer distances and highway driving increase accident exposure.
- Coverage Limits and Deductibles: Higher liability limits provide better protection but cost more. A lower deductible means you pay less out-of-pocket after a claim, but your premium will be higher. Finding the right balance is key to managing your budget while staying protected.
- Claims History: A history of frequent or major claims signals higher risk to insurers, leading to increased premiums. This is why a focus on safety and risk management is so important for long-term cost control.
How to Get an Affordable St. Petersburg Commercial Auto Insurance Quote
You can take proactive steps to manage your St. Petersburg commercial auto insurance costs.
- Bundle Your Policies: Combining your commercial auto with other business policies like general liability or a Business Owner’s Policy (BOP) often leads to significant discounts from a single carrier.
- Maintain Excellent Driving Records: Implement clear hiring standards for drivers and regularly review their MVRs. Rewarding safe driving can reinforce good habits and lower your risk profile.
- Implement Safety Programs: Formal programs for vehicle maintenance and driver training show insurers you are serious about preventing claims, often resulting in discounts. This can include implementing a telematics program to monitor driving behavior (like speeding and hard braking), conducting regular safety meetings, establishing a strict no-cell-phone-use policy, and keeping detailed vehicle maintenance logs. These proactive steps demonstrate a commitment to risk management that insurers reward.
- Choose the Right Deductible: Selecting a higher deductible can lower your premium, but ensure you can comfortably cover that amount out-of-pocket if you need to file a claim. We can help you analyze the trade-off.
- Review Your Policy Annually: As your business changes—you buy new vehicles, hire new employees, or change your service area—so do your insurance needs. An annual review ensures you aren’t overpaying or underinsured.
- Work with an Independent Agency: As your Auto Insurance Agent St. Petersburg, FL, we shop multiple carriers to find the best combination of coverage and price for your specific needs, saving you time and money.
Personal vs. Commercial Policies: A Critical Distinction
Understanding the difference between a personal and a commercial auto policy is one of the most important conversations we have with new clients. It’s the difference between being protected and facing financial disaster.
I’ve seen too many St. Petersburg business owners learn this lesson the hard way, with a denied claim after an accident because they relied on personal insurance for business activities. This is a completely avoidable situation that can threaten the very existence of a business.
| Feature | Personal Auto Policy | Commercial Auto Policy |
|---|---|---|
| Coverage Limits | Lower, designed for individual liability | Higher, designed for significant business liability |
| Covered Vehicles | Personal cars, family vehicles | Company-owned vehicles, specialized vehicles, fleets |
| Covered Usage | Commuting, personal errands, recreational use | Business operations, deliveries, client transport, hauling |
| Principal Insured | Individual(s) | Business entity (e.g., LLC, Corporation) |
| Risk Assessment | Based on individual driving record, limited mileage | Based on business type, high mileage, specialized use |
| Exclusions | Often excludes business use, for-hire activities | Custom for business activities, includes specific risks |
The fundamental issue is risk. Personal auto policies are priced and written for the predictable risks of personal activities. The moment you introduce business use—hauling equipment, making deliveries, or transporting clients—you’ve fundamentally changed the risk profile, and your personal policy is likely no longer valid.
Why You Can’t Use a Personal Policy for Business
Your personal auto policy almost certainly contains a “business use exclusion.” This is intentional, as business vehicle use creates substantially different and higher risks that the policy was not designed or priced to cover.
- Higher Liability Risks: Business driving often involves more miles, heavier vehicle loads, valuable cargo or equipment, and tight delivery schedules, all of which statistically increase the risk of an accident. A contractor’s truck loaded with tools and materials poses a greater risk than a personal car on a grocery run. An employee rushing to a client meeting is under different pressures than a casual driver. Commercial policies are designed to underwrite these liftd risks, whereas personal policies are not.
- Vehicle Usage Restrictions: Most personal policies contain specific exclusions for commercial activities like transporting goods for a fee (delivery), using your vehicle as a primary tool of your trade (a contractor’s van), or for-hire livery (transporting people). If you have an accident while performing these activities, your claim will almost certainly be denied.
- Named Insured Issues: A personal policy lists you, the individual, as the ‘named insured.’ However, if your business is structured as an LLC, S-Corp, or Corporation, it is a separate legal entity. In the event of a lawsuit, the business entity will be named. If the business is not the named insured on the policy, the insurer has no obligation to defend it or pay the claim. A commercial policy correctly lists the business entity as the named insured, ensuring the policy protects the entity it’s supposed to.
- Protecting Personal Assets: One of the main reasons to form a business entity is to create a legal separation between your business and personal assets. Using personal insurance for business activities can pierce that corporate veil. If a claim is denied, you could be held personally liable, putting your personal savings, home, and other assets at risk in a lawsuit.
Trying to save a few dollars by using personal insurance for your business is a gamble that could cost you everything. Your business deserves protection that actually works when you need it most. We’ve helped countless St. Petersburg businesses transition to proper St. Petersburg commercial auto insurance, and the peace of mind it provides is invaluable.
How to Secure the Right Coverage in St. Petersburg
Getting the right St. Petersburg commercial auto insurance should be a straightforward process. At Florida All Risk Insurance, we guide you through every step, translating insurance jargon into plain English. The U.S. Small Business Administration also offers helpful resources for business owners looking to understand their insurance needs.
Steps to Obtain a Commercial Auto Quote
Starting the process is simpler than you might think. We’ve broken it down into manageable steps.
- Gather Your Information: Before requesting a quote, collect key details. This includes information about your business operations (industry, services), vehicle information (make, model, year, VIN, special equipment), and driver information (names, birth dates, license numbers).
- Design Your Coverage: We will walk you through different coverage options, limits, and deductibles. Our expertise helps you choose what’s right for your business without being overwhelming.
- Contact an Independent Agent: Once you have your information, reaching out to an independent agency is the next move. We aren’t locked into one company’s offerings and can shop multiple top-rated carriers to find the best combination of coverage and price.
- Compare Quotes: We present your options clearly, explaining what each policy covers and what it costs. You’ll get honest, straightforward information without fine-print surprises.
- Review Your Policy: Before you’re officially protected, we’ll review the policy documents with you to ensure you understand exactly what you’re getting.
To begin the process, you can request an online quote from our website.
Choosing a Reputable Insurance Agency
Picking the right insurance agency is like choosing a business partner—you want someone who understands your needs and has your back.
- The Independent Advantage: As an independent agency, we work for you, not a single insurance company. We compare options from a network of carriers to find you better coverage at better prices.
- Local Knowledge: As a St. Petersburg-based agency, we understand the unique challenges of doing business here, from local traffic patterns to weather risks. This insight helps us recommend coverage that makes sense for your situation.
- Experience with Business Insurance: We specialize in business insurance and understand the complexities of commercial policies, ensuring there are no gaps in your coverage.
- Personalized Guidance: We don’t use one-size-fits-all solutions. We take the time to understand your operations and craft coverage that addresses your specific risks.
When you choose Florida All Risk Insurance, you’re gaining a partner invested in your success and committed to protecting what you’ve worked so hard to build.
Your Partner for St. Pete Business Protection
After diving into St. Petersburg commercial auto insurance, it’s clear this is not just another business expense—it’s the foundation that keeps your business moving forward. Your vehicles are the lifeline of your operations, and without proper coverage, a single accident could jeopardize everything you’ve built.
As we’ve covered, proper commercial auto insurance is essential. It means complying with Florida’s no-fault laws, understanding that state minimums are just a starting point, and recognizing the critical differences between personal and commercial policies. The factors that influence your premium all play into creating a policy that fits your business perfectly.
At Florida All Risk Insurance, we’ve spent over two decades helping St. Petersburg businesses steer these requirements. We’ve seen how the right coverage can save a business and how the wrong coverage can sink one. That’s why we take the time to understand your unique operations, whether you’re a sole proprietor or managing a fleet.
As your independent agents, we shop the market for you, comparing options from multiple top-rated carriers to find coverage that protects your assets without breaking your budget. We translate complex policy language into plain English, helping you make informed decisions about your business’s future.
The road ahead for your St. Petersburg business should be filled with growth and opportunity. Don’t let an uninsured accident become a roadblock to your success. Find the right auto coverage for your business today and drive forward with the confidence that comes from knowing you’re properly protected.
Contact Us
For assistance with your st. petersburg commercial auto insurance needs, our team at Florida All Risk Insurance is here to help.
Florida All Risk Insurance
Address: Saint Petersburg, FL
Phone: (727) 498-5550
Email: [email protected]

