

St Petersburg Car Insurance: Save Big 2025
Your Guide to Navigating Car Insurance in St. Petersburg, FL
St Petersburg car insurance is required by Florida law, and finding the right coverage at an affordable rate can save you hundreds of dollars each year. Whether you’re new to the Sunshine City or looking to switch providers, understanding your options is crucial for protecting both your wallet and your assets.
Top St. Petersburg Car Insurance Companies & Average Rates:
| Company | Full Coverage (Monthly) | Liability Only (Monthly) |
|---|---|---|
| State Farm | $182 | $85 |
| GEICO | $190 | $43 |
| Travelers | $184 | $75 |
| UAIC | $232 | $84 |
| Progressive | $320 | $106 |
Key Facts for St. Pete Drivers:
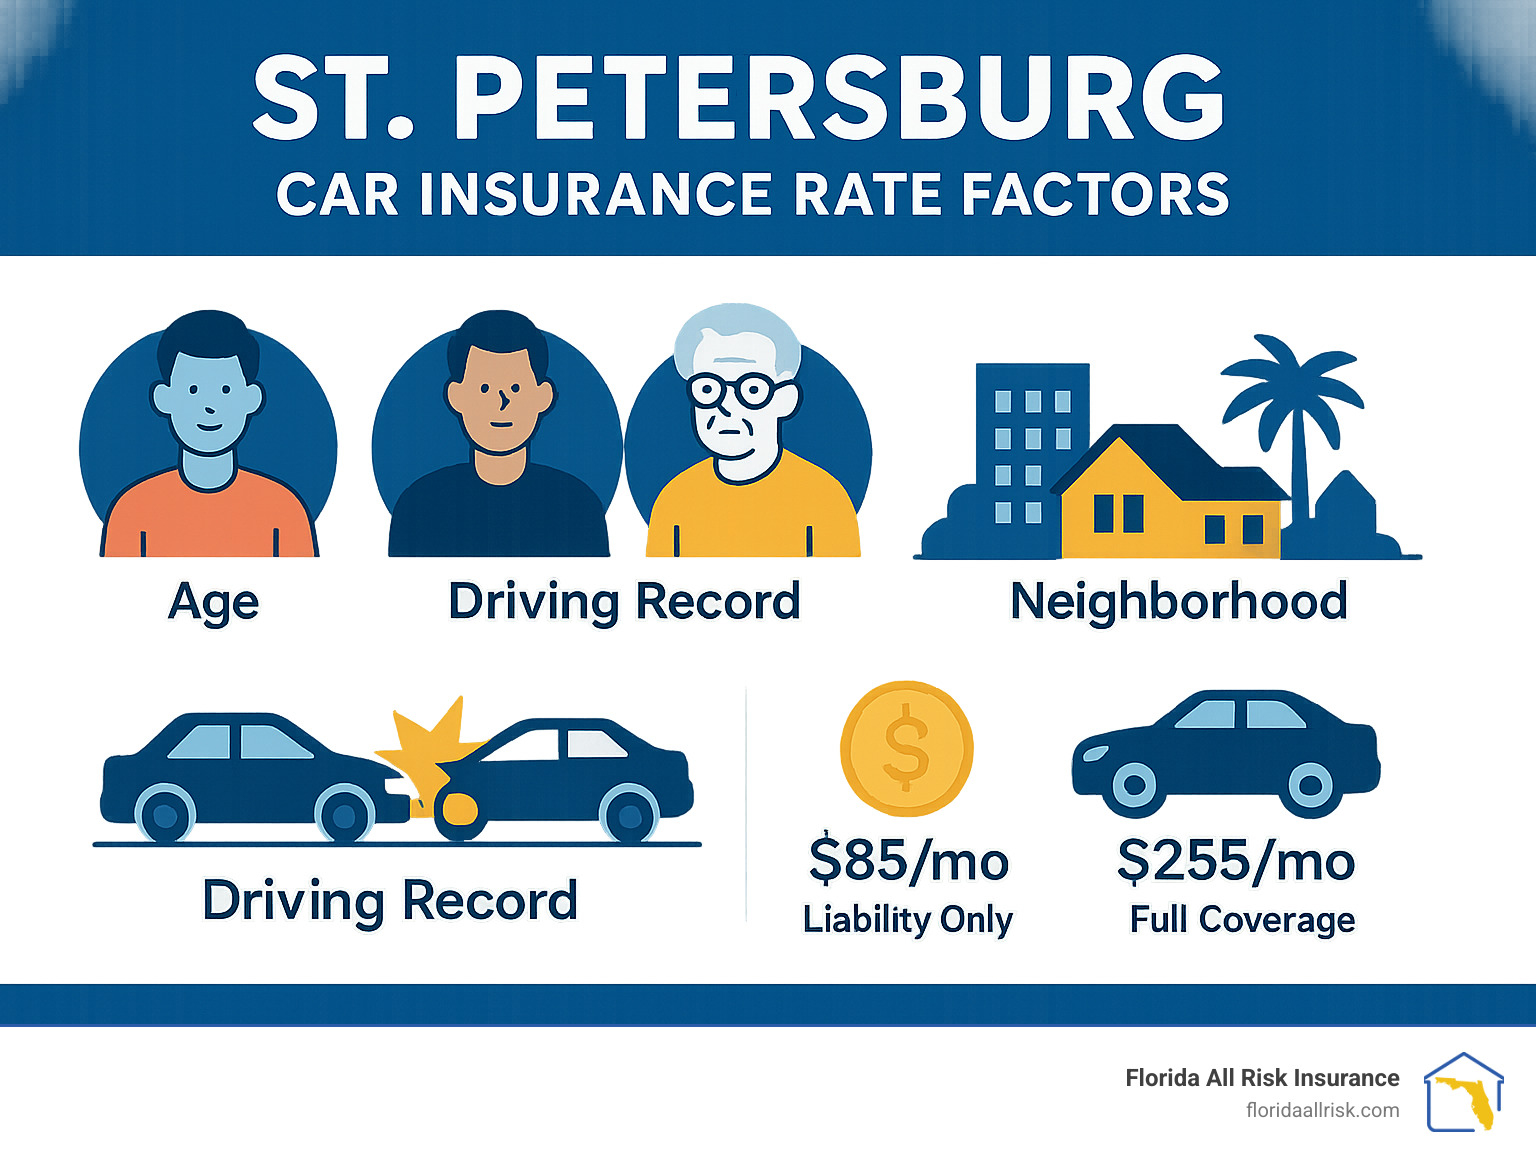
- Average full coverage: $255/month
- Average liability: $85/month
- Florida minimum requirements: $10,000 PIP + $10,000 PDL
- Penalties for no insurance: License suspension + $150-$500 fees
- Rate factors: Age, driving record, credit score, ZIP code
Living in St. Petersburg means dealing with unique driving challenges. The city sees heavy traffic around the I-275 loop, tourist congestion during peak seasons, and the ever-present risk of hurricane-related damage. Pinellas County alone reported over 14,000 car accidents in 2023, making proper coverage essential for local drivers.
Your ZIP code within St. Pete can significantly impact your rates. Drivers in some neighborhoods pay up to $16 more per month than others, with areas like Lealman seeing higher premiums due to accident frequency and population density.
About the Author: I’m Jason Miller, a second-generation insurance professional with over 20 years of experience helping Florida residents find the right coverage. My family has provided St Petersburg car insurance solutions for more than 60 years, giving me deep insight into the local market and the specific challenges drivers face in our coastal community.
Easy st petersburg car insurance word list:
Understanding the Cost of St. Petersburg Car Insurance
When you’re shopping for St Petersburg car insurance, the first question that probably pops into your mind is “How much is this going to cost me?” It’s a fair question, and honestly, one that deserves a straightforward answer. The truth is, your premium depends on a fascinating mix of factors that insurance companies use to calculate your risk profile.
Think of it like this: every time you get behind the wheel, you’re essentially making a bet with your insurance company. They’re betting you’ll drive safely, and you’re betting they’ll be there if something goes wrong. The premium you pay reflects how good or risky that bet looks on paper.
The good news? Once you understand what goes into those calculations, you can often find ways to lower your costs without sacrificing the protection you need. Let’s break down exactly what you can expect to pay and why.
Average Premiums in the Sunshine City
Here’s where things get interesting. If you’re looking for basic liability coverage in St. Petersburg, you’re looking at around $85 per month on average. That’s actually not too shabby when you consider that the Florida state average sits at $87 monthly. We’re slightly ahead of the game here in the Sunshine City!
Now, if you want the peace of mind that comes with full coverage – and trust me, living in hurricane country, you probably do – expect to pay around $255 per month. Again, this beats the Florida average of $286, so we St. Pete residents are catching a bit of a break.
| Coverage Type | St. Petersburg Average Monthly Cost | Florida Average Monthly Cost | National Average Monthly Cost |
|---|---|---|---|
| Minimum Liability | $85 | $87 | $52 |
| Full Coverage | $255 | $286 | $168 |
I’ll be honest with you – those numbers are higher than the national averages of $52 for basic coverage and $168 for full coverage. But before you start packing your bags for Kansas, we’re dealing with unique challenges here. We’ve got tourists who don’t know our roads, hurricane season that can turn your car into a submarine, and let’s face it, Florida drivers have a reputation for a reason!
The reality is that these higher premiums reflect real risks. When you factor in our weather patterns, tourist traffic, and the cost of repairs in Florida, those numbers start to make more sense. Plus, you get to live in paradise year-round, so there’s that trade-off to consider.
For more detailed information about your coverage options, check out More info about auto insurance to understand what protection makes sense for your situation.
Key Factors That Determine Your Rate
Your car insurance premium isn’t pulled out of thin air – it’s based on a detailed analysis of who you are as a driver and what risks you bring to the table. Think of it as your driving DNA, and every factor tells a story about how likely you are to file a claim.
Your driving record is hands down the biggest factor in determining your rates. A clean record is like gold in the insurance world. If you’ve managed to avoid accidents and tickets, you’re rewarded with lower premiums. But if you’ve had an at-fault accident, expect to pay more – sometimes significantly more.
A DUI conviction? That’s when things get really expensive. We’re talking about rate increases that can double or even triple your premium. The insurance company sees a DUI as a red flag that you might make risky decisions behind the wheel, and they price accordingly.
Age and experience play huge roles too. If you’re a teenager or in your early twenties, brace yourself for sticker shock. Young drivers in St. Petersburg can pay over $1,000 per month for full coverage. It’s not personal – it’s just statistics. Young drivers simply get into more accidents, period.
The sweet spot for rates usually hits somewhere in your thirties through fifties. You’ve got enough experience to be a safe driver, but you’re not yet at an age where reflexes might be slowing down. Senior drivers often enjoy excellent rates too, especially those in their sixties who have decades of safe driving behind them.
Your credit history might surprise you as a rate factor, but in Florida, insurers can use your credit score to help determine your premium. The logic is that people who manage their finances responsibly tend to be more responsible drivers too. If your credit needs work, you could be paying up to 93% more than someone with excellent credit.
How much you drive matters more than you might think. If you’re putting 30,000 miles on your car each year, you’re on the road a lot more than someone who drives 8,000 miles annually. More time on the road equals more opportunities for accidents. The good news is that if you don’t drive much, you might qualify for low mileage discounts. You can learn more about how low mileage can slash your Florida car insurance bill and potentially save hundreds of dollars.
The car you drive also influences your rates. A brand-new luxury SUV costs a lot more to repair or replace than a ten-year-old sedan. Sports cars often come with higher premiums because, well, they tend to be driven sportily. On the flip side, vehicles with excellent safety ratings and anti-theft features can help lower your costs.
How Your St. Pete Neighborhood Affects Premiums
Here’s something that catches many people off guard: where you park your car at night can add or subtract dollars from your monthly premium. Insurance companies have gotten incredibly sophisticated at analyzing risk down to the ZIP code level, and the differences can be eye-opening.
Population density plays a big role in this neighborhood effect. Areas with more people generally mean more cars on the road, which translates to more opportunities for fender-benders and more serious accidents. It’s simple math, really.
Traffic congestion is another factor that insurers watch closely. If you live near the I-275 loop or in areas that see heavy tourist traffic, your rates might reflect the increased accident risk that comes with stop-and-go driving and frustrated commuters.
Crime rates in your neighborhood also matter, especially for comprehensive coverage. If car break-ins or vehicle thefts are common in your area, expect to pay more for the coverage that protects against these risks.
Local accident statistics probably have the biggest impact on your rates. Insurance companies track accident data carefully, and if your ZIP code has a history of frequent claims, everyone in that area pays a bit more.
Here in St. Petersburg, these neighborhood variations are real and noticeable. The average full coverage rate of $255 can swing quite a bit depending on exactly where you live. In ZIP code 33701, you might pay right around that $255 average. But drive over to 33708, and you could save about $12 per month with rates around $243. Head to 33705, and you might pay a few dollars more at $257.
Some neighborhoods see even bigger variations. Lealman, for example, tends to be one of the pricier areas for St Petersburg car insurance, with rates averaging around $293 monthly. Meanwhile, areas like Madeira Beach often enjoy slightly lower premiums.
The key thing to remember is that these variations reflect real differences in risk. While it might seem unfair that your ZIP code affects your rates, the data shows genuine differences in accident frequency, crime rates, and other factors that influence insurance costs. Understanding this can help you make informed decisions about where to live and what coverage levels make sense for your specific situation.
Florida’s Legal Requirements and Local Driving Realities
Understanding Florida’s insurance laws isn’t just about staying legal – it’s about protecting yourself and your family on the roads we all share. Living in St. Petersburg means navigating both state requirements and our city’s unique driving challenges, and we want to make sure you’re prepared for both.
Minimum Car Insurance Requirements in St. Petersburg
Florida takes a different approach to car insurance than many states – we’re what’s called a “no-fault” state. This means that after an accident, your own insurance company pays for your medical bills first, regardless of who caused the crash. It’s designed to get people the medical care they need quickly, without waiting for fault to be determined.
To legally drive in St. Petersburg, you need two specific types of coverage. Personal Injury Protection (PIP) is the heart of Florida’s no-fault system. This coverage handles 80% of your medical expenses and 60% of your lost wages, up to $10,000 total. Whether you’re the driver or a passenger, PIP kicks in to cover your injuries. The second requirement is Property Damage Liability (PDL), which covers damage you might cause to someone else’s property – their car, mailbox, fence, or anything else you might accidentally hit. The state requires a minimum of $10,000 in PDL coverage.
So your basic St Petersburg car insurance needs to include $10,000 in PIP and $10,000 in PDL. While these are the legal minimums, many of our clients find that real-world accidents can easily exceed these limits. A trip to the emergency room alone can cost more than $10,000, and vehicle repairs today are surprisingly expensive.
Some drivers need special filings called SR-22 or FR-44 forms. These aren’t insurance policies themselves, but rather certificates that prove you’re carrying the required coverage. They’re typically required after serious violations like DUI convictions. If you’re dealing with this situation, our guide on DUI Auto Insurance Florida can help you understand your options. For more details about basic coverage, check out our resource on Liability Car Insurance Florida.
Penalties for Driving Uninsured
Florida doesn’t mess around when it comes to uninsured drivers. The penalties are designed to be serious enough that most people think twice before hitting the road without coverage.
If you’re caught driving without valid insurance, the state will suspend both your driver’s license and your vehicle registration for up to three years. Getting them back isn’t cheap or simple. First-time offenders face a $150 reinstatement fee, but if you’re caught again within three years, that fee jumps to $250. Repeat offenders can face $500 in fees along with extended suspension periods.
Beyond the legal penalties, driving uninsured puts you at enormous financial risk. Without insurance, you’re personally responsible for any damage or injuries you cause. Imagine causing a serious accident and having to pay for multiple people’s medical bills, vehicle repairs, and property damage out of your own pocket. A single serious accident could easily cost hundreds of thousands of dollars – enough to bankrupt most families.
The bottom line is simple: the cost of insurance is always less expensive than the cost of not having it. We’ve seen too many families face financial ruin because they thought they could skip coverage.
St. Petersburg’s Unique Driving Environment
Our city is beautiful, but it presents some driving challenges that make having proper insurance even more important. Understanding these local factors helps explain why St Petersburg car insurance rates are what they are, and why comprehensive coverage makes sense here.
Pinellas County has a concerning number of car accidents each year. In 2023, we saw 14,819 crashes with 111 fatalities – a slight improvement from 2021’s 16,464 crashes and 158 deaths, but still significant numbers that affect everyone’s insurance rates. These statistics aren’t just numbers; they represent real families and real consequences on our local roads.
Anyone who drives regularly in St. Pete knows about our traffic challenges. The I-275 loop can be a parking lot during rush hour, and areas like Central Avenue see constant congestion. More cars in closer proximity naturally leads to more fender benders and serious collisions. Add in construction zones from ongoing city improvement projects, and you have even more opportunities for accidents.
Tourist season brings its own set of challenges. Our beautiful beaches and attractions like the St. Pete Pier draw visitors from around the world, which is wonderful for our economy but challenging for our roads. Tourists unfamiliar with local traffic patterns can create unpredictable driving situations, especially around popular destinations.
Living in Florida means preparing for hurricane season every year. While your homeowners insurance might cover some storm damage, it typically won’t protect your vehicle from flooding. Comprehensive auto coverage becomes crucial during hurricane season, protecting your car from flood damage, fallen trees, and flying debris. We’ve all seen the aftermath of major storms, and the cars that weren’t properly insured.
St. Petersburg continues investing in infrastructure improvements, including projects like the North Shore Park Seagrass Bank Mitigation Project. These improvements are great for our city’s future, but construction zones temporarily add complexity to our daily commutes.
All these factors combine to create a driving environment where having the right insurance isn’t just about following the law – it’s about protecting yourself, your family, and your financial future in a city we all love to call home.
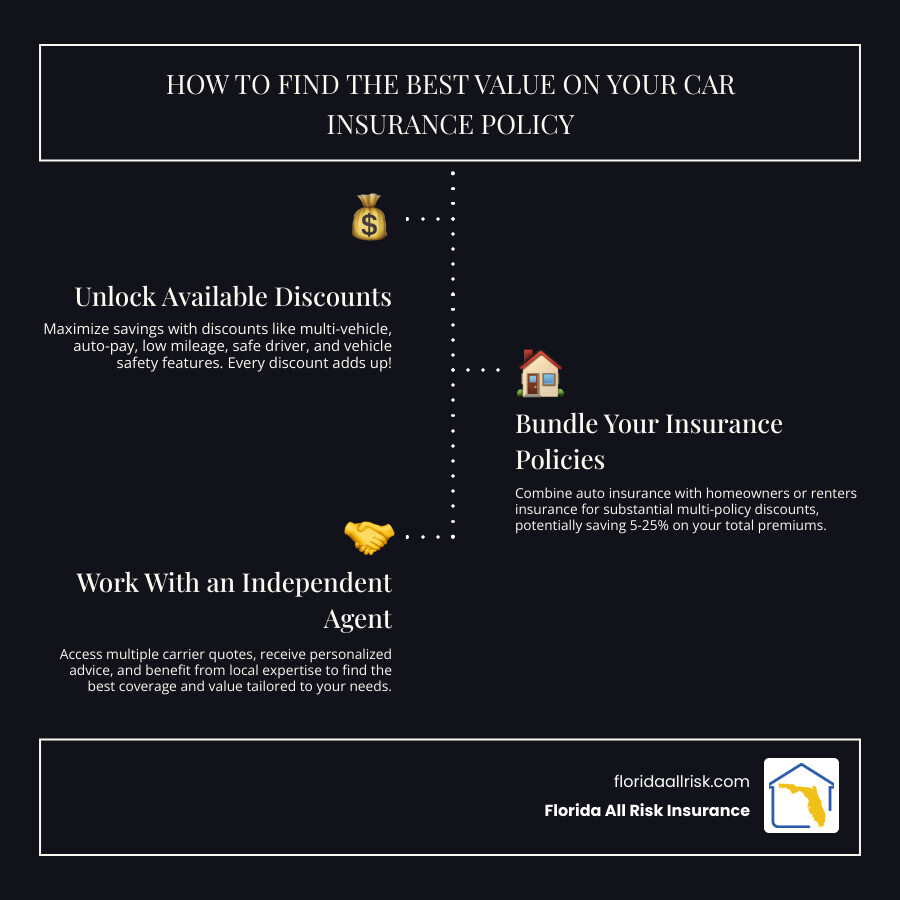
How to Find the Best Value on Your Policy
Finding affordable St Petersburg car insurance doesn’t have to be a scavenger hunt. We believe in empowering you with the knowledge to make smart choices and secure the best value for your needs.
Open up Common Car Insurance Discounts
One of the easiest ways to save money is by taking advantage of discounts. Most insurers offer a variety of ways to lower your premium. Here are some common ones you should ask about:
- Good Student Discount: If you have a young driver on your policy with good grades, this can lead to significant savings.
- Safe Driver Discount: Maintaining a clean driving record for a certain period (e.g., three or five years) often qualifies you for a discount.
- Low Mileage Discount: If you don’t drive much, you pose less risk, and insurers may reward that with a lower rate.
- Multi-Vehicle Discount: Insuring more than one car with the same company often results in a discount on all vehicles.
- Auto-Pay Discount: Setting up automatic payments can sometimes earn you a small discount.
- Paperless Billing Discount: Opting for electronic statements can also lead to minor savings.
- Customer Loyalty Discount: Staying with the same insurer for an extended period can be rewarded.
- Defensive Driving Course Discount: Completing an approved defensive driving course might reduce your rates.
- Vehicle Safety Features Discount: Cars with advanced safety features like anti-lock brakes, airbags, or anti-theft systems can qualify for discounts.
We can help you identify all the discounts you qualify for. Check out our detailed guide on Florida Car Insurance Discounts for more ways to save.
The Power of Bundling Your Policies
One of the most effective ways to reduce your overall insurance costs is by bundling multiple policies with the same provider. This often leads to a “multi-policy discount” that can be quite substantial.
- Bundling Auto and Home Insurance: This is a classic combination. If you own a home in St. Petersburg, combining your auto and Homeowners Insurance in Pinellas County Florida with us can lead to significant savings, potentially 5-10% or even more on your total bill.
- Bundling Auto and Renters Insurance: Even if you rent, you can still bundle! Many St. Petersburg residents rent their housing (almost 40%), and combining your auto policy with renters insurance can protect your belongings and liability, while also qualifying you for a discount. Some sources suggest this can lead to a 25% discount on the total bill.
- Simplified Management: Beyond the savings, bundling simplifies your insurance management. You’ll have one point of contact, one bill, and one renewal date, making your life a little easier.
Why Work With an Independent Insurance Agent?
When it comes to securing the best St Petersburg car insurance, working with an independent insurance agent, like us at Florida All Risk Insurance, offers distinct advantages.
- Comparing Multiple Carriers: Unlike captive agents who work for a single company, we partner with a wide range of national and regional insurance providers. This means we can shop around on your behalf, comparing coverage options and prices from numerous companies to find the best possible value for your specific needs. We’re like your personal insurance matchmakers!
- Personalized Advice: We take the time to understand your unique situation, driving habits, and financial goals. Our team has over 60 years of combined insurance experience, allowing us to offer custom advice and custom insurance plans. We’re here to change a stressful insurance experience from a sigh to a smile.
- Local Expertise: As a St. Petersburg-based agency, we understand the local driving conditions, risks, and community nuances. We can offer insights into how factors like hurricane season or specific traffic patterns might affect your coverage needs. We’re focused on being neighborly, providing affordability, and ensuring convenience.
- One-Stop Shop: Beyond auto insurance, we can help you with homeowners, flood, life, boat, and commercial insurance. This makes bundling easy and ensures all your assets are protected under one roof.
- Finding the Right Fit: Our goal is to provide complete coverage at the best prices carriers offer, ensuring you have the right policy that protects you without emptying your wallet. We are thorough in ensuring clients have the right policy for their needs and business.
- Verifying Credentials: It’s always a good practice to verify an agent’s credentials. You can check an agent’s background with FINRA’s BrokerCheck to ensure they are licensed and reputable.
Choosing an independent agent means you have an advocate on your side, dedicated to finding you the best policy, not just selling you a product. Learn more about Why You Should Work With an Independent Insurance Agency on our website.
Frequently Asked Questions about St. Petersburg Car Insurance
We hear a lot of questions about St Petersburg car insurance, and we’re always happy to provide clear, straightforward answers. After helping thousands of drivers in our community, we’ve noticed these same questions come up time and again. Let’s explore the ones that matter most to you.
What is the difference between minimum and full coverage car insurance?
This is probably the most important question we get, and for good reason! Understanding the difference between minimum and full coverage can save you from a financial headache down the road.
Minimum coverage in Florida means you’re carrying exactly what the law requires: $10,000 in Personal Injury Protection (PIP) and $10,000 in Property Damage Liability (PDL). Your PIP takes care of your medical bills (up to the limit) regardless of who caused the accident, while PDL covers damage you cause to someone else’s property.
Here’s the catch though – minimum coverage doesn’t protect your own vehicle if you’re at fault in an accident. If you crash into a tree or another car and it’s your fault, you’re on your own for repairs or replacement.
Full coverage is like having a safety net with much tighter weaving. It typically includes everything from minimum coverage plus Collision coverage (which pays for damage to your car from accidents), Comprehensive coverage (protecting against theft, vandalism, and weather damage – crucial here in hurricane country), and Bodily Injury Liability (covering injuries you cause to others beyond what PIP provides).
We also strongly recommend Uninsured/Underinsured Motorist coverage. While Florida doesn’t require it, given that Pinellas County sees over 14,000 accidents annually, you want protection when the other driver doesn’t have enough insurance to cover your damages.
If your car is financed or leased, your lender will require full coverage – they want their investment protected too. For personalized quotes and coverage options, check out more info about car insurance quotes on our website.
How much does a DUI raise car insurance rates in St. Petersburg?
A DUI conviction hits your St Petersburg car insurance rates like a financial hurricane. We wish we had better news, but it’s important you understand the reality.
Your rates can easily double or even triple after a DUI. A driver who was paying $2,990 annually might suddenly face bills of $4,365 or higher. That’s an extra $1,375 per year – money that could have gone toward so many better things.
Beyond the rate increase, you’ll be classified as a high-risk driver, which means some insurance companies simply won’t cover you at all. The ones that will often specialize in high-risk situations and charge accordingly.
Florida also requires FR-44 filing after most DUI convictions. This means you need much higher liability limits than the standard minimums – we’re talking $100,000/$300,000 for bodily injury and $50,000 for property damage. These higher requirements add even more to your costs.
The financial impact typically lasts for three to five years, though it can affect your rates for even longer. It’s one of those situations where the true cost goes far beyond the initial court fines and fees. If you’re dealing with this situation, we have resources on DUI Auto Insurance Florida to help you steer your options.
Does my car insurance cover a rental car in Florida?
This question comes up a lot, especially during our busy tourist season when rental cars are everywhere. The answer depends on what coverage you have on your personal vehicle.
If you have comprehensive and collision coverage on your own car, this protection typically extends to rental cars for up to 30 days. Your liability coverage usually travels with you too, so you’re covered if you cause an accident in the rental.
However, there are some important details to consider. Your rental car coverage is typically limited to the value of your own vehicle and subject to your same deductible. So if you drive a 10-year-old sedan but rent a luxury SUV, you might have a coverage gap.
The rental company will offer you a Loss Damage Waiver (LDW), sometimes called Collision Damage Waiver. This waives your responsibility for damage to their car. If you have robust collision and comprehensive coverage with a low deductible, you might not need it. But if your deductible is $1,000 and the LDW costs $15 per day for a week-long rental, it might be worth the peace of mind.
Don’t forget about your credit card benefits either. Many credit cards offer secondary rental car insurance, meaning they’ll cover costs after your primary insurance kicks in. This can help with deductibles or coverage gaps.
The smartest approach? Give us a call before you rent. We can review your specific policy and help you understand exactly what’s covered and what isn’t. You can always contact an auto insurance agent in St. Petersburg, FL for personalized advice that takes the guesswork out of rental car coverage.
Your Next Steps for Affordable Coverage
Navigating the complexities of St Petersburg car insurance can seem daunting, but it’s a vital step in protecting your financial future and ensuring peace of mind on the road. We hope this guide has shed some light on the factors influencing your rates, the legal requirements, and the many ways you can save.
Our mission at Florida All Risk Insurance is to provide you with personalized solutions that balance cost and protection. As an independent agency, we’re dedicated to helping you find the right policy from a wide range of carriers, custom to your unique needs. We believe in securing your peace of mind, one policy at a time.
Don’t let the search for affordable car insurance stress you out. Let us do the heavy lifting. We invite you to Get a personalized auto insurance quote today and find how we can help you save while ensuring you’re fully protected.
Contact Us
Ready to secure the perfect St Petersburg car insurance policy? We’d love to help you steer your options and find coverage that fits both your needs and your budget.
At Florida All Risk Insurance, we’re more than just an insurance agency – we’re your neighbors here in St. Petersburg. Our team understands the unique challenges of driving in our beautiful coastal city, from hurricane season preparations to navigating tourist traffic around the Pier.
Getting in touch with us is easy. You can call us directly at (727) 289-5907 during business hours to speak with one of our experienced agents. We’re always happy to answer questions, provide quotes, or help you understand your coverage options. No question is too small, and we believe in taking the time to explain things clearly.
If you prefer to reach out via email, you can contact us at [email protected]. Whether you’re looking for a quick quote, need help with a claim, or just want to discuss your current coverage, we’ll get back to you promptly.
Our office is conveniently located right here in Saint Petersburg, FL, making us easily accessible to local residents throughout Pinellas County. As an independent agency with deep roots in the community, we’re committed to providing the personalized service that only comes from working with people who truly understand your neighborhood.
For the fastest response and most comprehensive assistance, we encourage you to visit our Contact Us page on our website. There you’ll find additional ways to connect with us and can even start the process of getting your personalized quote.
Florida All Risk Insurance
Saint Petersburg, FL
Phone: (727) 289-5907
Email: [email protected]

