

Finding the Best Auto Insurance Rates in St. Petersburg
When it comes to st petersburg auto insurance quotes, local drivers often face a bit of sticker shock. St. Pete residents typically pay around $294 per month for full coverage—that’s about $22 more than the Florida state average of $272. But don’t worry! There are still plenty of ways to find affordable coverage in our beautiful coastal city.
As a St. Petersburg driver myself, I’ve helped hundreds of locals steer these waters. The sunshine and palm trees come with some insurance challenges—our hurricane risk and Florida’s unique no-fault insurance system both play significant roles in our rates.
| Quick Facts: St. Petersburg Auto Insurance | Details |
|---|---|
| Average Monthly Cost (Full Coverage) | $294 |
| Average Monthly Cost (Liability Only) | $106 |
| Cheapest Full Coverage Provider | $182/month |
| Cheapest Liability Provider | $43/month |
| Required Coverage in Florida | $10,000 PIP, $10,000 Property Damage Liability |
Whether you’re commuting downtown, heading to the beach, or just cruising through the neighborhood, your location makes a difference. Those st petersburg auto insurance quotes you receive will vary based on where exactly you live—downtown drivers face different risks than those in Pinellas Point or Shore Acres.
The good news? Shopping around truly pays off here. Our research shows some carriers offer full coverage at $182 per month—that’s a whopping 38% below the city average! For drivers with credit challenges, we’ve found rates around $232 monthly, which is 59% below what many others charge for similar situations.
Your premium isn’t set in stone. It’s shaped by several personal factors: your age and driving record naturally play major roles, but so does your ZIP code, credit score, and even what type of car you drive. Available discounts can also make a huge difference—bundling policies, maintaining a clean driving record, or even taking defensive driving courses can lead to significant savings.
I’m Jason Miller, and I’ve spent over 20 years helping Florida residents find affordable coverage through Florida All Risk Insurance. This isn’t just business for me—as a second-generation insurance professional, I’ve witnessed how our volatile Florida insurance market has evolved, especially for St. Petersburg drivers.
If you’re new to insurance shopping or just want to brush up on some terminology, here are a few resources that might help:
- Best car insurance discounts – Learn which discounts could save you the most
- Uninsured motorist coverage Florida – Essential protection in a state with many uninsured drivers
- Liability car insurance Florida – Understanding the basics of what’s required
Those st petersburg auto insurance quotes can vary dramatically between companies—often by hundreds of dollars for identical coverage. That’s why comparing multiple options isn’t just smart—it’s essential for your wallet!
St. Petersburg Auto Insurance Quotes: Rate Factors & Legal Basics
When shopping for st petersburg auto insurance quotes, understanding what influences your rates is crucial. Florida’s unique insurance landscape combines no-fault requirements with coastal risks that directly impact what you’ll pay.
Florida law requires all drivers to carry at least $10,000 in Personal Injury Protection (PIP) and $10,000 in Property Damage Liability (PDL). While these minimums keep you legal, they rarely provide adequate protection. A single accident can easily exceed these limits, leaving you financially exposed.
“Insurance rates in St. Petersburg vary significantly based on multiple factors,” explains our senior agent at Florida All Risk Insurance. “We see premiums differ by hundreds of dollars between similar drivers based on their exact location, driving history, and credit score.”
Your driving record plays perhaps the biggest role in your st petersburg auto insurance quotes. Drivers with a DUI in St. Petersburg pay an average of $469 per month for full coverage—60% more than those with clean records. It’s a costly reminder that safe driving isn’t just about avoiding accidents; it’s about protecting your wallet too.
Age factors significantly into your rates as well. Teen drivers face the steepest premiums, while rates typically level off around age 35 and gradually decline as you get older. A 20-year-old might pay twice what a 60-year-old pays for identical coverage, even with the same driving history.
Interestingly, your credit score impacts your rates just as much as a DUI. Drivers with poor credit in St. Petersburg pay an average of $469 per month for full coverage—the same increase as having a serious driving violation. This is why improving your credit can be as valuable as maintaining a clean driving record.
The vehicle you drive matters too. More expensive cars, sports models, and vehicles with poor safety ratings cost more to insure. That sleek sports car might turn heads, but it’ll also turn your premium up significantly compared to a family sedan.
Living in Florida’s sunshine comes with a stormy side. St. Petersburg’s vulnerability to hurricanes and tropical storms increases comprehensive coverage costs. According to AccuWeather research, our city faces significant hurricane risk each season, with potential storm surges of 12-15 feet that could flood 42% of Pinellas County households. This environmental risk directly impacts comprehensive coverage rates, especially for vehicles parked in flood-prone areas.
For drivers with serious violations, SR-22 or FR-44 requirements can dramatically increase premiums. These special filings tell the state you’re maintaining proper insurance after a serious violation, but they come at a significant cost.
What “st petersburg auto insurance quotes” Really Cover
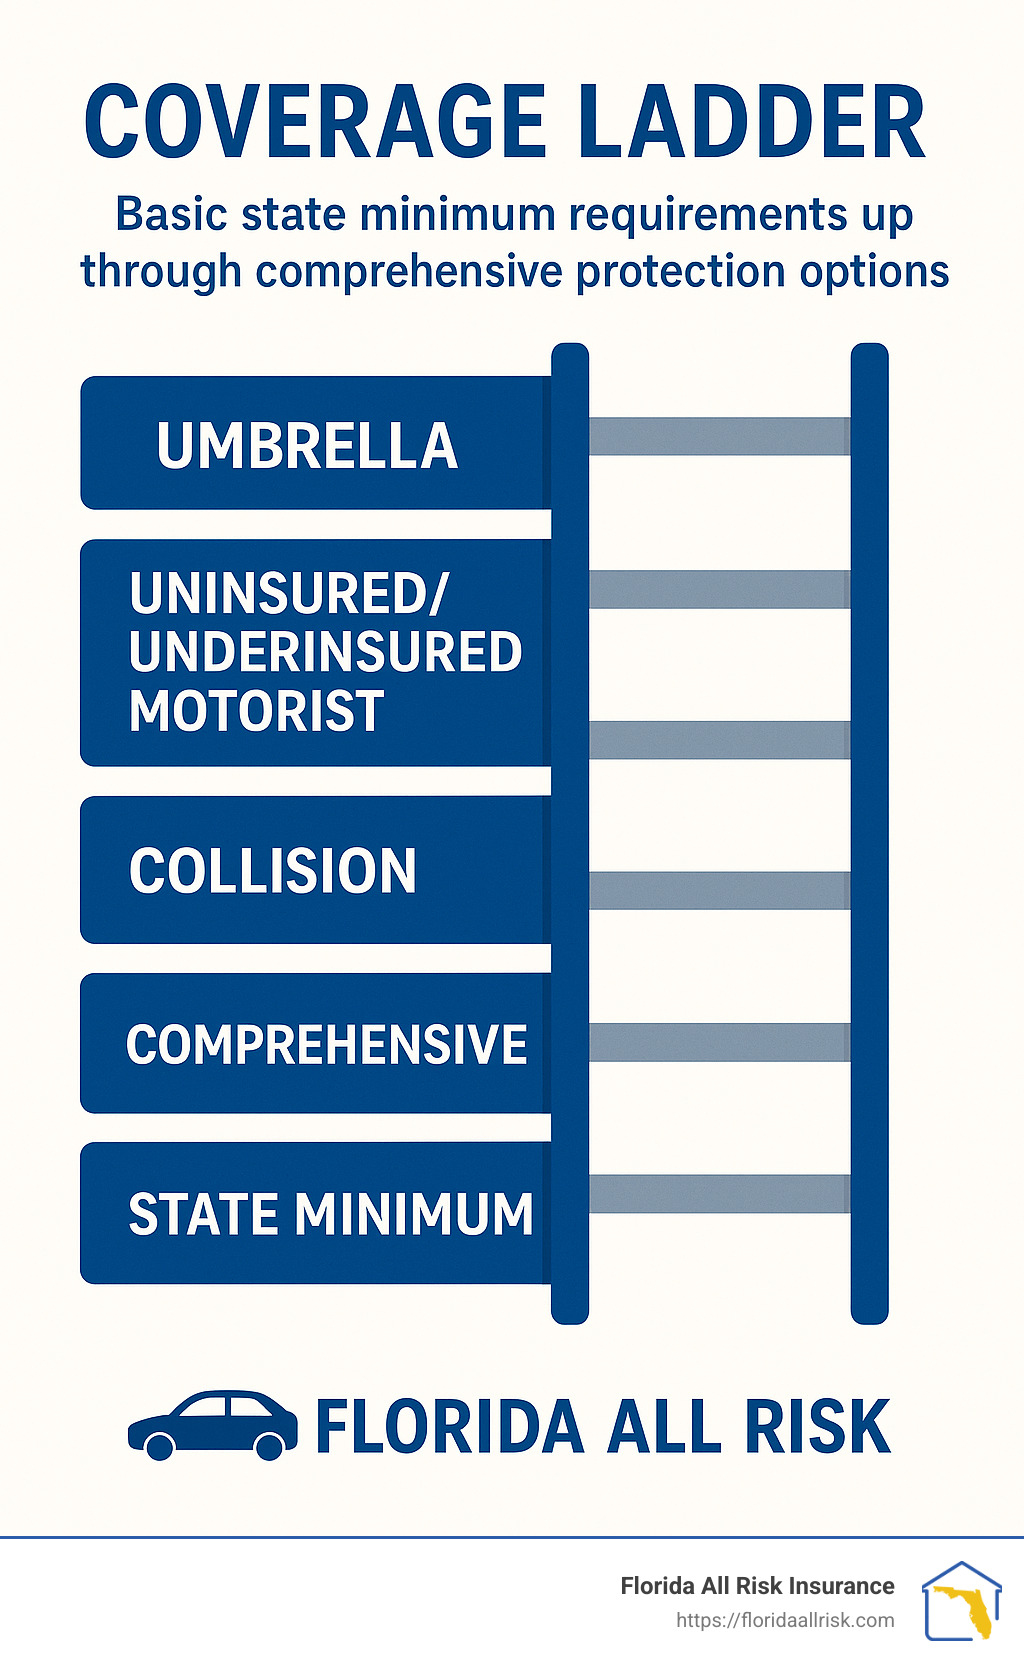
When comparing st petersburg auto insurance quotes, you’ll encounter several coverage types that serve different purposes.
Liability Coverage pays for damage you cause to others, including both bodily injury and property damage. While Florida only requires PDL, we strongly recommend adding Bodily Injury Liability to protect your assets. Without it, you could be personally sued for medical costs you cause in an accident.
Personal Injury Protection (PIP) is the cornerstone of Florida’s no-fault system. It covers 80% of your medical expenses and 60% of lost wages up to $10,000, regardless of who caused the accident. This mandatory coverage ensures you get prompt medical treatment without waiting for fault determination.
Comprehensive Coverage protects against non-collision incidents like theft, vandalism, fire, flooding, and hurricane damage. Given St. Petersburg’s weather risks, this coverage isn’t just optional—it’s practically essential. Just ask our client Maria: “I never thought I’d need comprehensive coverage until my parked car was damaged by flying debris during Hurricane Irma. That $12 extra per month saved me from a $4,800 repair bill.”
Collision Coverage pays for damage to your vehicle from accidents, regardless of fault. If you have a car loan or lease, your lender will require this coverage, but even if you own your vehicle outright, it provides valuable protection for your investment.
Uninsured/Underinsured Motorist Coverage is particularly important in Florida, where approximately 20% of drivers are uninsured. This protects you when the at-fault driver can’t cover your damages, preventing you from paying out-of-pocket for someone else’s mistake.
Key Laws That Shape St. Petersburg Auto Insurance Quotes
Florida Statute 627 establishes the state’s no-fault insurance system, which significantly impacts how st petersburg auto insurance quotes are structured.
The no-fault threshold is a key concept to understand. You can only sue another driver if injuries meet certain severity thresholds, such as significant scarring or permanent injury. This limitation affects how insurance companies structure their policies and price their coverage.
If you’re convicted of a DUI, Florida requires you to file an FR-44 form and carry much higher liability limits, typically $100,000/$300,000/$50,000. This requirement can double or even triple your insurance costs for several years.
Timing matters in Florida insurance claims. You must report accidents within 10 days and file PIP claims within 14 days of the incident to qualify for benefits. Missing these deadlines can result in denied claims, leaving you responsible for expenses that should have been covered.
To receive the full $10,000 in PIP benefits, you must seek medical treatment within 14 days of an accident. This “14-day rule” catches many drivers by surprise, especially those who think minor injuries don’t need immediate attention.
These legal requirements create a unique insurance environment in St. Petersburg that differs from many other states, making local expertise particularly valuable when shopping for coverage. At Florida All Risk Insurance, we help steer these complexities so you can focus on finding the best protection at the right price.
Average Costs, Neighborhood Variations & Savings Opportunities
If you’re shopping for car insurance in St. Petersburg, you might experience a bit of sticker shock. The average cost of st petersburg auto insurance quotes for full coverage is $294 per month (or $3,528 annually), which is $22 more per month than the Florida state average. If you’re looking to save with liability-only coverage, you’ll pay around $106 monthly ($1,272 annually).
But here’s the thing about averages – they don’t tell the whole story. Your personal situation can dramatically change what you’ll pay. Let me break it down for you.
Age plays a huge role in what you’ll pay. Teenagers might shell out $600–$800 monthly for full coverage (ouch!), while drivers in their 50s and 60s enjoy some of the best rates at $200–$300 monthly. Even seniors in their 70s typically pay less than young drivers, with rates around $230–$330 monthly.
Your credit score matters just as much as your driving record in Florida. With excellent credit, you might pay between $210–$260 monthly for full coverage. But if your credit is poor, that same policy could cost $400–$550 monthly. That’s potentially double the rate for identical coverage!
Speaking of driving records, that fender-bender might cost more than you think. While a clean record gets you that average $294 monthly rate, a single speeding ticket jumps to $347 (an 18% increase). An at-fault accident? Now you’re looking at $429 monthly (46% increase). And a DUI will typically cost you $469 monthly – a whopping 60% more than drivers with clean records.
As Maria, one of our long-time clients, told me last week: “I had no idea my credit score affected my car insurance so much. When I improved it from poor to good, my premium dropped by almost $100 a month!”
Affordable Options for Different Drivers
The good news? Different insurance companies weigh these factors differently, which means shopping around can save you hundreds – or even thousands – per year.
For drivers with clean records seeking full coverage, we’ve found rates as low as $182 monthly. That’s over $100 less than the city average! Other carriers offer competitive rates of $222 and $230 monthly, respectively.
Young drivers (those energetic 18–25-year-olds with little experience but lots of enthusiasm) can find liability-only coverage for about $99 monthly or $105 through different carriers. If they need full coverage, some insurers tend to be most forgiving at $280 monthly.
Got a speeding ticket? Some carriers barely penalize you with just an 8% increase, bringing rates to about $196 monthly. That’s significantly better than most competitors.
After an accident, certain insurance providers show mercy with just a 16% increase (to $212 monthly), while others come in second with a 24% increase (to $275 monthly).
Even drivers with serious issues like DUIs or poor credit have options. We’ve found post-DUI coverage at $297 monthly (37% below the city average), while other carriers provide remarkable rates for drivers with poor credit at $232 monthly – an incredible 59% below the city average.
I’ll never forget Robert’s face when we found him a new policy after his speeding ticket. “My previous company wanted an extra $100 monthly,” he told me, “but you found me coverage for just $14 more than my old rate. That difference is paying for my daughter’s dance lessons!”
How Your Neighborhood Affects st petersburg auto insurance quotes
In St. Petersburg, your ZIP code doesn’t impact your rates as dramatically as in bigger cities like Miami, but differences still exist. The variation between neighborhoods is typically around $16 monthly – not enormous, but still worth considering.
Residents in ZIP code 33710 (West St. Petersburg) pay around $4,307 annually for full coverage, benefiting from moderate traffic and lower theft rates. Move to South St. Petersburg (33712), and you’ll pay slightly more at $4,350 annually due to higher traffic density and slightly liftd accident rates.
Downtown and waterfront areas (33701) face the highest rates at about $4,390 annually. This makes sense when you consider the tourist traffic, flood exposure from being near the water, and higher vehicle density. Central St. Petersburg (33713) falls in the middle at $4,320 annually with its mix of residential and commercial properties.
Several neighborhood factors affect your st petersburg auto insurance quotes, including local theft and vandalism statistics, traffic patterns, proximity to flood-prone coastal areas, and even whether you park on the street or in a garage. Your daily commute matters too – driving through high-accident intersections regularly can impact your rates.
Unlike some parts of Florida where ZIP code can create dramatic price differences, St. Petersburg’s relatively consistent pricing across neighborhoods is actually good news for residents. It means you won’t be severely penalized just because of your address, though other personal factors will still significantly impact what you pay.
As one client who moved from Miami to St. Petersburg told me with relief, “I was paying $500 monthly in Miami for the same coverage I’m now getting for $285 in St. Pete. I should have moved years ago!”
How to Compare Quotes & Open up Discounts
Getting the best st petersburg auto insurance quotes requires a bit of strategy and know-how. Think of it as a treasure hunt where the prize is saving hundreds of dollars every year!
Step-by-Step: Getting Accurate st petersburg auto insurance quotes
Comparing quotes isn’t just about finding the cheapest price—it’s about finding the best value for your specific situation. Here’s how to do it right:
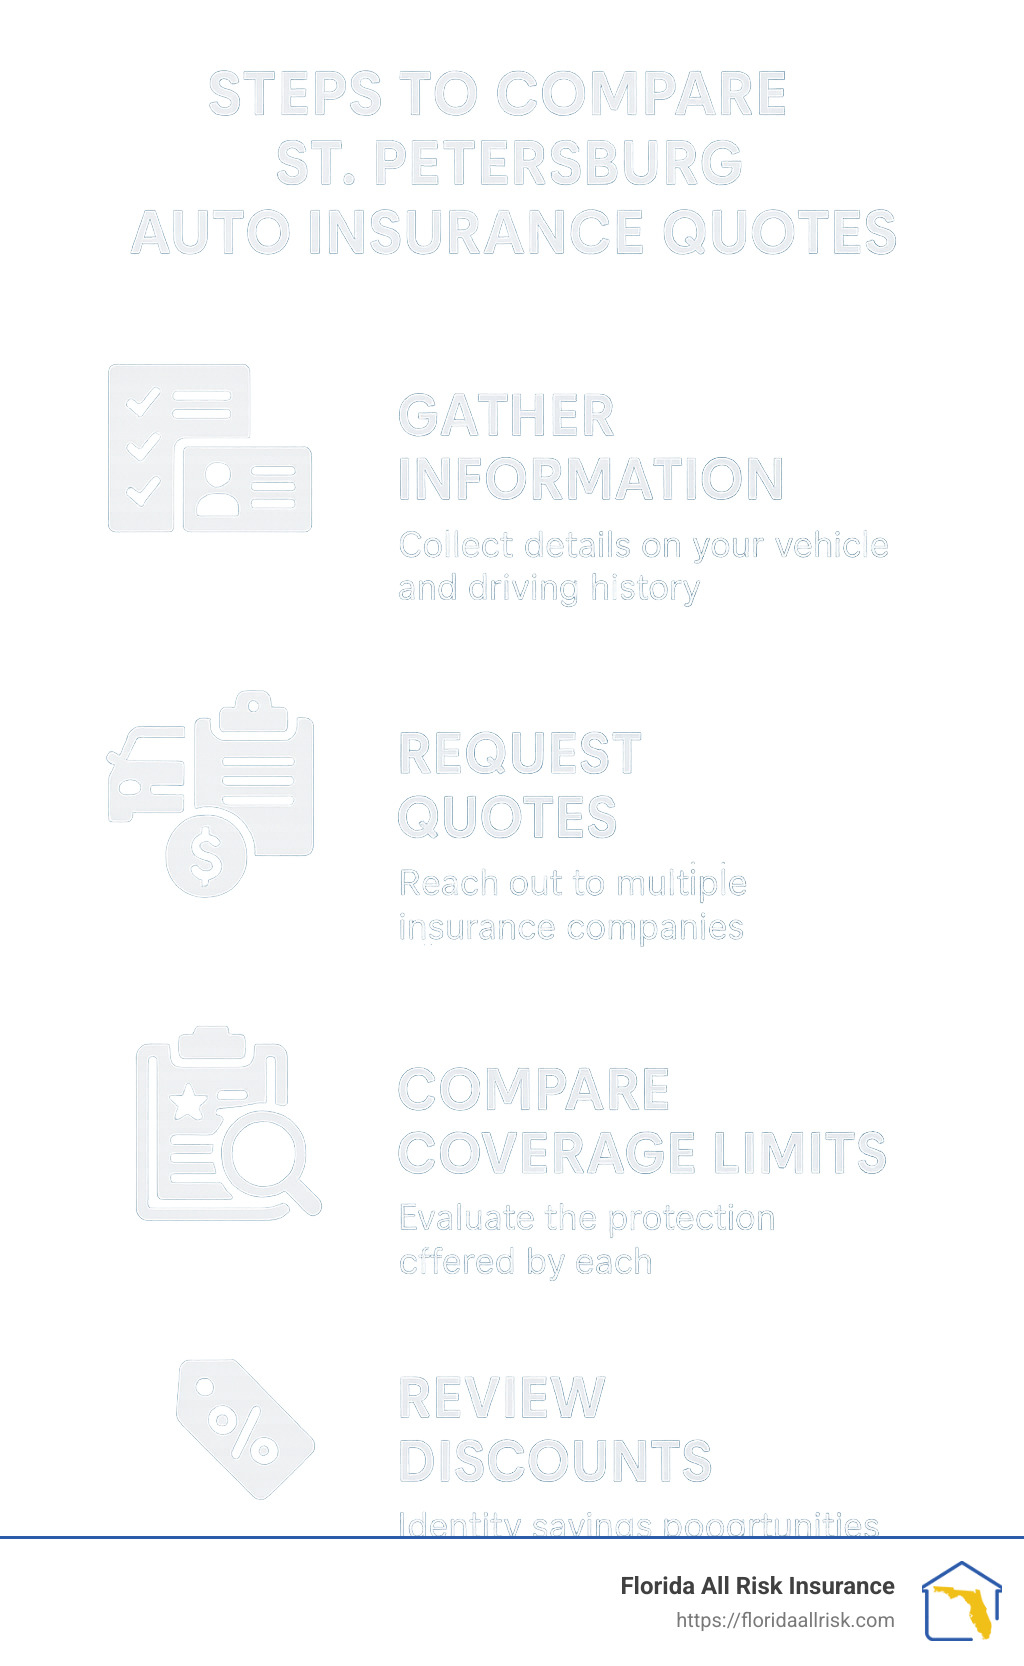
Start by gathering all your important information. You’ll need your driver’s license number, the VINs for all your vehicles, your current policy details if you have one, and a good estimate of how many miles you drive each year. Having your driving history handy helps too, though insurance companies will check this themselves.
Next, take a moment to think about your coverage needs. How much are your assets worth? That will help determine your liability limits. Is your car new or valuable enough to warrant comprehensive and collision coverage? Do you have good health insurance that works alongside PIP? And living in St. Petersburg, you’ll definitely want to consider how hurricane risk affects your comprehensive coverage needs.
When you request quotes, consistency is key. “I always tell clients to use identical coverage limits and deductibles when comparing companies,” says our agent Sarah. “Otherwise, you’re comparing apples to oranges.” Make sure you’re including all drivers and vehicles the same way across all quotes, and look at both 6-month and annual terms to find the best deal.
Working with an independent agent like us at Florida All Risk Insurance can save you tons of time. Instead of filling out the same information on a dozen different websites, we can compare rates from multiple carriers all at once. Plus, we know which companies are more forgiving of certain issues like accidents or credit problems.
Timing matters too! Shop for new rates about 3-4 weeks before your current policy expires. That’s when you’ll find the best deals. And don’t forget to re-shop after major life events like getting married, moving, or buying a new car. Even positive changes to your credit score can mean big savings.
Jennifer, one of our clients, learned this firsthand: “When I moved from Tampa to St. Petersburg last year, I assumed my rates would stay about the same. Florida All Risk Insurance showed me that different companies viewed my new ZIP code very differently. By switching carriers, I saved $430 annually for identical coverage.”
Open up Discounts to Lower Your St. Petersburg Auto Insurance Quotes
Most St. Petersburg drivers qualify for at least 2-3 discounts, which can slash your premium by 15-25%. The trick is knowing which ones to ask for!
Bundling home and auto policies is probably the biggest money-saver, often reducing premiums by 5-25%. If you have multiple vehicles, a multi-vehicle discount can save you 10-25%. Simple changes like paying in full instead of monthly (5-10% savings) or signing up for paperless billing and autopay (2-5% savings) add up quickly.
Your good behavior behind the wheel pays off too. Clean driving records can earn you 10-30% off, while taking a defensive driving course might save another 5-15%. If you have teens, make sure they know that good grades can translate to 5-25% insurance savings!
Seniors aren’t left out either—many companies offer mature driver discounts of 5-15%. And don’t forget to mention any professional organizations or alumni associations you belong to—they might be worth another 2-10% off.
Your vehicle itself might qualify for savings too. Anti-theft devices can reduce premiums by 5-25%, while safety features like airbags and anti-lock brakes save 5-15%. Driving a brand new car or a low-mileage vehicle? Those could be worth 5-20% off.
Technology is creating new ways to save too. Telematics programs that track your driving habits through a smartphone app or plug-in device can save good drivers 5-40%, depending on how safely you drive. Even just using a company’s mobile app might earn you a small 2-5% discount.
At Florida All Risk Insurance, we do a thorough discount review with every client. Many people don’t realize that a defensive driving course can lower rates for three full years, often saving more than the course costs in just the first few months.
You can find even more ways to save on our Best Car Insurance Discounts page.
Extra Coverages Worth Considering
While basic coverage keeps you legal on the road, these additional protections can save you from serious financial headaches:
Gap insurance is a lifesaver if your new car gets totaled. It covers the difference between what your car is worth (which drops the minute you drive it off the lot) and what you still owe on your loan. If you made a small down payment on a new vehicle, this coverage is practically essential.
Roadside assistance feels like a luxury until you’re stuck on the Howard Frankland Bridge in July with a flat tire. For just a few dollars a month, you get towing, battery jumps, flat tire changes, and lockout services. In St. Petersburg’s summer heat, this peace of mind is well worth it.
Rental reimbursement covers your rental car costs while your vehicle is being repaired after a covered claim. For just $2-5 monthly, you won’t be stranded without transportation when you need it most.
Living in St. Petersburg means being prepared for water. A flood endorsement offers improved protection specifically for our flood-prone areas, going beyond what standard comprehensive coverage includes. This is especially important in neighborhoods like Shore Acres or Snell Isle.
If you’ve just purchased a new car, consider new car replacement coverage. If your vehicle is totaled within the first year or two, this pays for a brand-new replacement rather than the depreciated value—a difference that could be thousands of dollars.
Thomas, a client who recently moved to Shore Acres, shared his experience: “After moving, I added flood endorsement to my policy on Florida All Risk’s recommendation. Six months later, when street flooding reached my car during a severe thunderstorm, that $3 monthly add-on saved me from a $7,000 repair bill.”
To learn more about all your coverage options, visit our Auto Insurance St Petersburg FL page or check out our offerings at FINRA’s BrokerCheck Insurance Products Offered.
Frequently Asked Questions about St. Petersburg Auto Insurance Quotes
How does a recent accident change my rates?
That fender-bender on Central Avenue can really hit your wallet. After an at-fault accident in St. Petersburg, expect your rates to jump by about 46% on average. But here’s where shopping around really pays off – some carriers typically only increase rates by about 16% after an accident, while others might slam you with a whopping 75% increase!
“When my daughter backed into a light pole at Tyrone Mall, I was terrified about our premium,” shares Maria, a long-time Florida All Risk client. “Our agent reshuffled our coverage and found a carrier that only increased our rate by 20% instead of the 60% our previous insurer quoted.”
Your accident will usually follow you for 3-5 years, though the good news is the impact typically decreases each year you drive claim-free. Even non-fault accidents might bump your premium by 5-15%, which doesn’t seem fair, but that’s how insurance math works.
If you’ve had an accident, comparing st petersburg auto insurance quotes becomes even more crucial – the difference between companies could mean hundreds of dollars in your pocket each year while you wait for that accident to age off your record.
Will improving my credit score lower premiums?
Absolutely, and the savings can be substantial! In St. Petersburg, drivers with poor credit pay about $469 monthly for full coverage – which is the same 60% increase as having a DUI on your record. That’s right – your credit score can impact your insurance as much as a serious driving offense.
Improving your credit from “poor” to “fair” could save you $100-150 each month on full coverage, while climbing from “fair” to “good” might put another $50-80 monthly back in your pocket. For many families, that’s the difference between struggling and comfortable budgeting.
Insurance companies use what they call “credit-based insurance scores” – similar but not identical to regular credit scores – because their data shows people who manage credit responsibly tend to file fewer claims. Florida law permits this practice, though some states have restricted it.
Want to improve your insurance score? Focus on paying bills on time, reducing credit card balances, limiting new credit applications, keeping long-standing accounts open, and regularly checking your credit report for errors. Many of our clients at Florida All Risk Insurance see premium reductions within 3-6 months of improving their credit.
What should I do after a hurricane damages my car?
Living in St. Petersburg means hurricane preparedness isn’t just for your home – it’s for your vehicles too. If Ian, Irma, or the next big storm damages your car:
First, document everything thoroughly. Take plenty of photos from multiple angles before moving the vehicle or making temporary repairs. These images are gold when filing your claim.
Next, file your claim promptly. Contact your insurance company as soon as it’s safe to do so – most policies require reporting within 24-72 hours. The Florida All Risk mobile app lets clients file claims directly with photos attached, which speeds up processing.
Be sure to mitigate further damage by taking reasonable steps like covering broken windows with plastic, but don’t make permanent repairs until the adjuster has inspected the vehicle.
Keep all receipts for emergency repairs, towing, or protective measures – these expenses may be reimbursable under your policy.
Understand that hurricane damage falls under comprehensive coverage, not collision. Your comprehensive deductible will apply, which is why many St. Petersburg drivers opt for lower comprehensive deductibles during hurricane season.
Finally, be prepared for potential delays after widespread events like hurricanes when adjusters are handling high claim volumes. Stay in regular contact with your insurer.
“After Hurricane Irma, we saw claims processing take 2-3 weeks longer than normal,” explains our claims specialist at Florida All Risk Insurance. “Our clients who had complete documentation and promptly responded to adjuster requests generally saw faster resolutions.”
One local tip: If your car has been submerged in saltwater flooding, don’t start the engine! Salt water causes rapid corrosion and can turn a repairable vehicle into a total loss within days. Have it towed directly to a qualified repair facility instead.
The right coverage before the storm makes all the difference after. That’s why we recommend reviewing your st petersburg auto insurance quotes annually to ensure your comprehensive coverage limits and deductibles still make sense for our coastal reality.
Conclusion
Finding affordable st petersburg auto insurance quotes doesn’t have to feel like searching for buried treasure. With a little knowledge and the right guidance, you can steer Florida’s unique insurance landscape with confidence.
At Florida All Risk Insurance, we’ve spent years helping St. Petersburg drivers just like you find the perfect balance of protection and affordability. As your neighbors, we understand the local factors that impact your rates – from hurricane risks to Florida’s no-fault requirements.
When you work with an independent agency like ours, you gain access to multiple insurance carriers through a single point of contact. This means more options, better rates, and coverage that truly fits your specific situation.
Remember what we’ve learned about St. Petersburg auto insurance:
The average full coverage policy runs about $294 monthly, but your personal rate could be significantly higher or lower. Your age, driving history, credit score, and even the neighborhood where you park at night all play important roles in determining what you’ll pay.
Strategic comparison shopping can save you hundreds – sometimes even thousands – each year. We’ve seen clients save over $400 annually just by switching to a carrier that views their driving profile more favorably.
Living in our beautiful coastal city means comprehensive coverage isn’t just nice to have – it’s practically essential. One major storm could leave you with repair bills far exceeding your savings if you’re not properly protected.
Smart discount stacking can reduce your premium by 15-25%. Many drivers qualify for multiple discounts but aren’t taking advantage of them all.
“I thought all insurance companies would charge about the same for my situation,” shared Michael, a recent client. “Florida All Risk showed me quotes that varied by over $700 a year for identical coverage. That’s money back in my pocket every month!”
Whether you’re new to the Sunshine City or have been watching the pelicans at The Pier for decades, we’re here to help you find coverage that protects what matters most without breaking the bank.
Ready to compare st petersburg auto insurance quotes and see how much you could save? Reach out to our team at Florida All Risk Insurance today. We’ll take the time to understand your unique situation and find options that make sense for your life and budget.
For more detailed information about coverage options, visit our Auto Coverage Information page.

