

Why PIP Insurance Florida is Critical for Every Driver
{: .align-center data-alt=”Florida coastal highway with palm trees and cars, symbolizing the journey of understanding insurance in the Sunshine State.” data-caption=”Florida coastal highway with palm trees and cars, symbolizing the journey of understanding insurance in the Sunshine State.” }
PIP insurance Florida is a mandatory auto insurance coverage that protects you by paying 80% of medical expenses and 60% of lost wages up to $10,000, regardless of who caused an accident. If you own a vehicle with four or more wheels in Florida, you must carry this Personal Injury Protection (PIP) and $10,000 in Property Damage Liability (PDL) to drive legally.
Quick Answer: Florida PIP Insurance Requirements
- Minimum PIP Coverage Required: $10,000 per person, per accident
- What PIP Covers: 80% of medical bills, 60% of lost wages, up to $5,000 death benefits
- Who Must Have It: All Florida vehicle owners with 4+ wheel vehicles
- Critical Rule: Seek medical treatment within 14 days of an accident or lose benefits
- Coverage Applies To: You, resident family members, and passengers
- Penalties for Non-Compliance: License suspension up to 3 years, reinstatement fees up to $500
Florida operates under a “no-fault” insurance system, meaning your own policy is the first source of payment for your injuries. This is designed to speed up medical payments, but it often surprises drivers. The state’s high insurance rates—52% above the national average—and a large number of uninsured drivers make understanding your policy crucial. Many drivers find too late that the minimum $10,000 PIP limit is often insufficient, as a serious accident can lead to costs far exceeding this amount. Knowing what PIP covers and when you can seek further damages is key to protecting your family on Florida’s roads.
At Florida All Risk Insurance, we have over 20 years of experience helping Florida families steer the state’s unique no-fault system. We’re here to break down the complexities in plain language.
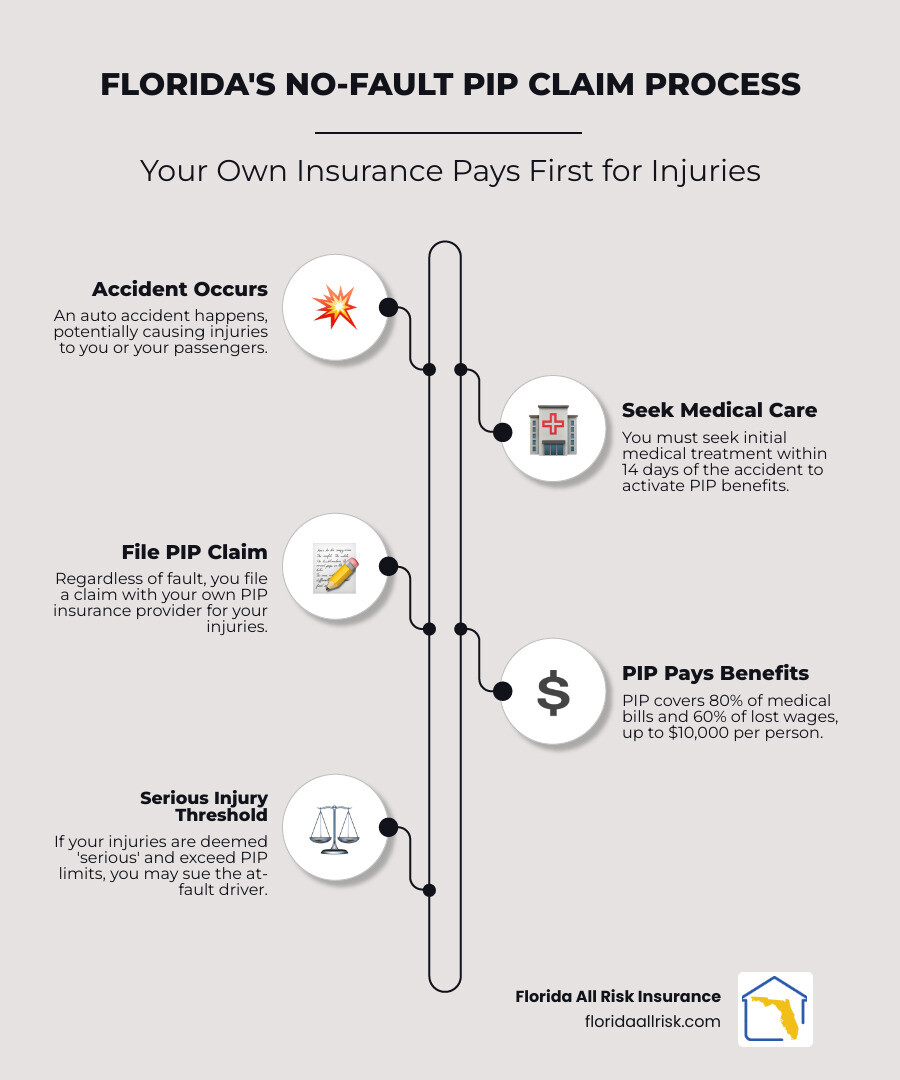
{: .align-center data-alt=”Infographic showing Florida’s no-fault PIP insurance system flow: Driver A and Driver B both involved in an accident, each filing claims with their own PIP insurance first for medical expenses and lost wages up to policy limits, with arrows showing when serious injury threshold allows lawsuits against at-fault driver.” data-caption=”Infographic showing Florida’s no-fault PIP insurance system flow: Driver A and Driver B both involved in an accident, each filing claims with their own PIP insurance first for medical expenses and lost wages up to policy limits, with arrows showing when serious injury threshold allows lawsuits against at-fault driver.” }
What is PIP and Why is it Mandatory in Florida?
Florida is one of a dozen states with a “no-fault” auto insurance system. This approach is designed to ensure injured people receive medical care and financial support quickly, without waiting for a lengthy legal process to assign blame. It also aims to reduce the number of minor injury lawsuits in the court system. For a plain-English overview of how no-fault works, see the Insurance Information Institute explainer on no-fault auto insurance.
At the heart of this system is Personal Injury Protection, or PIP insurance Florida. It acts as your primary financial safety net after a crash. When an accident occurs, PIP covers your initial medical bills and lost wages, regardless of who was at fault. Even if another driver was clearly to blame, you will file your first injury claim with your own insurance company. Because this system is integral to Florida law, PIP coverage is mandatory for anyone who owns and registers a vehicle with four or more wheels in the state. For a complete overview of legal requirements, see our guide on Basic Auto Insurance Florida.
How Florida’s ‘No-Fault’ System Works with PIP
The term “no-fault” doesn’t mean no one is ever responsible for an accident. Fault still matters, just not for your initial injury claim. After a crash, you and your passengers turn to your own PIP insurance Florida policy to cover medical costs and lost wages. Your insurer pays these benefits without determining who caused the accident, which is different from traditional fault-based states where the at-fault driver’s insurance pays.
This system provides faster access to funds for recovery. However, PIP has limits. The standard $10,000 cap can be exhausted quickly by emergency room visits, therapy, and missed work. If your expenses exceed your PIP limits or you suffer a “serious injury” as defined by Florida law, you can step outside the no-fault system. This allows you to file a claim or lawsuit against the at-fault driver for additional damages.
Is PIP Insurance Mandatory for All Drivers?
Yes, if you own a vehicle with four or more wheels registered in Florida, you must carry PIP insurance Florida. This is a strict legal requirement. The law demands continuous coverage, even if your vehicle is stored, inoperable, or not being driven, as long as it has a valid Florida registration. The Florida Department of Highway Safety and Motor Vehicles enforces this rule without exception for most residents.
Many drivers mistakenly cancel their insurance on a vehicle they aren’t using, leading to severe penalties. If you need to cancel your policy, you must surrender your license plates to the DMV before canceling. Failing to do so will trigger an automatic suspension of your driver’s license and vehicle registration. Reinstatement fees range from $150 to $500, plus the hassle of dealing with a suspended license. While some exemptions exist, such as for military members stationed out-of-state, the vast majority of Floridians must maintain continuous PIP and Property Damage Liability coverage.
Understanding Your PIP Insurance Florida Coverage
{: .align-center data-alt=”A person carefully reviewing an auto insurance policy document with a calculator nearby, symbolizing financial planning and understanding of insurance terms.” data-caption=”A person carefully reviewing an auto insurance policy document with a calculator nearby, symbolizing financial planning and understanding of insurance terms.” }
Understanding the details of your PIP insurance Florida policy is crucial for financial security after an accident. Let’s decode what your policy covers and its critical limitations.
What Specific Expenses Does Florida PIP Coverage Typically Cover?
Your PIP insurance Florida policy acts as a financial first responder, covering specific, immediate expenses. The primary benefits include:
- Medical Expense Coverage: Pays for 80% of “necessary and reasonable” medical costs up to your $10,000 policy limit. This includes a wide range of services such as hospital bills, ambulance transport, surgical procedures, diagnostic tests (X-rays, MRIs), rehabilitation, chiropractic care, and prescription medications. For more details on benefits and definitions, see Florida Statutes § 627.736 (Personal Injury Protection).
- Lost Wages: Covers 60% of your gross income lost due to accident-related injuries, up to the $10,000 policy limit. This benefit is a crucial lifeline when you are unable to work.
- Replacement Services: Pays for essential household services you cannot perform while injured, such as cleaning, cooking, or childcare.
- Death Benefits: Provides $5,000 for funeral and burial expenses. This benefit is in addition to the $10,000 limit for medical and wage loss.
The Critical 14-Day Treatment Window
This is a rule you cannot ignore: to qualify for any PIP insurance Florida benefits, you must seek initial medical treatment within 14 days of your accident. If you miss this deadline, your insurer can deny your entire claim, leaving you responsible for all costs.
Many accident injuries, like whiplash or soft tissue damage, may not present symptoms immediately. Waiting to see if you feel better is a gamble that can cost you thousands. Furthermore, the nature of your diagnosis matters. If a qualified medical professional diagnoses you with an Emergency Medical Condition (EMC), you are eligible for the full $10,000 in medical benefits. If no EMC is diagnosed, your medical benefits are capped at just $2,500. Always see a doctor within 14 days to protect your health and your right to benefits.
What is NOT Covered by Florida PIP Insurance?
Knowing what PIP insurance Florida excludes is just as important as knowing what it includes. PIP does NOT cover:
- Damage to your vehicle or any other property. This falls under Collision, Comprehensive, or Property Damage Liability coverage. Our guide on Auto Insurance Coverage Options explains these further.
- Injuries to occupants of another vehicle. Their own PIP policies are responsible for their initial injury claims.
- Medical costs beyond the 80% coverage or the $10,000 limit. You are responsible for the remaining 20% of medical bills and any costs that exceed your policy cap.
- Lost wages beyond the 60% coverage or the policy limit.
- Pain and suffering. Compensation for non-economic damages like emotional distress or chronic pain can only be pursued through a lawsuit against the at-fault driver if your injuries meet the state’s “serious injury” threshold.
Florida’s Minimum Insurance Requirements & Penalties
Florida is a mandatory insurance state, meaning carrying proper coverage is a legal obligation with serious consequences if ignored. Before you can register a vehicle with four or more wheels, you must provide proof of Personal Injury Protection (PIP) and Property Damage Liability (PDL) insurance. The Florida Department of Highway Safety and Motor Vehicles provides comprehensive information on these requirements.
Minimum Coverage Limits for PIP and PDL
Florida law is explicit about the minimum coverage every driver must carry:
- $10,000 in Personal Injury Protection (PIP): This is your no-fault coverage for your own medical bills and lost wages.
- $10,000 in Property Damage Liability (PDL): This coverage pays for damage you cause to another person’s property, such as their car, fence, or mailbox.
While these are the legal minimums, they are often insufficient. A modern vehicle can easily cost more than $10,000 to repair or replace, and serious injuries can quickly surpass the PIP limit. Relying solely on minimum coverage can leave you financially exposed. For a look at more robust protection, review our Auto Insurance Coverage Options.
Key Insurance Terms Defined
Understanding insurance vocabulary is key to making smart choices. Here are the essential terms for Florida drivers:
- Personal Injury Protection (PIP): No-fault coverage for your own medical expenses and lost wages after an accident.
- Property Damage Liability (PDL): At-fault coverage for damage you cause to someone else’s property.
- Bodily Injury Liability (BIL): At-fault coverage that pays for injuries you cause to others, including their medical bills, lost wages, and pain and suffering. While not typically required, it is mandatory for drivers with certain convictions, like a DUI. It is highly recommended for all drivers to protect their assets.
- SR-22/FR-44: These are not insurance policies but are certificates of financial responsibility filed with the state. An SR-22 proves you have the required liability coverage after a license suspension. An FR-44 is required after a DUI conviction and certifies that you carry much higher liability limits.
Penalties for Driving Without Insurance in Florida
Driving without the required PIP insurance Florida and PDL coverage carries severe penalties. If you let your insurance lapse, the state can suspend your driver’s license, vehicle registration, and license plates for up to three years. There are no hardship licenses granted for insurance-related suspensions.
To reinstate your driving privileges, you will face hefty fees: $150 for a first offense, $250 for a second, and $500 for subsequent offenses. These fees are in addition to the cost of a new insurance policy. Worse, if you cause an accident while uninsured, you are personally liable for all damages and injuries, which can lead to lawsuits, wage garnishment, and financial ruin. The risks of driving uninsured far outweigh the cost of coverage. Our Driving Without Insurance Florida Guide details these risks further.
The Cost of Car Insurance in Florida
If you feel like you’re paying too much for car insurance, you’re not imagining things. Florida policies cost about 52% more than the national average. This is due to a combination of factors, including a high rate of uninsured drivers, frequent litigation, severe weather risks like hurricanes, dense population centers, and high healthcare costs. These cost drivers directly impact the price of injury claims and, ultimately, premiums.
What is the Average Cost of PIP Insurance Florida?
While PIP insurance Florida is bundled into your total premium, it typically accounts for 15-20% of the cost. The average Florida driver pays around $131 per month for minimum coverage and nearly $300 per month for a full coverage policy. However, your individual rate will depend on several factors:
- Driving History and Age: A clean record lowers your rates, while accidents and violations increase them. Younger, less experienced drivers pay more.
- Vehicle Type: Luxury cars and sports cars cost more to insure than standard sedans due to higher repair costs and theft rates.
- Location: Urban areas like Miami and Tampa have higher rates than rural areas due to more traffic and crime.
- Credit Score: Insurers in Florida use a credit-based insurance score to predict risk. A better credit score generally leads to lower premiums.
- Coverage Choices: Higher deductibles can lower your premium, but you’ll pay more out-of-pocket for a claim. Opting for more than the minimum coverage will increase your premium but provide far greater protection. Our guide on Auto Insurance for Young Drivers offers more specific advice for families.
How to Find the Cheapest PIP Insurance Florida
Finding affordable auto coverage in Florida is possible with the right strategy. As an independent agency, Florida All Risk Insurance shops multiple carriers to find the best balance of price and protection for you.
The most effective way to save is to compare quotes. Beyond that, be sure to:
- Ask for Discounts: Most insurers offer discounts for safe driving, good grades (for students), bundling auto with home or renters insurance, and having vehicle safety features. See our Florida Car Insurance Discounts guide for a full list.
- Maintain a Good Driving Record: Avoiding accidents and tickets is the surest way to keep rates low and qualify for Safe Driver Insurance Discounts.
- Manage Your Credit: A higher credit score can lead to lower insurance premiums over time.
- Choose Your Deductibles Wisely: Selecting a higher deductible on collision and comprehensive coverage will lower your premium. Just ensure you can afford the out-of-pocket cost if you file a claim.
Special Scenarios & Additional Coverage Options
Florida’s insurance rules have unique considerations for different situations. Understanding these scenarios and your optional coverages is key to ensuring you’re properly protected.
Requirements for New & Non-Residents
Welcome to Florida! If you are moving to the state and either accept employment or enroll your children in a public school, you have 10 days to register your vehicle. This requires obtaining a PIP insurance Florida policy from a carrier licensed in the state. Your out-of-state policy will not suffice. If you are moving out of Florida, you must surrender your Florida license plates to a Department of Highway Safety and Motor Vehicles Office before canceling your insurance to avoid penalties for a coverage lapse.
Can I Sue if My Costs Exceed PIP Limits?
Yes, you can step outside the no-fault system and sue an at-fault driver, but only if your injuries meet the state’s “serious injury” threshold. Medical bills from even a moderate crash can quickly exceed PIP limits, often reaching tens of thousands of dollars. The law allows you to pursue a claim for additional damages if you suffer a:
- Permanent injury
- Significant and permanent scarring or disfigurement
- Significant and permanent loss of an important bodily function
- Death
If you meet this threshold, you can sue for economic damages (like medical bills beyond PIP) and non-economic damages (like pain and suffering). Consulting with a personal injury attorney is advisable in these situations.
Optional Coverages to Consider
Florida’s minimum requirements are just that—a minimum. For true financial security, consider these crucial optional coverages:
- Bodily Injury Liability (BIL): This is perhaps the most important coverage you can buy. It protects your assets by paying for injuries you cause to others in an at-fault accident. Without it, you could be personally sued for hundreds of thousands of dollars.
- Uninsured/Underinsured Motorist (UM/UIM): This protects you when you’re hit by a driver with no insurance or not enough insurance. Given Florida’s high rate of uninsured drivers, this coverage is essential for covering your own medical bills, lost wages, and pain and suffering. Learn more in our Uninsured Motorist Coverage Florida guide.
- Medical Payments (MedPay): An affordable supplement to PIP, MedPay helps cover out-of-pocket medical costs like deductibles and the 20% of bills that PIP doesn’t pay.
- Collision Coverage: Pays to repair or replace your own vehicle after an accident, regardless of fault.
- Comprehensive Coverage: Protects your car from non-accident events like theft, vandalism, floods, hail, and fire. In Florida, this coverage often includes free windshield replacement with no deductible.
Frequently Asked Questions about PIP Insurance in Florida
We regularly answer questions about PIP insurance Florida. Here are the most common ones to help clear up any confusion.
How does PIP coverage coordinate with my health insurance?
In Florida, your PIP insurance Florida is the primary payer for auto accident injuries. It pays first, covering 80% of your medical bills and 60% of lost wages up to your policy limit. Your health insurance acts as secondary coverage, kicking in after your PIP benefits are exhausted or for costs PIP doesn’t cover, like co-pays. It’s wise to review your health policy to understand how it coordinates with auto insurance.
What is the difference between PIP and Bodily Injury Liability (BIL) coverage?
This is a critical distinction. PIP (Personal Injury Protection) is no-fault coverage for your own injuries and lost wages, plus those of your passengers. It pays regardless of who caused the accident. Bodily Injury Liability (BIL) is at-fault coverage that protects your assets. It pays for injuries and damages you cause to others if you are legally responsible for a crash. Think of it this way: PIP protects you, while BIL protects you from claims made by others.
Can I choose my own doctor under my PIP policy?
Yes, you generally have the freedom to choose your own licensed medical provider for treatment under your PIP insurance Florida policy. However, two rules are crucial: the treatment must be medically necessary as a result of the accident, and your initial visit to any provider must occur within 14 days of the accident to remain eligible for benefits. Always inform your doctor’s office that you will be using PIP coverage, as they will need to follow specific billing procedures.
Conclusion: Securing the Right Protection on Florida’s Roads
Navigating Florida’s auto insurance landscape is manageable once you understand the basics. We’ve covered how PIP insurance Florida is the foundation of our state’s no-fault system, requiring all drivers to carry at least $10,000 in PIP and $10,000 in Property Damage Liability (PDL). This system ensures quick access to medical benefits but has significant limitations.
Remember the critical 14-day window to seek medical treatment and that minimum coverage rarely provides adequate protection in a serious accident. This is why considering optional coverages like Bodily Injury Liability (BIL) and Uninsured Motorist (UM/UIM) is essential for safeguarding your financial future, especially in a state with high insurance costs and many uninsured drivers.
Finding the right policy at a fair price doesn’t have to be a challenge. At Florida All Risk Insurance, we are an independent agency that works for you, not a single insurance company. We leverage our expertise and access to a wide range of carriers to build a policy that fits your needs and budget.
Ready to ensure you have the right coverage for the right price? Get a free, no-obligation auto insurance quote online now! Our team will compare options from multiple carriers to find your best fit.
For a comprehensive review of all your insurance needs—from auto to home, flood, and commercial coverage—explore our full range of products. View Our Insurance Products to see how we can help protect everything that matters to you.
Contact Us
Florida All Risk Insurance
3401 34th St N, Saint Petersburg, FL 33713
Phone: (727) 521-1800
Email: [email protected]

