

Online auto insurance quotes Florida: 3 Ways to Save
Why Florida Drivers Are Turning to Online Auto Insurance Quotes
{:alt=”Coastal highway in Florida with palm trees and cars. Metadata: Location – Florida Coast, Date – 2024-05-15, Photographer – AI Generated, Keywords – Florida, auto insurance, quotes, highway, coastal, palm trees” }
Online auto insurance quotes Florida have become an essential tool for drivers navigating the state’s high insurance costs. In 2024, Florida’s average car insurance premium soared to $3,682, a full 68% higher than the national average. This financial pressure has led savvy drivers to accept digital platforms that allow them to easily compare rates, understand coverage, and find better deals from home.
Quick Answer for Florida Drivers Seeking Online Auto Insurance Quotes:
- Visit multiple insurance websites or use comparison platforms to get quotes.
- Gather required information: Have your driver’s license, vehicle VIN, and current policy details ready.
- Compare identical coverage limits across different insurers for an accurate price comparison.
- Consider both price and company ratings before making a decision.
- Complete your application online for instant coverage, often available the same day.
Florida’s unique insurance landscape, with its no-fault system and high rate of uninsured drivers, creates challenges. However, the digital shift in insurance shopping empowers drivers to find the best value by comparing dozens of carriers in minutes.
About the Author: I’m Jason Miller, a second-generation insurance professional with over 20 years of experience helping Florida drivers. At Florida All Risk Insurance, my expertise in online auto insurance quotes Florida has helped thousands of clients find comprehensive coverage at competitive rates in this complex market.
Related content about Online auto insurance quotes Florida:
- Florida car insurance discounts
- Non-owner car insurance Florida
- Car insurance broker St Petersburg FL
Understanding Florida’s Unique Car Insurance Landscape
Before you start shopping for online auto insurance quotes Florida, it’s crucial to understand what makes the Sunshine State’s insurance market one of the most complex and expensive in the nation. Florida’s unique combination of laws, demographics, and environmental risks directly influences the prices you’ll see.
Florida’s Mandatory Car Insurance Requirements
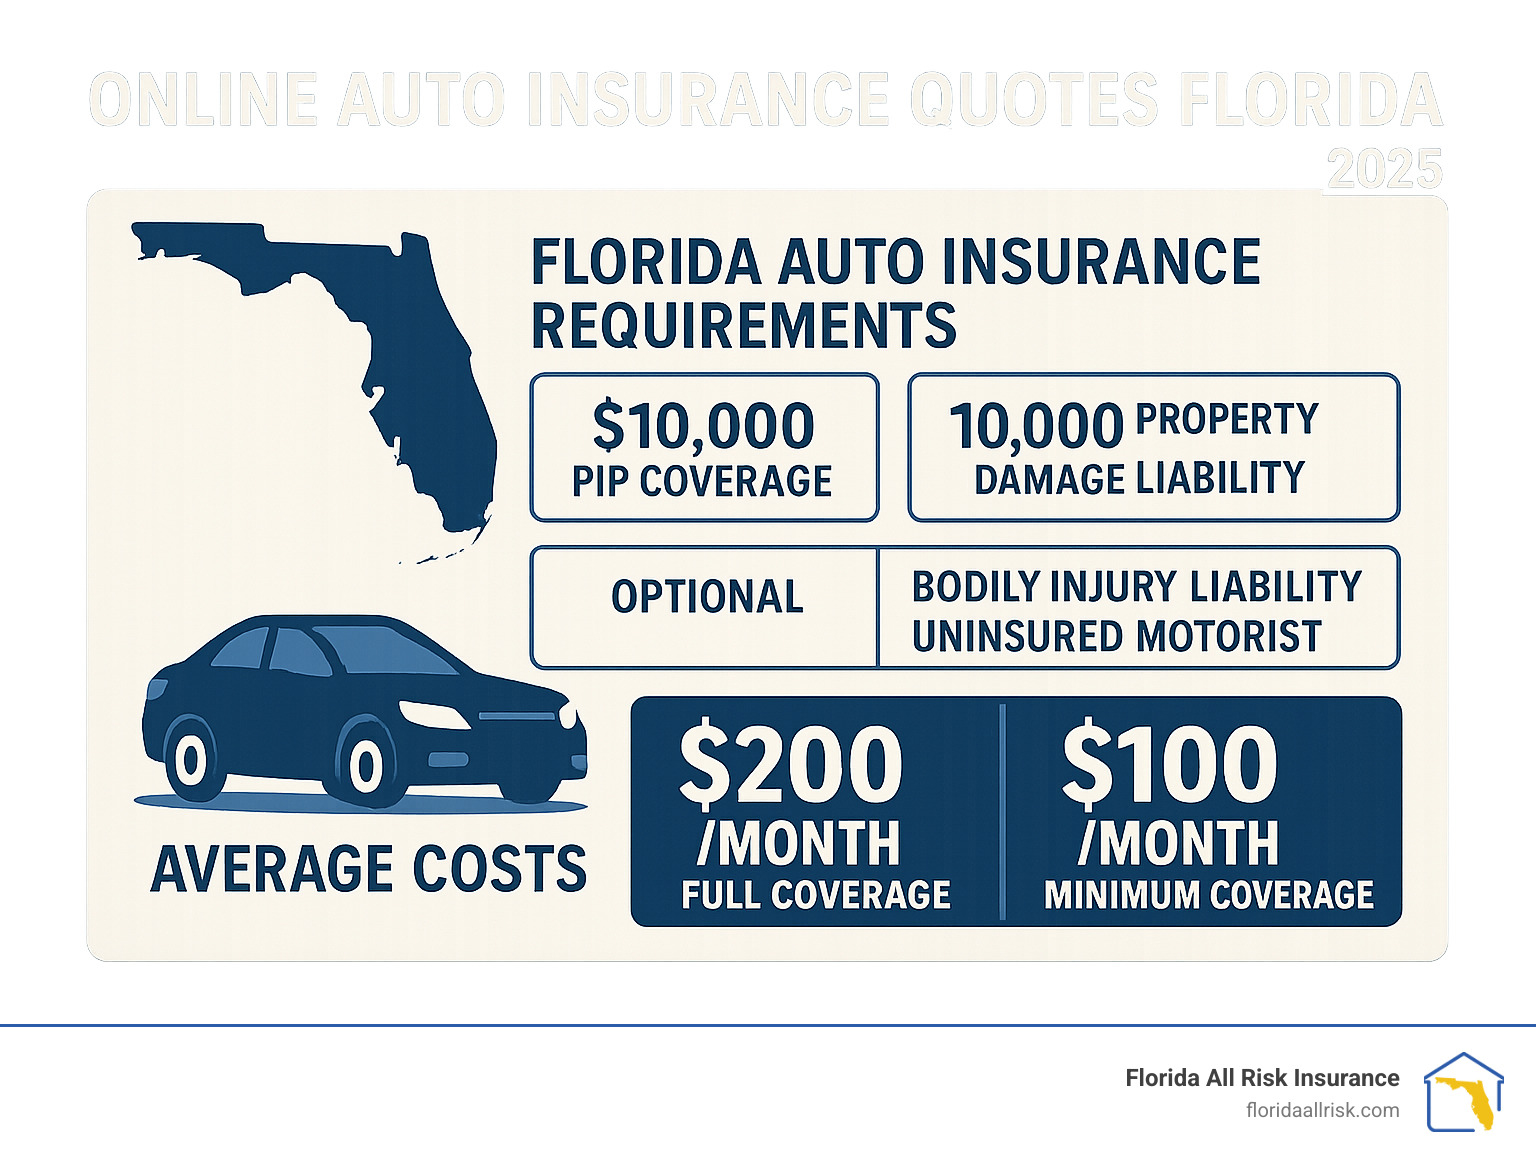
Florida operates under a “No-Fault” insurance system, which means your own policy covers your initial medical expenses after an accident, regardless of who is to blame. This system is designed to expedite medical payments without waiting for a legal determination of fault. To drive legally, you must have:
-
Personal Injury Protection (PIP): This is the core of the no-fault system. It covers 80% of your “reasonable and necessary” medical expenses and 60% of lost wages, up to a combined limit of $10,000, for you and your passengers after an accident. It also protects you as a pedestrian or cyclist if you’re hit by a car. To receive the full $10,000 benefit for non-emergency care, you must seek treatment within 14 days of the accident.
-
Property Damage Liability (PDL): This covers damage you cause to other people’s property, such as their car, a fence, or a building. Florida requires a minimum of $10,000 in PDL coverage.
Notably, Bodily Injury Liability (BIL) is not required for most drivers. This is a critical point of distinction from most other states. However, skipping this coverage is extremely risky, as you could be held personally liable for injuries you cause to others in a serious accident. Most financial and insurance experts strongly recommend carrying it.
For the most current requirements, you can always check with the Florida Department of Highway Safety and Motor Vehicles{:target=”_blank”}.
Why Are Florida Car Insurance Rates So High?
Florida’s average annual premium of $3,682 is nearly 70% above the national average for several concrete reasons:
Image: Busy Miami intersection, traffic, and palm trees. Photo by Denys Nevozhai on Unsplash.
- The No-Fault System and Fraud: While intended to be efficient, the PIP system has been exploited, leading to widespread fraud. So-called “PIP mills” and fraudulent medical clinics contribute to inflated medical claims and unnecessary treatments, driving up costs for all policyholders.
- Insurance Fraud: Beyond PIP fraud, Florida also sees high rates of staged accidents and false claims, which insurers must account for in their pricing.
- A Highly Litigious Environment: Florida has a reputation for being a litigious state. The use of “letters of protection” (agreements between a claimant’s attorney and a medical provider) and attorney fee multipliers can lead to inflated settlements and more lawsuits, which insurers pass on through higher premiums.
- Uninsured Drivers: With nearly 20% of drivers uninsured (one of the highest rates in the U.S.), insured drivers bear a heavier burden. If an uninsured driver hits you, your own policy (specifically Uninsured Motorist coverage) must cover your expenses.
- High Population Density: More cars in urban centers like Miami, Tampa, Orlando, and Jacksonville lead to more traffic congestion, accidents, and claims.
- Tourism: Millions of visitors and rental cars on the road at any given time increase accident frequency, especially with drivers unfamiliar with local roads.
- Severe Weather: Florida’s geography makes it uniquely vulnerable. Hurricanes like Ian and Michael have caused billions in vehicle damage from flooding, wind, and debris. This leads to a high volume of comprehensive claims, forcing insurers to raise rates statewide to cover the catastrophic losses.
How to Get Online Auto Insurance Quotes in Florida: A Step-by-Step Guide
The digital age has revolutionized insurance shopping. You can now gather and compare multiple online auto insurance quotes Florida from your home, but getting accurate quotes requires some preparation and understanding the different avenues available.
Information You’ll Need to Get a Quote
To ensure your quotes are accurate and the process is smooth, have the following information ready:
- Personal Details: Full name, address (where the vehicle is garaged), date of birth, and driver’s license number for all drivers on the policy.
- Vehicle Information: The make, model, year, and Vehicle Identification Number (VIN) for each car you want to insure. The VIN provides the most accurate details about your vehicle’s specific features.
- Driving History: Be prepared to share details about any accidents, claims, or traffic violations (tickets, DUIs) for all drivers within the last 3-5 years. Honesty is crucial, as insurers will verify this information.
- Current Policy Details: If you’re currently insured, your policy declaration page is invaluable. It lists your current coverage limits, deductibles, and endorsements, making it easy to request quotes for the same level of protection for an apples-to-apples comparison.
Where to Find Your Online Auto Insurance Quotes in Florida
Once you have your information, you have several paths to find quotes, each with its own pros and cons:
-
Independent Insurance Agencies: An independent agency like Florida All Risk Insurance works with multiple carriers, not just one. This allows us to shop the market on your behalf, comparing policies and prices from numerous national and regional insurers to find the best fit for your specific needs. This approach combines the convenience of comparison with personalized, expert advice from a licensed professional who understands the Florida market’s complexities.
-
Directly from Individual Insurance Companies (Captive Agents/Websites): You can visit the websites of major national carriers like State Farm, Geico, Progressive, or Allstate to get a quote directly. This approach gives you direct interaction with the insurer and can be straightforward if you already have a preferred company. However, it can be very time-consuming, as you must enter your information on each individual site to compare options effectively. You are also limited to the products offered by that single company.
-
Comparison Websites: Platforms like The Zebra or NerdWallet allow you to enter your information once to receive quotes from several insurers. They are excellent for getting a quick market overview and a baseline understanding of prices. However, be aware that some of these sites are primarily lead-generation tools that may sell your information to multiple agents and companies. The quotes may not be final, and they often lack the personalized guidance of a dedicated agent who can help you understand the nuances of each policy.
| Quote Method | Pros | Cons |
|---|---|---|
| Independent Agent | Access to multiple carriers, expert advice, personalized service. | May not represent every single carrier (e.g., those who only sell direct). |
| Direct from Insurer | Direct relationship with the company, may offer unique programs. | Time-consuming to compare, limited to one company’s options and prices. |
| Comparison Website | Fast way to see multiple initial estimates, good for research. | Quotes may not be final, can lead to many sales calls, lacks personal advice. |
For a truly personalized quote that considers your unique situation and leverages our access to multiple carriers, we’re here to make the process smooth and transparent.
Decoding Your Premium: What Determines Your Florida Car Insurance Rate?
Your car insurance premium is a carefully calculated figure based on a provider’s assessment of your risk. When you request online auto insurance quotes Florida, insurers analyze dozens of data points to predict your likelihood of filing a claim. Understanding these factors empowers you to make choices that can lower your costs.

Image: Car dashboard, speedometer, and odometer. Photo by Samuele Errico Piccarini on Unsplash.
Your Driving Profile and History
This is the most influential category in determining your rate.
- Driving Record: A clean record free of accidents (especially at-fault), speeding tickets, DUIs, and other violations is the single best way to secure lower premiums.
- Years of Experience: More years of licensed driving experience generally lead to lower rates. Teen drivers face the highest premiums due to statistical risk.
- Age, Gender, and Marital Status: Rates are based on broad actuarial data. Statistically, drivers under 25 and single drivers have higher accident rates, resulting in higher premiums. Rates often decrease for married drivers and those between the ages of 50 and 65.
Your Vehicle’s Details
The car you drive directly impacts potential claim costs.
- Make and Model: High-performance sports cars, heavy-duty trucks, and luxury vehicles cost more to insure due to higher repair costs, greater theft risk, and higher potential for damage in an accident.
- Vehicle Age: Newer cars can be more expensive to insure due to higher replacement value, but their advanced safety features may earn discounts that offset some of that cost.
- Safety and Anti-Theft Devices: Features like airbags, anti-lock brakes (ABS), electronic stability control (ESC), and alarm systems can reduce your premium by lowering the risk of injury or theft.
- Electric Vehicles (EVs): Insuring an EV can sometimes be more expensive due to the high cost of replacing or repairing specialized batteries and components after an accident.
For more guidance on vehicle safety ratings, you might find helpful information at U.S. News: Cheap Car Insurance in Florida{:target=”_blank”}.
Your Location and Lifestyle
Where you live and how you use your car are key factors.
- ZIP Code: Insurers analyze claim frequency by location. Urban areas like Miami and Fort Lauderdale with more traffic, crime, and accidents have significantly higher rates than rural parts of the Panhandle. Coastal regions may also see higher rates due to hurricane risk.
- Annual Mileage: The more you drive, the higher your statistical risk of an accident. Low-mileage drivers often qualify for discounts.
- Vehicle Use: Using your car for a daily commute in heavy traffic is riskier—and more expensive—than using it for occasional pleasure driving.
- Credit-Based Insurance Score: In Florida, insurers are permitted to use a credit-based insurance score as a rating factor. This is not the same as your FICO score but is derived from your credit history. Insurers’ data shows a strong correlation between responsible credit management and responsible driving. A strong credit history can lead to significantly lower premiums.
Beyond the Basics: Essential and Optional Coverages to Consider
Meeting Florida’s minimum PIP and PDL requirements is only a starting point. This basic coverage offers dangerously limited financial protection. For true peace of mind when getting online auto insurance quotes Florida, you should consider additional coverages that shield you from significant, potentially life-altering financial loss.
-
Bodily Injury Liability (BIL): Though not required for most, this is arguably the most critical optional coverage. If you’re at fault in an accident that injures others, BIL covers their medical bills, lost wages, and pain and suffering. Without it, your personal assets—your home, savings, and future earnings—are at risk in a lawsuit.
- A Real-World Scenario: Imagine you cause an accident that results in $100,000 in medical bills for the other driver. Without BIL, you are personally responsible for that entire amount. A court could order the seizure of your assets or the garnishment of your wages for years to come. Carrying BIL transfers that risk to your insurance company.
-
Uninsured/Underinsured Motorist (UM): With nearly one in five Florida drivers uninsured, UM coverage is essential. It protects you and your passengers if you’re hit by a driver with no insurance or not enough insurance to cover your medical bills and other damages. In Florida, you will be offered two types:
- Stacked UM: This allows you to combine the UM coverage limits for multiple vehicles on your policy. If you have two cars with $100,000 in UM coverage each, you can “stack” them to have $200,000 in available coverage for a single accident. This is highly recommended for families with multiple vehicles.
- Non-Stacked UM: This limits your coverage to the amount listed for the specific vehicle involved in the accident. It is less expensive but offers less protection.
-
Collision Coverage: This pays for damage to your own car from an accident with another vehicle or object (like a pole or fence), regardless of fault. If you lease or finance your car, your lender will require it.
-
Comprehensive Coverage: This protects your car from non-collision events common in Florida, such as theft, vandalism, fire, falling objects, and weather damage from hurricanes, floods, and hail. Like collision, it is required for leased or financed vehicles.
-
Medical Payments (MedPay): This works with PIP to cover out-of-pocket medical costs. While PIP covers 80% of medical bills, MedPay can help pay for the remaining 20% and your PIP deductible, reducing your immediate financial burden after an accident.
-
Gap Insurance: If your new car is totaled, your collision/comprehensive coverage will pay out its Actual Cash Value (ACV). Due to depreciation, this may be less than what you still owe on your loan or lease. Gap insurance covers this “gap” so you aren’t left making payments on a car you no longer have.
-
Rental Reimbursement & Roadside Assistance: These convenient add-ons help pay for a rental car while yours is being repaired after a covered claim and provide help for flat tires, dead batteries, or towing. They are low-cost additions that provide significant value when needed.
For a full list of coverage options and to understand what might be right for your specific needs, see Auto Insurance Coverage Options at Florida All Risk Insurance{:target=”_blank”}.
Proven Strategies for Slashing Your Florida Auto Insurance Costs
While Florida’s rates are high, you can actively lower your premium. It’s not just about finding the cheapest online auto insurance quotes Florida, but about making smart choices and leveraging every available saving opportunity to get the best value for your money.
Image: Piggy bank and car key. Photo by Rawpixel on Unsplash.
Open uping Discounts: From Safe Driver to Bundling
Discounts are your secret weapon against high premiums. Always ask your agent to perform a full discount review, as you may qualify for savings you aren’t aware of.
- Multi-Policy Bundling: Combining your auto insurance with a home, condo, or renters policy from the same provider often yields the largest discounts, sometimes 15-25%.
- Multi-Car: Insuring more than one vehicle on the same policy provides significant savings.
- Good Student: Rewards high school or college students for maintaining good grades (typically a B average or 3.0 GPA).
- Safe Driver: A clean driving record free of accidents and violations for 3-5 years is one of the best ways to earn a significant discount.
- Defensive Driving Course: Completing an approved course can sometimes lower your rate, especially for mature drivers.
- Professional & Affinity Groups: Some insurers offer discounts for belonging to certain alumni associations, professional organizations, or for being in specific occupations like teachers, first responders, or military personnel.
- Vehicle Safety Features: Airbags, anti-lock brakes, daytime running lights, and anti-theft systems can all lead to small but cumulative discounts.
For more details on how these discounts can add up, check out our page on Florida Car Insurance Discounts{:target=”_blank”}.
Smart Policy Management and Adjustments
- Increase Your Deductible: Your deductible is the amount you pay out-of-pocket on a comprehensive or collision claim. Raising it from $500 to $1,000 can lower your premium by 15% or more. Ensure you can comfortably afford this amount in an emergency.
- Pay Your Premium in Full: Paying annually or semi-annually instead of monthly can save you money by avoiding installment fees.
- Review Your Policy Annually: Life changes like moving, getting married, changing jobs, or buying a new car can affect your needs and rates. An annual review with your agent ensures you’re not overpaying or underinsured.
- Improve Your Credit Score: Since Florida allows credit-based insurance scores, improving your credit over time can lead to lower premiums at renewal.
- Consider Telematics (Usage-Based Insurance): Programs like Progressive’s Snapshot, Geico’s DriveEasy, or State Farm’s Drive Safe & Save track your driving habits (braking, acceleration, time of day, mileage) via a smartphone app or a small device. Safe drivers can earn substantial discounts, sometimes up to 30%.
The Power of Comparison
- Compare Apples-to-Apples: When reviewing quotes, ensure you are comparing identical coverage limits, deductibles, and endorsements. A cheaper quote may simply be for less coverage.
- Look Beyond Price: A cheap policy isn’t a good deal if the company has poor customer service, a difficult claims process, or financial instability. Check financial strength ratings from A.M. Best and read customer reviews and claim satisfaction surveys.
Frequently Asked Questions about Online Auto Insurance Quotes Florida
Navigating car insurance can be confusing. Here are concise answers to the most common questions we receive about online auto insurance quotes Florida.
How much does car insurance cost per month in Florida?
There’s no single answer, as rates are highly personalized. However, on average, Floridians can expect to pay around $200-$300 per month for full coverage and closer to $100-$150 per month for minimum coverage. Your actual cost will depend heavily on your driving record, location (ZIP code), vehicle, age, credit history, and the coverage limits you select. The only way to know your exact cost is to get a personalized quote.
Is Bodily Injury Liability (BIL) required in Florida?
No, Bodily Injury Liability (BIL) is not legally required for most drivers in Florida. The state’s no-fault law only mandates PIP and PDL coverage. However, we and most financial experts strongly recommend purchasing BIL. Without it, you are personally responsible for the medical bills, lost wages, and pain and suffering of anyone you injure in an at-fault accident. This could put your personal assets, like your home and savings, at significant risk in a lawsuit.
What happens if my Florida car insurance lapses?
Letting your insurance lapse in Florida has serious consequences. The FLHSMV will be notified electronically by your insurer. You will receive a notice requiring you to provide proof of new insurance. If you fail to do so, your driver’s license, license plate, and registration will be suspended for up to three years or until you get new insurance. To reinstate them, you will have to pay a fee ranging from $150 to $500.
Can I get insurance with a bad driving record or DUI in Florida?
Yes, but it will be more difficult and expensive. After a major violation like a DUI, you will likely be required to file an FR-44 form, which certifies you have much higher liability coverage limits ($100,000/$300,000/$50,000) than the standard. Not all companies will insure high-risk drivers, so you may need to work with an independent agent who specializes in finding coverage from non-standard carriers. Expect your premiums to be significantly higher for 3-5 years.
What’s the difference between stacked and non-stacked Uninsured Motorist coverage?
This is a critical choice in Florida. Non-stacked UM coverage means the limit you choose applies per accident, per vehicle. Stacked UM coverage allows you to combine or “stack” the UM limits for all vehicles on your policy. For example, if you have two cars with $50,000 of stacked UM coverage, you would have a total of $100,000 in coverage available if you were injured in an accident with an uninsured driver. Stacked coverage offers far more protection and is highly recommended, especially given Florida’s high rate of uninsured drivers.
How quickly can I get coverage after receiving an online quote?
Very quickly. In most cases, you can get coverage almost instantly. The modern process for getting online auto insurance quotes Florida is designed for speed and convenience. Once you select a quote, provide payment information, and sign documents electronically, the insurer can issue your policy immediately. You will typically receive digital proof of insurance (ID cards) via email or a mobile app within minutes, allowing you to be legally insured and ready to drive the same day.
Conclusion: Take Control of Your Car Insurance Costs
Navigating Florida’s complex auto insurance market doesn’t have to be an overwhelming task. While the state’s high rates and unique no-fault system present challenges, you are now equipped with the knowledge to take control. By understanding the key factors that influence your premium and leveraging the power of online auto insurance quotes Florida, you can find a policy that offers both the protection you need and a price you can afford.
Car insurance is more than a legal requirement—it’s a critical financial safeguard for you, your family, and your assets. The cheapest policy isn’t always the best, especially if it leaves you underinsured when you need it most.
Ready to find the right coverage? The key is to be a proactive, informed shopper. Use the strategies in this guide to compare your options effectively. For expert guidance and a streamlined comparison of multiple top-rated carriers, the team at Florida All Risk Insurance is here to help. We can steer the market for you, ensuring you secure the best possible coverage at a competitive rate.
Contact Us
Finding the right car insurance in Florida is easier with a trusted partner. The experienced local agents at Florida All Risk Insurance are here to simplify the process and provide the personalized guidance you deserve.
As an independent agency, we shop multiple top-rated carriers on your behalf to find a policy that fits your life and budget. We’ll help you understand your options and answer all your questions.
Ready to get started with a personalized auto insurance quote? Contact us today.
Florida All Risk Insurance
Address: 7901 4th St N, Suite 300, Saint Petersburg, FL 33702
Phone: (727) 232-9550
Email: [email protected]
Website: https://floridaallrisk.com/

