

CNA General Liability Insurance: Top A+ Choice
Why CNA General Liability Insurance Matters for Your Business
CNA general liability insurance protects businesses from financial losses when third parties claim bodily injury, property damage, or personal injury caused by your operations. Whether you run a small consulting firm or a mid-sized manufacturing company, this coverage shields you from lawsuits that could otherwise threaten your business’s survival. In the litigious environment of modern commerce, having a robust defense is not just a luxury; it is a fundamental requirement for operational continuity. For Florida business owners, navigating the complexities of liability requires a partner with deep pockets and even deeper expertise.
What CNA General Liability Insurance Covers
Core Protections:
- Bodily injury – Medical costs when someone gets hurt on your property or due to your business operations. This includes immediate first aid, ambulance services, and long-term rehabilitation costs if your business is found liable. It also covers the legal fees required to defend against these claims, which can often exceed the medical costs themselves.
- Property damage – Repairs or replacement when you damage someone else’s property. This extends beyond physical structures to include loss of use of that property, which can often be a significant financial burden. For example, if a contractor accidentally breaks a water main, they are responsible for the repair and the lost revenue of the businesses affected by the water shutoff.
- Personal and advertising injury – Legal defense for slander, libel, or copyright infringement claims. This is increasingly important in the digital age where a single social media post or a marketing campaign that looks too similar to a competitor’s can lead to a multi-million dollar lawsuit.
- Medical payments – Immediate medical expenses regardless of fault (typically up to $5,000). This “no-fault” coverage is designed to settle minor injuries quickly and prevent them from escalating into full-blown lawsuits, acting as a goodwill gesture to injured parties.
Who Needs It:
- Construction contractors and builders who face daily risks on job sites and potential “completed operations” claims years later.
- Manufacturing companies dealing with complex supply chains and product liability risks that could span multiple continents.
- Healthcare providers and aging services requiring specialized professional and general liability integration to protect their staff and patients.
- Real estate firms and property managers responsible for large physical assets and the safety of hundreds of tenants.
- Financial institutions managing professional and civil liabilities in an increasingly regulated environment.
- Professional service providers like architects, engineers, and consultants whose advice can lead to third-party losses.
- Small businesses and mid-market organizations looking for scalable protection that grows with their revenue.
Key CNA Advantages:
- A+ Superior financial strength rating from AM Best, ensuring they can pay claims even in catastrophic economic cycles.
- 40+ years of industry-specific experience in high-stakes sectors like healthcare and technology.
- Claims professionals with average 20 years expertise in handling complex litigation and identifying fraudulent claims.
- Specialized packages like CNA Paramount® and CNA Connect® tailored to business size and specific industry risks.
- E&O coverage up to $10 million for tech and manufacturing sectors, bridging the gap between physical and financial damage.
I’m Jason Miller, and with over 20 years helping Florida businesses secure proper coverage, I’ve seen how CNA general liability insurance delivers the comprehensive protection and claims support that keeps companies operating confidently. In this guide, I’ll walk you through everything you need to know about CNA’s commercial general liability offerings and how they can protect your business.
Cna general liability insurance terms explained:
- general liability insurance
- commercial general liability insurance for small business
- high risk general liability insurance
Understanding the Core Protections of Commercial General Liability
At its heart, CNA general liability insurance—often referred to as a commercial general liability insurance policy—is designed to protect your business from the “slip and fall” incidents that keep business owners awake at night. But it goes much further than just wet floors. The policy serves as the first line of defense against a wide array of civil legal actions that can arise from your daily business activities, whether they occur on your premises or at a client’s location.
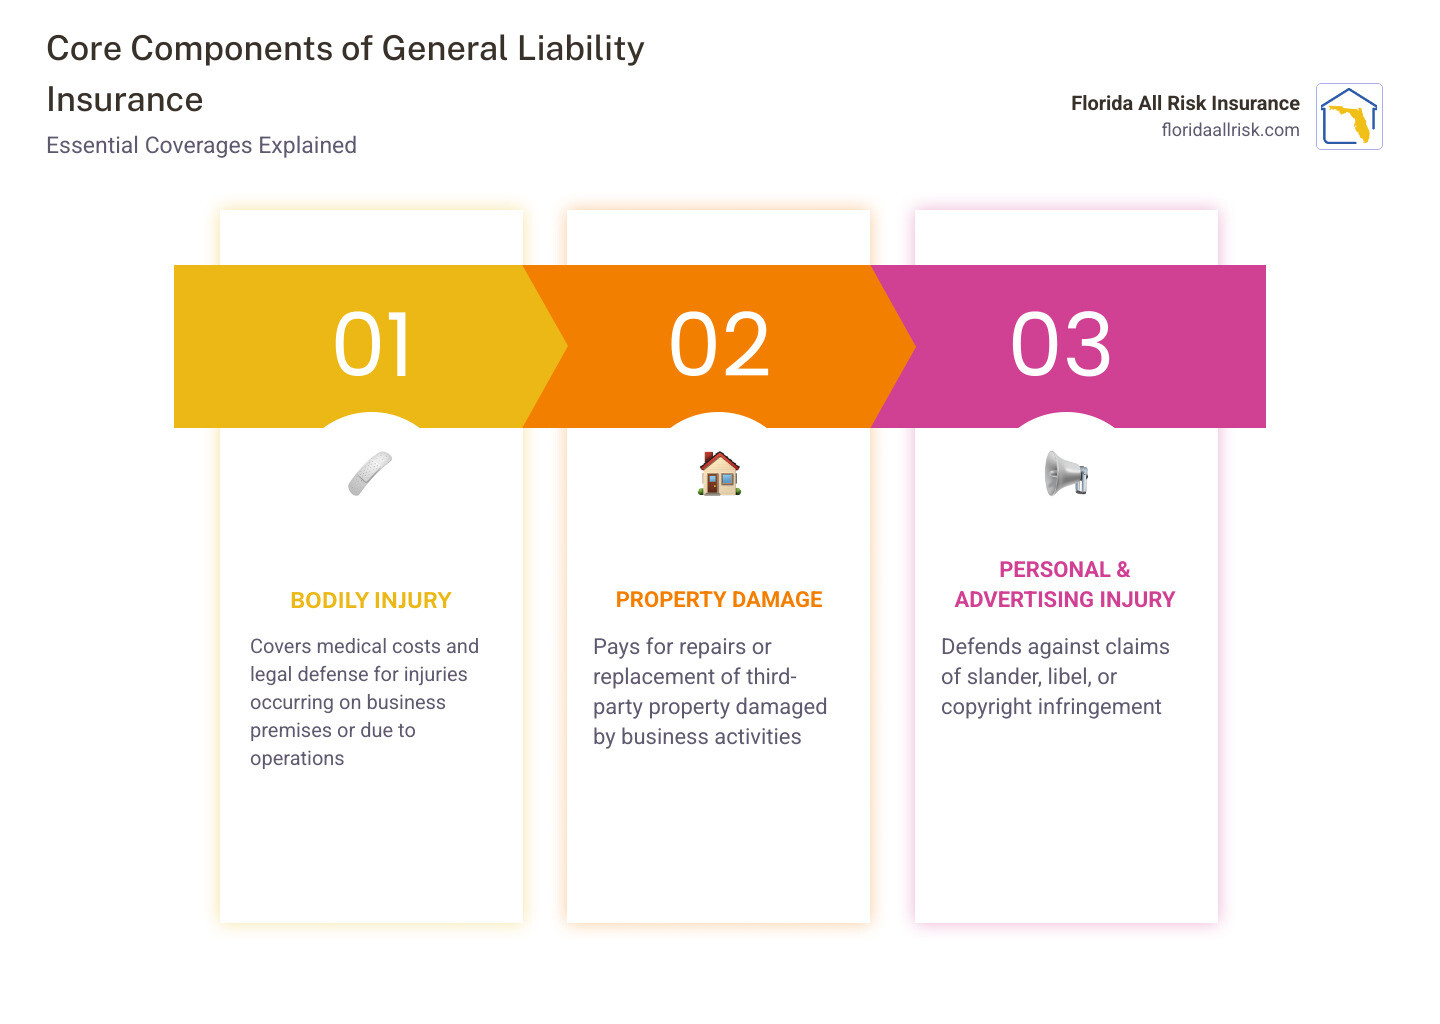
When we talk about what does general liability insurance cover, we are looking at three primary buckets of risk: bodily injury, property damage, and personal/advertising injury. CNA’s policies are built on the foundation of the ISO CGL policy, which is the industry standard developed by Verisk/ISO. However, CNA adds layers of expertise and specific endorsements that make them stand out in the crowded Florida market. The ISO form is the “DNA” of the policy, but CNA’s enhancements provide the specialized “armor” needed for modern risks.
Bodily Injury and Property Damage (Coverage A)
These are the most common claims. If a client visits your office in Saint Petersburg and trips over an unsecured rug, that is a bodily injury claim. If your employee accidentally knocks over an expensive piece of equipment while visiting a client’s site, that is property damage. CNA’s coverage doesn’t just pay the bill for the damage; it pays for your legal defense, which can often be more expensive than the claim itself.
In the legal world, the “duty to defend” is often broader than the “duty to indemnify.” This means CNA will provide a legal defense even if the lawsuit is groundless, false, or fraudulent, as long as the allegations fall within the scope of the policy. This protection is vital because even a successful defense against a frivolous lawsuit can cost tens of thousands of dollars in attorney fees and court costs. Furthermore, CNA’s policy includes coverage for “contractual liability,” which protects you when you have assumed the liability of another party under an “insured contract,” such as a lease or a construction agreement.
Personal and Advertising Injury (Coverage B)
This protects you from non-physical damages. In the age of social media and digital marketing, it is easier than ever to accidentally infringe on a copyright or face a lawsuit for libel or slander. If a competitor claims your latest advertisement disparages their brand, your CNA general liability insurance is there to step in. This coverage also includes protection against wrongful eviction, invasion of privacy, and false arrest, which are critical for real estate professionals and retail business owners.
| Scenario | Coverage Type | What is Paid? |
|---|---|---|
| Customer slips on a wet floor in your lobby | Bodily Injury | Medical bills, ambulance fees, legal defense |
| Your technician drops a tool through a client’s skylight | Property Damage | Repair costs for the roof, replacement of damaged furniture |
| A social media post accidentally uses a copyrighted image | Advertising Injury | Settlement costs, legal fees, court awards |
| A neighbor’s building is damaged by a fire starting at your shop | Property Damage | Reconstruction costs for the third party |
By securing general liability insurance, you aren’t just buying a piece of paper; you are buying the peace of mind that a single accident won’t wipe out your life’s work. The financial stability of CNA ensures that when a claim is filed, the resources are available to handle it professionally and efficiently. This is especially important for “occurrence-based” policies, where a claim might be filed years after the policy period ends, requiring a carrier that will still be in business decades from now.
Specialized Industry Solutions and the CNA Paramount® Advantage
One of the reasons we often recommend CNA to our clients at Florida All Risk Insurance is their ability to scale. They don’t believe in a “one size fits all” approach. Instead, they offer modular policies that can be customized to the specific needs of your industry. This modularity is essential because the risks faced by a florist are vastly different from those faced by a heavy machinery manufacturer. CNA’s industry-specific underwriters understand these nuances, allowing them to price risk more accurately and provide more relevant coverage extensions.
For smaller businesses, CNA offers CNA Connect®. This is a streamlined commercial general liability insurance for small business package that bundles essential coverages into one easy-to-manage policy. It’s perfect for the boutique shops and local service providers that make Saint Petersburg such a vibrant place to live. CNA Connect often includes built-in protections for business personal property, business income, and even some cyber liability elements, making it a comprehensive “Business Owners Policy” (BOP). It simplifies the insurance process for entrepreneurs who need to focus on growth rather than policy management.
For mid-market and larger organizations, there is CNA Paramount®. This is a premier package policy that integrates CNA general liability insurance with other critical coverages. The beauty of Paramount is its modularity; you can add or subtract coverages based on your specific risk profile, making it a highly efficient way to manage general risk insurance. Paramount is designed for businesses with more complex operations that require higher limits and specialized endorsements. It allows for a unified approach to risk, reducing the likelihood of coverage gaps between different policies.
Tailoring CNA General Liability Insurance for High-Risk Industries
Certain industries face much higher stakes than others. CNA has developed specific endorsements and sub-brands to handle these “tough” risks. For instance, Cardinal E&S—a CNA brand—is dedicated to the excess and surplus market, providing solutions for businesses that might struggle to find coverage in the standard market due to their high-risk nature or unique loss history. This ensures that even businesses in volatile sectors have access to the security of a major carrier.
For those in the building trades, general liability insurance for contractors is a non-negotiable requirement. CNA provides a specialized Contractor’s General Liability Extension Endorsement (GLEE). This endorsement packs in extra protections that contractors specifically need, such as:
- Blanket Additional Insured: Automatically covers entities you are contractually required to protect, such as project owners or general contractors, without needing to name each one individually on the policy. This saves time and reduces administrative errors.
- Waiver of Subrogation: Prevents the insurer from seeking recovery from a third party you’ve agreed to protect in a written contract, which is a standard requirement in most commercial construction contracts.
- Product Withdrawal Expense: Covers the costs if a faulty product you installed needs to be recalled or removed due to a known defect that could cause bodily injury or property damage. This is critical for manufacturers and installers alike.
- Per Project Aggregate: Ensures that your policy limits apply separately to each project you work on, preventing a single large claim on one job from exhausting your coverage for all other ongoing projects. This is a vital protection for contractors managing multiple job sites simultaneously.
In manufacturing, CNA offers Errors and Omissions (E&O) integrated with the CGL policy, providing a capacity of up to $10 million. This is vital for manufacturers who face risks not just from physical damage, but from the financial loss caused by a product that fails to perform as intended. For example, if a manufacturer produces a specialized valve that doesn’t break but fails to regulate pressure correctly, causing a factory shutdown, the resulting financial loss would be covered under the E&O portion of the policy. This integrated approach ensures that the “gray area” between a product failure and a physical accident is fully covered.
Healthcare and Financial Institution Protections
CNA is a titan in the healthcare space. They are one of the top five underwriters of healthcare professional liability in the country, with over 40 years of experience. This expertise carries over into their CNA general liability insurance for aging services, hospitals, and clinics. They understand that in healthcare, a general liability claim (like a visitor falling) is often intertwined with a professional liability claim (like a patient falling during treatment).
For general liability insurance for healthcare providers, CNA understands the delicate balance between professional malpractice and general premises liability. They even have a preferred relationship with LeadingAge, the national association for non-profit aging services providers. Their policies are designed to address the unique risks of patient transport, medical equipment failure, and the specific privacy concerns associated with HIPAA compliance. Financial institutions also benefit from the Paramount structure, which addresses the unique professional and civil liabilities faced by banks, credit unions, and investment firms. Whether it is a slip in the branch lobby or a complex legal obligation to a third party regarding the management of assets, CNA’s industry-specific knowledge ensures there are no gaps in the “safety net.”
Advanced Risk Management and Claims Support
Buying insurance is only half the battle; preventing the claim from happening in the first place is where the real value lies. This is where CNA truly shines with its Risk Control services. When you hold a CNA general liability insurance policy, you gain access to a wealth of resources designed to make your workplace safer and your business more resilient. CNA employs over 100 risk control professionals who specialize in various industries, providing on-site evaluations and virtual consultations that help identify hazards before they lead to injuries.
One of their standout tools is PrepWise®. This resource helps businesses prepare for various threats, from severe weather events (a must for us here in Florida!) to daily operational hazards. PrepWise provides checklists, training modules, and real-time alerts to help business owners mitigate risk before it turns into a loss. They also provide a specialized Slip and Fall Claim Kit, which gives your staff a step-by-step guide on what to do immediately after an accident occurs. This immediate response is critical for mitigating the severity of a claim and ensuring all necessary evidence, such as photos and witness statements, is preserved. By following these protocols, businesses can often reduce the ultimate cost of a claim by 20% or more.
The Power of Experience in Claims Handling
If a claim does occur, you want someone in your corner who has seen it all before. CNA’s claims professionals apply an average of 20 years of industry experience. They aren’t just processing paperwork; they have a robust understanding of loss trends and the specific severities associated with different industries. This deep expertise allows them to identify fraudulent claims early and negotiate fair settlements for legitimate losses. Their goal is to protect your reputation as much as your bottom line.
For example, in the construction sector, they analyze claims trends to help policyholders understand where their biggest vulnerabilities lie—whether it’s ladder safety, scaffolding issues, or subcontractor management. This data-driven approach allows for better defense strategies and more accurate settlements. Their goal isn’t just to “pay and close” but to ensure the business can continue to operate with minimal disruption. CNA also utilizes a network of preferred legal counsel who specialize in insurance defense, ensuring that your business is represented by the best in the field. These attorneys are vetted for their track record in specific jurisdictions, which is vital in Florida’s complex legal landscape.
Loss Control Surveys and Consultations
CNA offers comprehensive loss control surveys for mid-to-large sized businesses. During these surveys, a specialist will visit your facility to identify potential hazards that could lead to general liability claims. They look at everything from floor surfaces and lighting to employee training programs and contractual agreements with vendors. Following the survey, you receive a detailed report with actionable recommendations to improve your risk profile. Implementing these recommendations not only makes your business safer but can also lead to lower insurance premiums over time as your risk profile improves. This proactive approach transforms insurance from a static expense into a dynamic tool for business improvement.
Expanding Your Protection with Complementary Casualty Products
While CNA general liability insurance is the foundation of your protection, it often needs to be part of a larger strategy. As businesses grow, the standard limits of a general liability policy—typically $1 million per occurrence and $2 million aggregate—might not be enough to satisfy a major contract or protect against a catastrophic lawsuit. In today’s legal environment, “nuclear verdicts” (jury awards exceeding $10 million) are becoming more common, making higher limits a necessity for any business with significant assets.
Umbrella and Excess Liability
An umbrella insurance policy provides an extra layer of protection that sits on top of your general liability, commercial auto, and employer’s liability policies. If a major accident results in a $5 million judgment but your CGL policy only covers $1 million, the umbrella policy kicks in to cover the remaining $4 million. CNA offers significant capacity in both umbrella and excess liability, with the ability to provide limits of $25 million or more for qualified risks. This ensures that even the largest Florida enterprises are protected from total financial ruin in the event of a catastrophic loss. Umbrella policies also often provide broader coverage than the underlying policies, filling in small gaps that might otherwise exist.
International Solutions and Oneworld+
In today’s global economy, even a mid-sized manufacturer in Florida might have sales or operations overseas. Standard domestic policies often stop at the border, leaving a massive gap in coverage for international travel, foreign trade shows, or overseas sales offices. CNA’s Oneworld+® Casualty product offers a single master policy for global exposures. This eliminates the need for a complex web of local endorsements and ensures consistent coverage regardless of where your business takes you. Oneworld+ includes coverage for foreign voluntary workers’ compensation, contingent auto liability, and international general liability, all managed through CNA’s global network of partners. This global reach is essential for businesses looking to expand into international markets without taking on unmanaged risks.
Integrating CNA General Liability Insurance with Professional and Cyber Liability
There is often confusion between general liability and professional liability (also known as Errors and Omissions). We’ve put together a general liability vs errors and omissions guide to help clarify this, but the short version is: CGL covers physical accidents (bodily injury and property damage), while E&O covers financial mistakes in your professional work.
CNA makes it easy to bridge this gap. For technology and manufacturing firms, they offer integrated general liability errors and omissions insurance with limits up to $10 million. This ensures that if a software glitch causes a client to lose money, or a manufactured part fails to work as promised, you aren’t left holding the bill. Furthermore, CNA’s cyber liability offerings can be bundled with your general liability policy, providing protection against data breaches, ransomware, and business interruption caused by cyberattacks—a critical need for any business handling sensitive customer data. In the modern world, a data breach can be just as damaging to a business as a physical fire, and CNA’s integrated approach ensures both risks are addressed.
Why Businesses Trust CNA General Liability Insurance for Comprehensive Protection
When choosing an insurance carrier, their financial stability is just as important as the policy language. You need to know that the company will be there to pay a claim five, ten, or twenty years from now. This is especially true for general liability, where claims for “completed operations” can arise years after a project is finished. A carrier that disappears or goes insolvent leaves you personally liable for those old claims.
CNA is one of the most respected names in the industry for several reasons:
- Financial Strength: AM Best has upgraded CNA’s financial strength rating to A+ (Superior). This is a clear indicator of their ability to meet their ongoing insurance obligations and their robust capital position. Standard & Poor’s also maintains a strong rating for CNA, reflecting their consistent performance in the casualty market and their ability to withstand economic downturns.
- Longevity: Founded in 1897, CNA has over 125 years of history. With over 40 years of experience in specialized sectors like healthcare and construction, they have weathered every economic cycle, from the Great Depression to the 2008 financial crisis and the recent global pandemic. This longevity provides a level of institutional knowledge that newer carriers simply cannot match.
- Industry Recognition: They are one of the top five underwriters of healthcare professional liability products in the United States and a leading provider of commercial insurance for the manufacturing and technology sectors. Their reputation is built on a foundation of technical underwriting and fair claims handling.
- Local Presence: While they are a global powerhouse, they have a strong presence in Florida, understanding the unique risks we face from hurricanes to our specific litigious environment. They have dedicated underwriters and claims adjusters who live and work in the Sunshine State, providing a level of local insight that national-only carriers can’t match. You can find more about state-specific needs in our florida general liability insurance guide.
Choosing CNA general liability insurance means partnering with a carrier that values expertise and data-driven risk management as much as you value your business. Their commitment to the independent agency system ensures that you have a local advocate at Florida All Risk Insurance who can help you navigate the complexities of your policy and ensure you are getting the best possible value for your premium dollar.
Frequently Asked Questions about CNA General Liability
How quickly can I obtain a quote for CNA coverage?
Through the modern underwriting systems used by CNA and independent agencies like Florida All Risk Insurance, many small business owners can receive a quote in as little as five minutes for standard risks. For more complex risks, such as large construction firms, healthcare facilities, or international manufacturers, the process involves a more detailed review by an experienced underwriter to ensure the coverage is perfectly customized. This might take a few business days as we gather necessary loss runs and safety documentation. You can start the process today by requesting a general liability insurance quote through our website.
Does CNA offer specialized coverage for international business exposures?
Yes. Through their Oneworld+® platform, CNA provides comprehensive casualty coverage for businesses with global operations. This includes international general liability, automobile liability, and foreign voluntary workers’ compensation, all managed under a streamlined master policy structure. This is particularly beneficial for Florida businesses that export goods or have employees traveling to South America, Europe, or Asia. It ensures that your business is protected by a carrier that understands local laws and regulations in foreign jurisdictions.
What is the difference between CNA Paramount® and CNA Connect®?
CNA Connect® is specifically designed for small businesses (typically those with lower revenue and fewer employees). It is a “Business Owners Policy” (BOP) that simplifies the buying process by bundling general liability with property insurance into a single, affordable package. CNA Paramount® is a more robust, modular package policy intended for mid-sized and large organizations that require higher limits and more specialized endorsements tailored to specific industries like real estate, financial institutions, or law firms. Paramount allows for much greater customization of limits and sub-limits to match complex risk profiles.
Can I add Cyber Liability to my CNA General Liability policy?
Absolutely. CNA offers several ways to add cyber protection. For small businesses using CNA Connect, cyber coverage can often be added as a simple endorsement, providing basic protection against data breaches. For larger firms, CNA offers a standalone cyber policy that can be integrated into the Paramount package, providing comprehensive protection against data breaches, network extortion, and digital asset restoration. This integrated approach ensures that your cyber risks are managed alongside your physical risks, providing a more complete safety net for your digital assets.
Conclusion
Navigating commercial insurance can feel like sailing into a storm, but with the right partner, it doesn’t have to be. CNA general liability insurance offers a level of stability and specialized protection that is hard to match in the current marketplace. From the common slip-and-fall to complex international casualty risks and high-stakes professional liability, CNA’s suite of products—backed by an A+ financial rating—provides the security Florida business owners need to grow and thrive in an uncertain world. Their commitment to risk control and expert claims handling ensures that you aren’t just buying a policy, but a comprehensive risk management partner.
At Florida All Risk Insurance, we take pride in being an independent agency. We don’t work for the insurance companies; we work for you. Our team in Saint Petersburg understands the local market and can help you determine if a CNA policy is the right fit for your specific needs. We look at your business holistically, identifying gaps in coverage and finding the most cost-effective ways to close them. Whether you are looking for general liability insurance in Tampa or a comprehensive package for a statewide operation, we are here to help you navigate the process with transparency and expertise.
Don’t leave your business’s future to chance. A single lawsuit without proper coverage can undo years of hard work and dedication. Let’s work together to build a shield of protection around your company, utilizing the strength and expertise of CNA. Our goal is to provide you with the coverage you need so you can focus on what you do best: running and growing your business. Contact us today to start a conversation about your risk management needs.
Ready to protect your business with a carrier you can trust?
Get a Personalized CNA General Liability Quote Today
Explore All Our Commercial Insurance Solutions
Contact Us
Florida All Risk Insurance
136 4th St N, Ste 200
Saint Petersburg, FL 33701
Email: [email protected]
Phone: (727) 555-0199

