

Why Every Consultant Needs a Safety Net
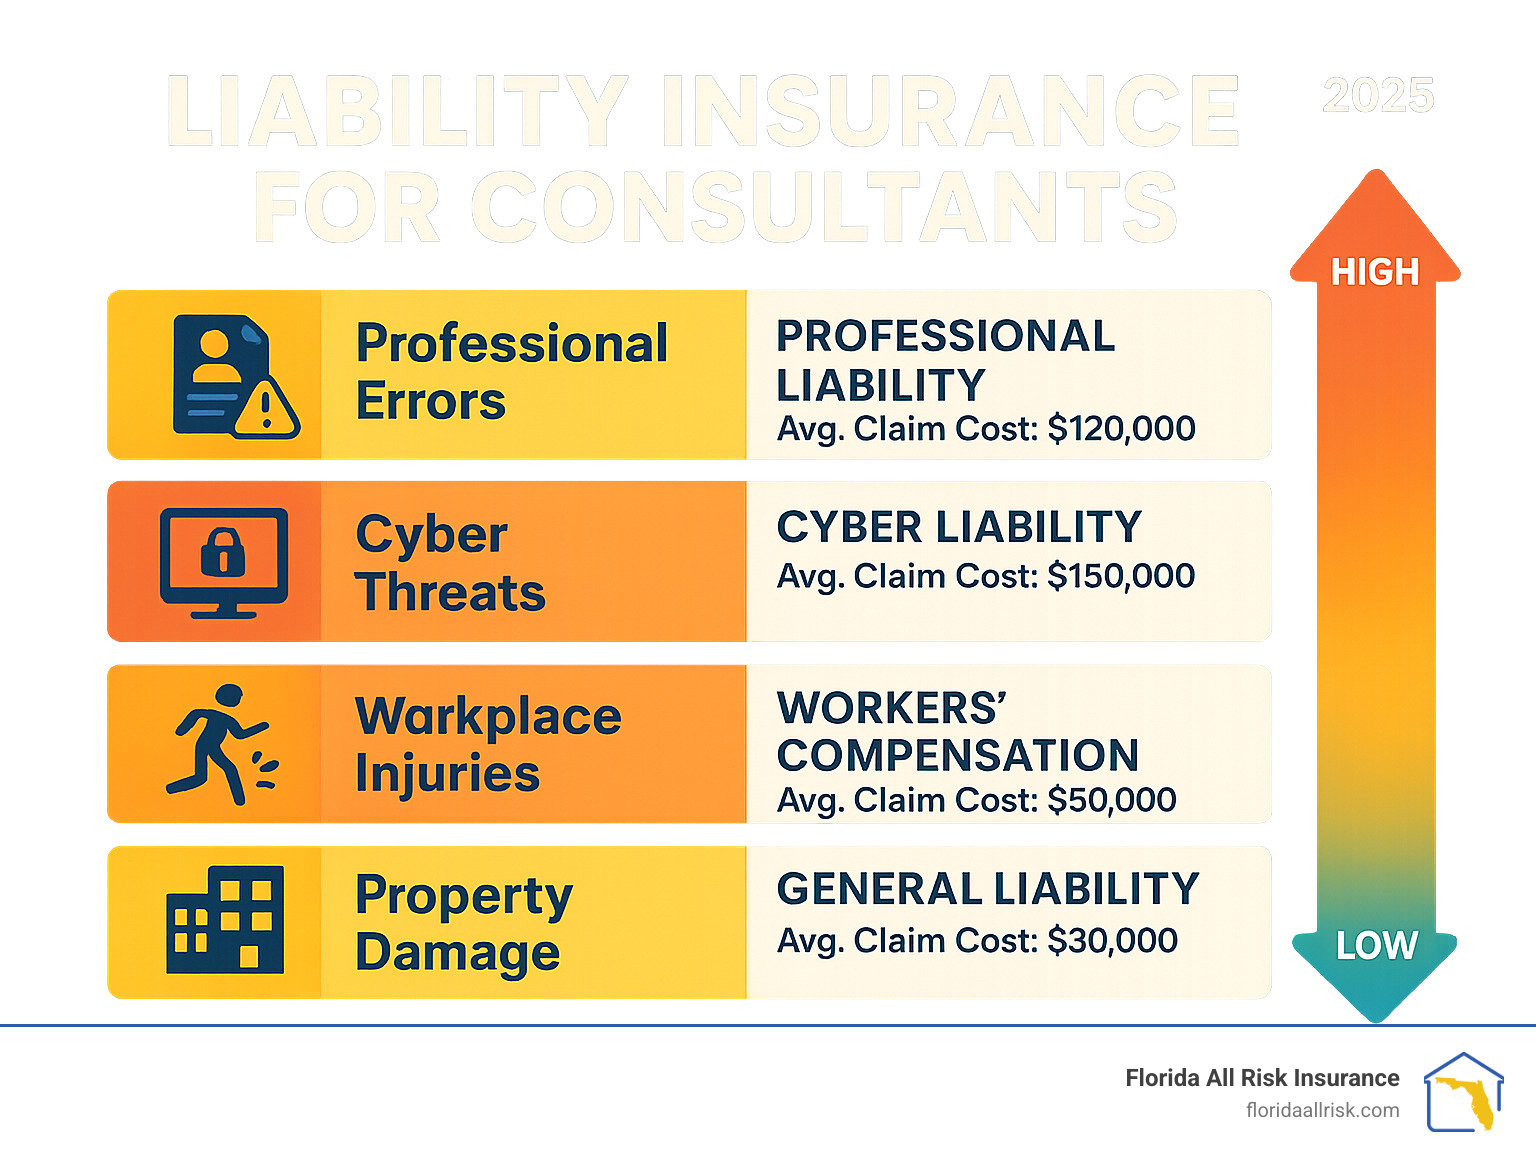
Liability insurance for consultants protects your business when clients claim your advice caused financial loss, when someone gets injured at your office, or when a data breach exposes sensitive information. Here’s what you need to know:
Essential Coverage Types:
- Professional Liability (E&O) – Covers claims about bad advice or missed deadlines
- General Liability – Protects against slip-and-fall accidents and property damage
- Cyber Liability – Handles data breaches and ransomware attacks
- Workers’ Compensation – Required in most states if you have employees
Average Costs:
- General liability: $29/month
- Professional liability: $55/month
- Cyber insurance: $92/month
Why It Matters:
Most clients require proof of insurance before hiring you. Even if you haven’t done anything wrong, legal defense costs can bankrupt your business. A single lawsuit can cost tens of thousands in attorney fees alone.
The consulting industry is booming, but so are the risks. Whether you’re a management consultant advising on million-dollar decisions or a marketing consultant creating campaigns, your professional advice puts you in the legal crosshairs. One missed deadline, one data error, or one client who doesn’t get the results they expected can trigger a lawsuit that threatens everything you’ve built.
But here’s the good news: the right insurance coverage turns these business-ending risks into manageable expenses. Smart consultants don’t just focus on growing their revenue – they protect it too.
I’m Jason Miller, and I’ve spent over 20 years helping Florida professionals steer complex insurance decisions, including finding the right liability insurance for consultants who need comprehensive protection. My experience working with thousands of businesses has shown me that the consultants who sleep best at night are the ones who’ve built a solid insurance foundation under their growing practice.
Quick look at Liability insurance for consultants:
- general liability errors and omissions insurance
- professional liability insurance for independent contractors
- general civil liability
Liability Insurance for Consultants: What It Really Means
Let’s cut through the insurance jargon and get to what liability insurance for consultants actually does. At its core, liability insurance protects you when someone claims you caused them financial harm, bodily injury, or property damage through your professional services or business operations.
Professional liability insurance, also known as errors and omissions (E&O) insurance, covers claims arising from your professional advice or services. This includes allegations of negligence, errors, omissions, misrepresentation, or failure to deliver promised results. Even if you haven’t done anything wrong, this coverage pays for your legal defense and any settlements or judgments.
The key word here is “claims.” Your insurance kicks in when someone files a lawsuit or makes a formal demand for compensation. It doesn’t matter if their claim has merit – the insurance company will investigate and defend you regardless.
Why Do Consultants Need It?
We’ve seen three main drivers that make liability insurance essential for consultants:
Client Requirements: Most clients require proof of insurance before signing contracts. This isn’t just corporate paranoia – it’s smart business. When a client invests thousands or millions based on your recommendations, they want assurance that you can cover mistakes that could cost them money.
Contract Protection: Many consulting agreements include indemnification clauses requiring you to defend and hold harmless your clients from claims arising from your work. Without insurance, you’re personally on the hook for these costs.
Reputation Shield: Even a frivolous lawsuit can damage your professional reputation. Insurance provides experienced legal counsel who knows how to handle these situations while protecting your business relationships.
Peace of Mind: Knowing you’re covered lets you focus on growing your practice instead of worrying about worst-case scenarios.
Is It Legally Required?
Professional liability insurance is not mandatory by law for consultants in Florida or most other states. However, this doesn’t mean you can skip it. Here’s what we tell our clients:
State Requirements: While not legally required, some professional licensing boards may require or recommend coverage for certain types of consulting work.
Independent Contractor Status: If you work as an independent contractor, you typically can’t rely on a client’s insurance to cover your professional mistakes. You need your own coverage.
Professional Standards: Many industry associations and professional organizations require members to carry liability insurance as part of their ethical standards.
Practical Necessity: Even though it’s not legally required, it’s practically essential. Most clients won’t hire uninsured consultants, making coverage a business necessity rather than a legal requirement.
Key Types of Liability Coverage Consultants Need
Think of consultant insurance as a puzzle – you need multiple pieces to create complete protection. Here are the essential coverage types we recommend:
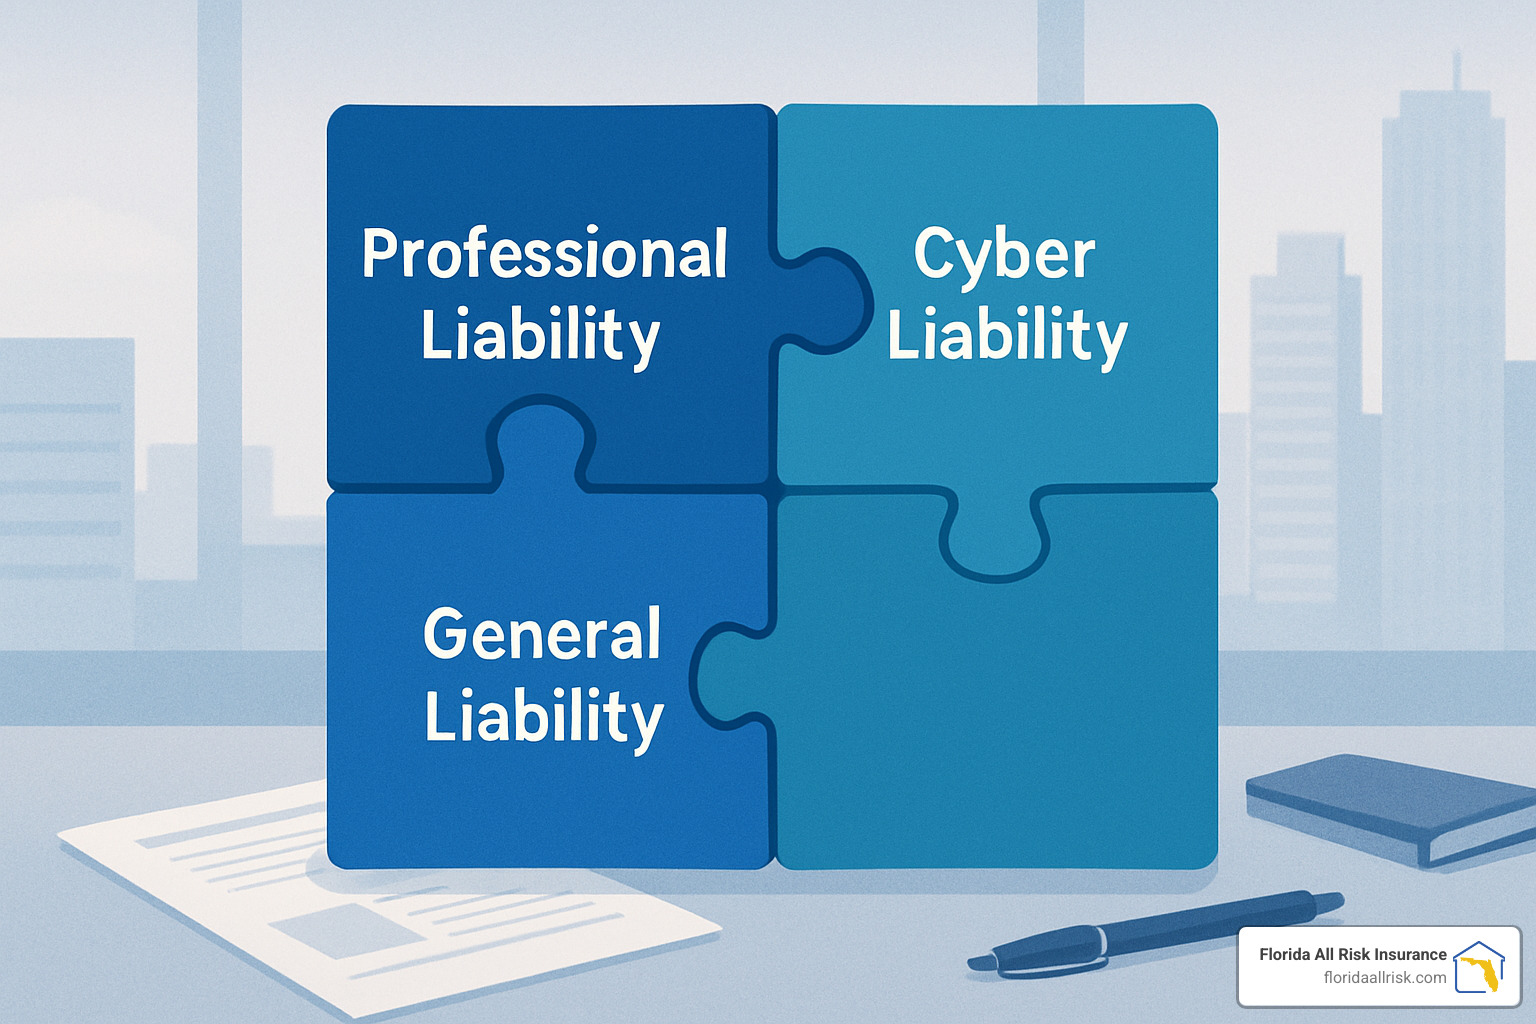
Professional Liability (E&O): Covers claims related to your professional advice, services, or failure to deliver promised results. This is your primary protection against client lawsuits.
General Liability: Protects against third-party bodily injury, property damage, and advertising injury claims. This covers the basics like slip-and-fall accidents at your office.
Cyber Liability: Handles data breaches, ransomware attacks, and privacy violations. With over 40% of small businesses experiencing cyberattacks annually, this coverage is becoming essential.
Workers’ Compensation: Required in most states if you have employees. Covers medical expenses and lost wages for work-related injuries.
Commercial Auto: Necessary if you use vehicles for business purposes. Personal auto policies typically exclude business use.
Fidelity Bond: Protects against employee theft and dishonesty. Important if employees handle client funds or sensitive information.
Umbrella Coverage: Provides additional liability limits above your primary policies. Essential for high-exposure consulting work.
Professional Liability (E&O) vs. General Liability – Spot the Difference
Many consultants get confused about the difference between professional liability and general liability insurance. Here’s how they compare:
| Coverage Type | Professional Liability (E&O) | General Liability |
|---|---|---|
| Primary Purpose | Protects against claims from professional services | Protects against bodily injury and property damage |
| Trigger Events | Bad advice, missed deadlines, errors in work | Slip-and-fall, property damage, advertising injury |
| Coverage Scope | Financial losses from professional mistakes | Physical injuries and property damage |
| Policy Form | Claims-made (covers claims made during policy period) | Occurrence (covers incidents that happen during policy period) |
| Defense Costs | Included in policy limits | Usually separate from policy limits |
| Average Cost | $55/month for consultants | $29/month for consultants |
Professional Liability kicks in when a client claims your advice caused financial harm. For example, if a marketing consultant’s campaign strategy fails and the client loses revenue, professional liability covers the resulting lawsuit.
General Liability handles physical incidents and property damage. If a client slips on a wet floor in your office and breaks their ankle, general liability covers their medical bills and any lawsuit.
You need both types of coverage because they protect against different risks. Professional liability won’t cover a slip-and-fall accident, and general liability won’t cover claims about bad advice.
For more detailed information about these coverage types, check out our general liability errors and omissions insurance page.
Cyber Liability—More Than IT Consultants Need
Don’t think cyber liability is just for IT consultants. Any consultant who stores client data electronically, sends emails, or uses cloud-based systems faces cyber risks. Here’s what cyber liability covers:
First-Party Coverage (your own losses):
- Data recovery and system restoration
- Business interruption from cyber incidents
- Ransom payments (where legally permitted)
- Public relations expenses to manage reputation damage
Third-Party Coverage (claims against you):
- Client lawsuits over data breaches
- Regulatory fines and penalties
- Notification costs for affected individuals
- Credit monitoring services for breach victims
With cyber insurance averaging $92 per month and over 40% of small businesses experiencing cyberattacks annually, this coverage is becoming as essential as professional liability insurance.
Bundled Policies & BOPs
A Business Owner’s Policy (BOP) bundles general liability and commercial property insurance into one policy, often at a discount compared to buying them separately. For consultants who qualify, BOPs can provide:
- Cost Savings: Up to 25% less than separate policies
- Simplified Management: One policy, one renewal, one deductible
- Comprehensive Coverage: Property protection plus liability coverage
However, BOPs typically don’t include professional liability coverage, so you’ll still need separate E&O insurance. Some insurers offer multi-product discounts when you bundle professional liability with a BOP.
Real-World Risks & Claims Scenarios
Let’s look at actual scenarios that trigger consultant liability claims. These aren’t hypothetical – they’re based on real claims we’ve seen:

The Missed Deadline: An HR consultant fails to file required compliance reports on time, resulting in regulatory fines for the client. The client sues for the fine amount plus additional damages.
The Bad Advice: A financial consultant recommends an investment strategy that results in significant losses. The client claims the advice was negligent and sues for their losses.
The Slip-and-Fall: A client visits your office for a presentation, slips on a wet floor, and breaks their wrist. They sue for medical expenses and lost wages.
The Coffee Catastrophe: During a client meeting, you accidentally spill coffee on their laptop, destroying important files. They demand compensation for the damaged equipment and lost data.
The Data Hack: A hacker breaches your email system and steals client financial information. Multiple clients sue for privacy violations and identity theft damages.
The Employee Theft: Your assistant embezzles client funds from trust accounts. Clients demand full restitution plus damages.
What Consultant Liability Insurance Would Cover
When these scenarios happen, your insurance provides several layers of protection:
Defense Costs: Your insurance company assigns experienced attorneys to defend you. Legal fees can easily reach $50,000-$100,000 even for cases that don’t go to trial.
Settlement Payments: If your insurance company determines it’s better to settle than fight, they’ll pay the agreed settlement amount up to your policy limits.
Judgments: If a case goes to trial and you lose, your insurance pays the judgment amount up to your policy limits.
Investigation Costs: Insurance companies investigate claims to determine coverage and build your defense.
Public Relations Expenses: Some policies include coverage for PR professionals to help manage reputation damage from high-profile claims.
Common Exclusions to Watch For
No insurance policy covers everything. Here are common exclusions in consultant liability policies:
Intentional Acts: Insurance doesn’t cover deliberate wrongdoing or criminal acts.
Fraud and Dishonesty: Fraudulent misrepresentation or dishonest acts are typically excluded.
Prior Known Issues: Claims arising from problems you knew about before buying the policy.
Contract Penalties: Liquidated damages or penalty clauses in contracts are often excluded.
Employment Practices: Discrimination, harassment, and wrongful termination claims usually require separate coverage.
Cyber Incidents: Unless you have cyber liability coverage, data breaches and cyber attacks are excluded from traditional policies.
Cost Breakdown & Smart Ways to Save
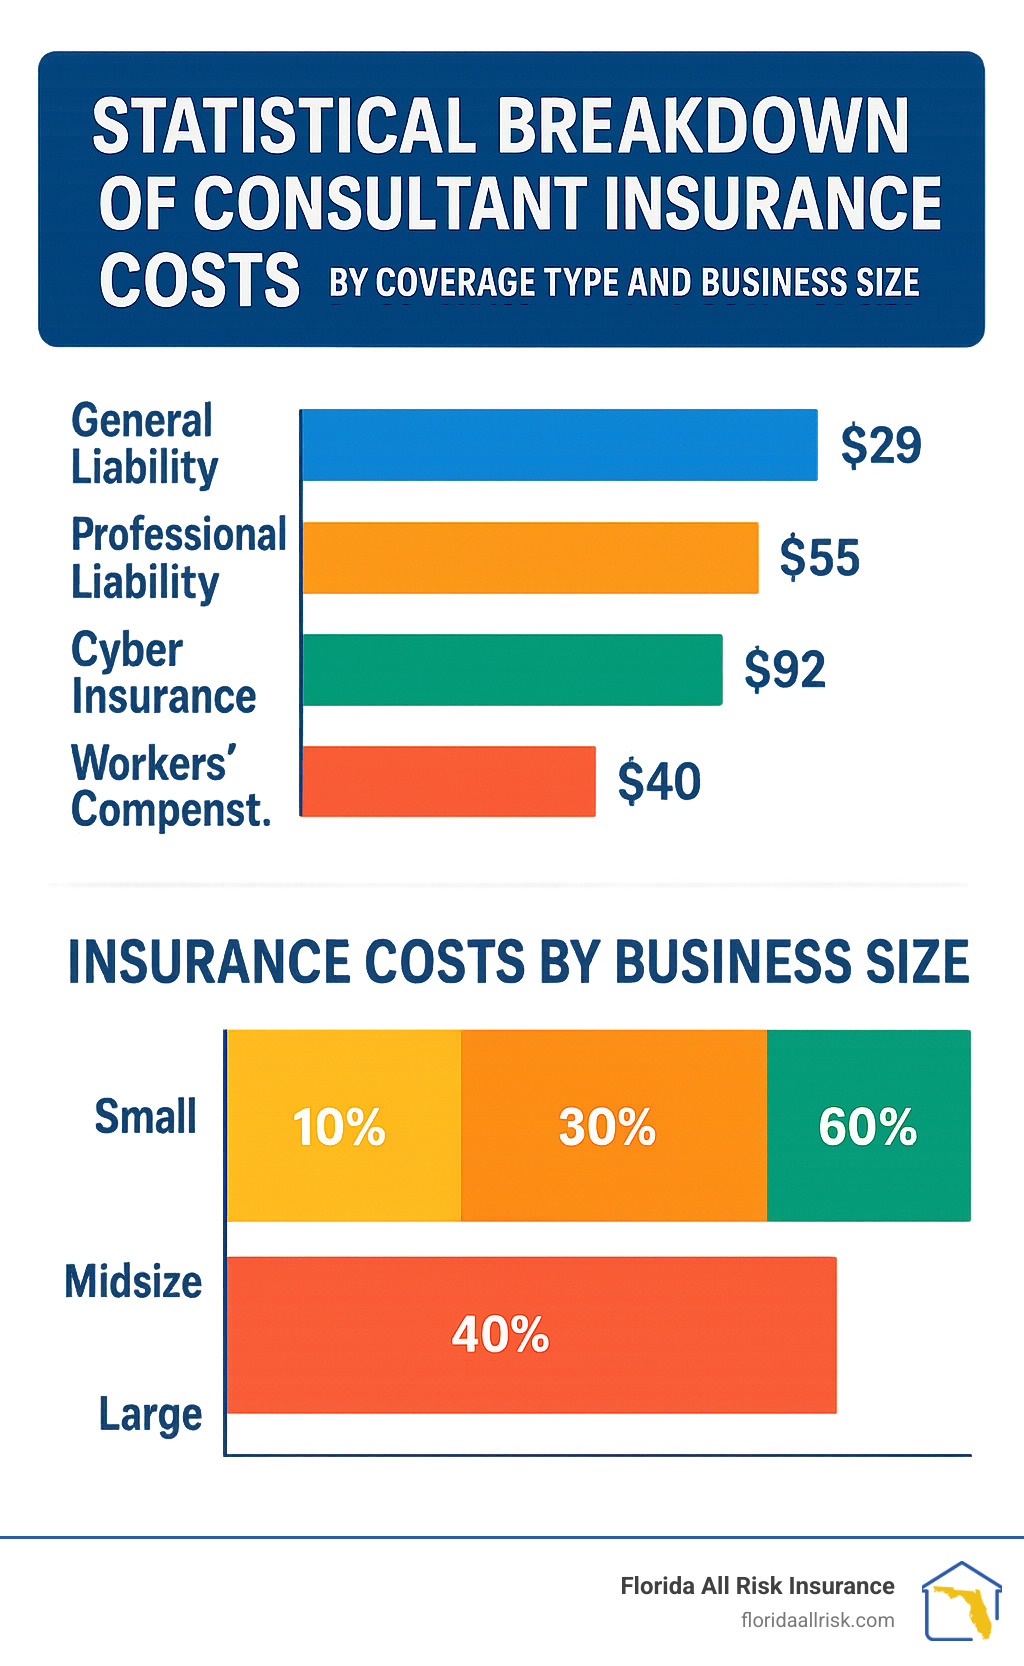
Let’s talk money. Based on our research and experience, here’s what consultants typically pay for liability insurance:
- General Liability: $29 per month average
- Professional Liability: $55 per month average
- Cyber Insurance: $92 per month average
- Workers’ Compensation: $40 per month average
Several factors affect your premiums:
Annual Revenue: Higher revenue usually means higher premiums because it indicates larger potential claims.
Claims History: A clean claims record can reduce premiums by 10-20%.
Coverage Limits: Higher limits cost more, but the relationship isn’t linear. Doubling your limits might only increase premiums by 25-50%.
Industry Risk: Some consulting specialties (like financial or medical consulting) carry higher risks and premiums.
Business Location: Urban areas typically have higher premiums due to increased lawsuit frequency.
Years in Business: Established consultants often get better rates than new businesses.
Coverage Limits & Deductibles: How Much Is Enough?
Most consultants carry $1 million per occurrence and $2 million aggregate limits for both professional and general liability. However, your needs might vary:
Project Size Matters: If you work on million-dollar projects, consider higher limits. A $100,000 mistake on a $10 million project could easily trigger a lawsuit exceeding basic coverage limits.
Client Requirements: Many clients require minimum coverage amounts. Corporate clients often demand $2-5 million in coverage.
Personal Assets: If you have significant personal assets, higher limits or umbrella coverage protects against claims exceeding your primary policy limits.
Deductible Choices: Higher deductibles can reduce premiums by 10-25%, but make sure you can afford the out-of-pocket expense if you need to file a claim.
Money-Saving Tips Without Cutting Coverage
You can save up to 35% on consultant insurance with these strategies:
Compare Quotes: Prices vary significantly between insurers. We recommend getting quotes from at least three carriers.
Bundle Policies: Multi-policy discounts can save 10-25% when you buy multiple coverages from the same insurer.
Pay Annually: Annual payments often include 5-10% discounts compared to monthly payments.
Risk Management: Implementing formal risk management practices can qualify you for discounts with some insurers.
Professional Associations: Some industry associations offer group insurance programs with discounted rates.
Clean Claims History: Maintaining a claims-free record is the best long-term strategy for keeping premiums low.
According to the Insurance Information Institute, businesses that implement comprehensive risk management programs can reduce their insurance costs by 15-30% over time.
For more information about business liability options, visit our business liability insurance page.
Buying & Using Your Policy
Getting consultant insurance is easier than most people think. Here’s how the process works:
Getting a Quote in Minutes
Modern insurance buying is fast and convenient:
Basic Information: You’ll need your business name, address, years in operation, and number of employees.
Revenue Details: Most insurers ask for current year revenue and projections for the next year.
Industry Classification: Specific consulting specialty codes help insurers assess risk accurately.
Coverage Preferences: Choose your desired limits, deductibles, and coverage types.
Instant Quotes: Many insurers provide quotes within minutes of completing the application.
Certificate of Insurance: Once you purchase coverage, you can usually generate certificates of insurance immediately for client requirements.
How the Claims Process Works
If you need to file a claim, here’s what happens:
Immediate Notification: Report potential claims as soon as you become aware of them. Most policies require “prompt” notification.
Initial Investigation: The insurance company assigns a claims adjuster to investigate the circumstances and determine coverage.
Legal Counsel: For liability claims, the insurer typically assigns experienced attorneys to handle your defense.
Settlement Negotiations: If appropriate, your legal team will negotiate with the claimant to reach a fair settlement.
Trial Defense: If settlement isn’t possible, your attorneys will defend you in court.
Resolution: Whether through settlement or trial verdict, the insurance company pays covered amounts up to your policy limits.
The entire process can take months or even years for complex cases, but your insurance company handles the heavy lifting while you focus on your business.
Frequently Asked Questions about Liability Insurance for Consultants
What risks does liability insurance for consultants not cover?
Liability insurance for consultants doesn’t cover everything. Common exclusions include:
- Intentional wrongdoing or criminal acts
- Employment practices violations (discrimination, harassment, wrongful termination)
- Cyber incidents (unless you have separate cyber liability coverage)
- Professional services outside your stated business activities
- Contract penalties and liquidated damages
- Personal activities unrelated to your business
The key is understanding your policy’s specific exclusions and buying additional coverage where needed.
How much does liability insurance for consultants cost on average?
Based on our research, consultants typically pay:
- Professional Liability: $55 per month ($660 annually)
- General Liability: $29 per month ($348 annually)
- Combined Coverage: $75-100 per month for both policies
However, costs vary significantly based on:
- Your consulting specialty and risk level
- Annual revenue and business size
- Coverage limits and deductibles
- Claims history and years in business
- Geographic location
Small consulting practices often pay less than $1,000 annually for comprehensive liability coverage, while large firms might pay $5,000-$10,000 or more.
Do solo consultants really need both professional and general liability?
Yes, solo consultants need both types of coverage because they protect against different risks:
Professional Liability covers claims about your advice and services – the core of your consulting business. This includes missed deadlines, bad advice, errors in deliverables, and failure to meet client expectations.
General Liability covers physical incidents and property damage. Even home-based consultants face risks like:
- Clients injured during office visits
- Accidental damage to client property
- Libel or slander claims from marketing materials
The combined cost is typically under $100 per month, making it affordable protection against business-ending lawsuits. Many clients also require both types of coverage before they’ll hire you.
For more specific information about coverage for independent contractors, check out our Professional Liability Insurance for Independent Contractors page.
Conclusion
Liability insurance for consultants isn’t just another business expense – it’s the foundation that lets you build and grow your practice with confidence. Whether you’re a solo consultant working from home or running a multi-person firm, the right insurance coverage protects everything you’ve worked to build.
The consulting industry continues to grow, but so do the risks. Client expectations are higher, lawsuits are more common, and cyber threats are everywhere. Smart consultants don’t wait for problems to happen – they prepare for them.
At Florida All Risk Insurance, we understand the unique challenges consultants face. We’ve helped thousands of Florida professionals find the right coverage at competitive rates. Our independent agency status means we can shop multiple carriers to find the best combination of coverage and price for your specific needs.
Don’t let insurance questions keep you up at night. The peace of mind that comes from proper coverage is worth far more than the modest premiums you’ll pay. Your consulting expertise is valuable – make sure it’s properly protected.
Ready to get started? We make the process simple and fast. Most consultants can get quotes and coverage in place within 24 hours. Contact us today to discuss your specific needs and get a customized quote.
For comprehensive information about professional liability coverage options, visit our Professional Liability Insurance for Independent Contractors page.
Contact Us
Florida All Risk Insurance
Saint Petersburg, FL
Email: [email protected]
We’re here to help you steer the complex world of consultant insurance and find the coverage that’s right for your business. Contact us today for a personalized consultation and competitive quotes from top-rated carriers.

