Why Independent Business Insurance Agents Are Your Best Business Ally
When it comes to protecting your business, having the right partner makes all the difference. Independent business insurance agents stand out as true allies in the complex world of commercial insurance. Unlike agents who work exclusively for one company, independent agents work for you, representing multiple insurance carriers and bringing a wealth of options to your doorstep.
Think of an independent agent as your personal insurance shopper. They have relationships with numerous insurance companies, allowing them to compare coverage options and pricing side by side. This breadth of choice is why approximately 80% of commercial insurance policies are placed through independent agents – business owners clearly recognize their value!
What sets these professionals apart is their ability to truly customize your protection. When you sit down with an independent business insurance agent, they’ll take time to understand your specific operations, concerns, and goals. This personalized approach means you’ll get coverage custom to your business, not a one-size-fits-all policy that leaves dangerous gaps.
| What Independent Business Insurance Agents Offer | Why This Matters |
|---|---|
| Access to multiple insurance carriers | More options and competitive pricing |
| Personalized risk assessment | Coverage custom to your specific business needs |
| Claims advocacy | Support throughout the claims process |
| Ongoing policy management | Regular reviews to adapt as your business grows |
| Local expertise | Understanding of regional risks and regulations |
Perhaps the greatest advantage comes when your business faces challenges. Running a high-risk operation or working in a specialized industry? Your independent business insurance agent has the flexibility to find carriers that specialize in those unique risks – options that simply aren’t available through captive agents tied to a single company.
Another key benefit is account ownership. Independent agents own and control their client relationships, policy records, and renewals. This means if a better option becomes available for your business, they can seamlessly move your coverage without you having to start from scratch with a new agent.
I’m Jason Miller, and as a second-generation insurance professional with over 20 years in the industry, I’ve watched independent business insurance agents help thousands of Florida businesses find perfect-fit coverage solutions. I’ve seen how their expertise saves business owners not just money, but also countless hours of research and worry.
Related content about independent business insurance agents:
– commercial property insurance
– business property insurance companies
– commercial lease liability insurance
What Are Independent Business Insurance Agents?
Independent business insurance agents are your business allies in the complex world of insurance. Unlike agents who work for just one company, these licensed professionals represent multiple insurance carriers, giving them the freedom to find coverage that truly fits your business needs.
Think of them as your personal insurance shoppers. They work on your behalf, connecting your business with various insurance companies to find the perfect match. It’s no wonder they dominate the commercial insurance landscape – independent agents handle about 80% of all business insurance in the United States.
One of the biggest advantages? Your independent agent actually owns your account. This means if your current insurer raises rates or no longer meets your needs, your agent can seamlessly move your business to another carrier. No starting over, no headaches, just continued protection.
As Stefan DeShazo, an independent agent from Houston, puts it: “Independent agents aren’t held captive by one company. They’re free to tailor solutions to fit you, your needs, your life, to help you make the choices that are right for you.”
Most independent agents work with an impressive lineup of insurance partners – typically thirteen property and casualty companies and six life and health insurers. This diversity translates directly into more options for your business.
Key Features of Independent Business Insurance Agents
Market Access is perhaps their greatest strength. With connections to numerous insurance carriers, independent business insurance agents can access specialized coverage options that might be impossible to find through standard channels. This becomes especially valuable when your business has unique risks that require custom protection.
Personalized Advice sets these agents apart from impersonal online quotes. They take time to understand your operations, identify potential risks, and recommend appropriate coverage. As one business owner shared: “There is nothing more valuable than a consultative agent who considers your interests when shopping for coverage.”
Ongoing Support extends well beyond your initial policy purchase. Your independent agent becomes a valuable business partner who provides continuous guidance through policy reviews, claims assistance, and coverage adjustments as your business grows. They’re not just selling you insurance – they’re helping protect your business journey for the long haul.
Independent vs. Captive vs. Direct: Understanding Agent Types
Choosing the right insurance partner for your business is a bit like dating – you need someone who truly understands your needs and has your best interests at heart. Let’s break down the three main types of insurance agents you’ll encounter in your search for the perfect match:
Independent Agents work with multiple insurance companies rather than being tied to just one. Think of them as your personal insurance shoppers who can compare policies across different carriers to find your best fit. They work for agencies, not insurers, giving them the freedom to recommend what’s truly best for your business. Their compensation comes from commissions paid by the insurance companies they represent.
Captive Agents are the loyal employees of a single insurance company. While they often know their company’s products inside and out, their options are limited to what their employer offers. If their company doesn’t have competitive rates or the specific coverage your business needs, they simply can’t offer alternatives.
Direct Sales Agents work directly for insurance companies and sell policies through call centers or online platforms. They typically focus on standardized, one-size-fits-all products and may lack the personalized touch that independent and captive agents provide.
Here’s how these three agent types stack up against each other:
| Feature | Independent Agents | Captive Agents | Direct Sales Agents |
|---|---|---|---|
| Carrier Options | Multiple (avg. 13+ carriers) | Single company | Single company |
| Product Range | Comprehensive | Limited to one carrier | Limited to one carrier |
| Pricing Comparison | Yes, across multiple carriers | No | No |
| Account Ownership | Agent owns client relationships | Carrier owns client relationships | Carrier owns client relationships |
| Personalized Service | High | Medium to High | Low to Medium |
| Local Presence | Typically local | Typically local | Often remote/centralized |
| Claims Advocacy | Strong advocacy role | Limited by carrier policies | Limited by carrier policies |
As one independent business insurance agent once told me: “Choice is something we as Americans can’t even imagine doing without. But independent agents aren’t held captive by one company. They’re free to tailor solutions to fit you, your needs, your life, to help you make the choices that are right for you.”
When you work with an independent agent, you gain a partner who can move your policies to different carriers if better options become available. This portability is a significant advantage that captive and direct agents simply cannot offer.
For more comprehensive information about your insurance buying options, check out the Insurance Information Institute’s background on buying insurance.
Pros & Cons of Independent Business Insurance Agents
Let’s be honest – nothing in life is perfect, and that includes insurance relationships. Here’s a balanced look at what you can expect when working with an independent business insurance agent.
The Good Stuff:
Working with independent agents gives you access to multiple insurance markets, allowing them to find the best coverage and rates for your specific business needs. With an average of thirteen property and casualty insurers at their fingertips, they offer significantly more options than captive agents.
Independent agents typically provide more personalized attention and take the time to understand your business thoroughly. As one satisfied client put it: “My experience with this agency was great! They are knowledgeable in any questions you may have.”
Because they’re not tied to a single carrier, independent agents can provide more objective recommendations based on your best interests rather than pushing products from just one company. When claims happen (and they will), independent agents advocate on your behalf, helping steer the claims process and ensuring fair treatment.
Perhaps best of all, independent agents serve as your one-stop shop for all insurance needs, handling multiple lines of business coverage through different carriers while giving you a single point of contact.
The Not-So-Good Stuff:
Independent agents earn commissions from insurance companies – typically 5% to 15% of first-year premiums for property and casualty insurance, and 2% to 5% on renewals. While this doesn’t directly increase your costs, it’s important to understand how your agent makes money.
Some agents might recommend additional coverage or higher limits partly to increase their commission. That’s why finding a reputable agent who puts your needs first is essential.
Not all independent agents have the same expertise in every industry. Finding someone with experience in your specific business sector can make a world of difference in the quality of coverage you receive.
Smaller independent agencies might not offer the same technological conveniences (like fancy online portals or apps) as large direct writers, though this gap is closing rapidly as technology becomes more accessible.
As one industry expert notes: “For very expensive policies, a fee-only planner can be more objective since they don’t earn commissions.” However, for most business insurance needs, the benefits of working with an independent business insurance agent typically far outweigh these potential drawbacks.
How Independent Agents Help You Secure the Right Coverage
When you’re running a business, finding the right insurance coverage can feel like navigating a maze. This is where independent business insurance agents truly shine. They don’t just sell policies—they guide you through a thoughtful process that ensures your business has protection custom to your specific needs.
Your journey with an independent agent typically begins with a comprehensive risk assessment. They’ll sit down with you and ask thoughtful questions about your day-to-day operations, valuable assets, employee situations, and potential liability concerns. This conversation isn’t just checkbox questions—it’s a genuine effort to understand what makes your business unique.
As one seasoned insurance professional puts it: “There is nothing more valuable than a consultative agent who considers your interests when shopping for coverage.”
Independent business insurance agents can help protect your company with a variety of coverage types. They’ll explain how General Liability Insurance safeguards against common third-party claims, while Commercial Property Insurance protects your physical assets. If disaster strikes and interrupts your operations, Business Interruption Insurance can be a lifesaver.
They’ll also guide you through essential protections like Workers’ Compensation for employee injuries and Professional Liability coverage for service-based businesses. They can secure Cyber Liability Insurance to protect against data breaches. For businesses with vehicles, Commercial Auto Insurance is crucial, while Employment Practices Liability, Directors and Officers Liability, and Umbrella/Excess Liability provide additional layers of protection.
What truly sets independent agents apart is their ability to comparison shop on your behalf. The average independent agent works with thirteen different property and casualty carriers regularly. Instead of you making thirteen phone calls and trying to compare apples to oranges, they do the legwork and present you with clearly explained options.
One satisfied client shared: “Through accidents whether mine or not I’ve never had any problems and all of my questions through the years have been answered promptly and accurately.”
Perhaps most valuable is having an advocate in your corner when claims happen. When you’re dealing with property damage or a liability situation, your independent agent becomes your guide and champion, helping gather documentation and communicating with the insurance company on your behalf. This support can make all the difference during stressful times.
For more detailed information about insurance options for smaller companies, visit Florida All Risk’s small business insurance page.
Matching Policies to Unique or Complex Needs
Every business has its quirks and challenges. Some operate in high-risk industries, while others have unusual exposures that don’t fit neatly into standard insurance packages. This is where independent business insurance agents truly prove their worth.
For businesses with specialized needs, independent agents can access specialty markets and surplus lines carriers—insurers who handle risks that standard companies might turn away or price prohibitively.
Take Cyber Liability coverage, for example. With digital threats evolving daily, your business needs protection that evolves too. Independent agents can find specialized cyber policies custom to your specific digital footprint, whether you need coverage for data breach response, cyber-related business interruption, or customer data protection.
If you provide professional services, your agent can secure customized Professional Liability coverage (also called errors and omissions insurance) that specifically addresses the risks in your field, whether you’re an accountant, consultant, or healthcare provider.
High-risk industries like construction, manufacturing, or food service face unique challenges. Your independent agent knows which carriers specialize in these sectors and understand their particular exposures. They speak the language of these specialized underwriters and know how to present your business in the best possible light.
When standard markets say “no thanks,” independent agents can turn to surplus lines carriers. These specialized insurers create custom-custom policies for unusual risks that don’t fit the standard mold. They’re the problem-solvers of the insurance world.
As one grateful business owner shared: “Stefan helped me out with my Business Insurance needs. He was professional, respectful, knowledgeable about insurance, and he guided me through the entire process.”
Even if your business has a claims history that makes some carriers nervous, independent agents know which companies might still offer favorable terms. Their intimate knowledge of multiple carriers’ appetites and underwriting preferences allows them to match your business with the insurers most likely to welcome you with open arms and competitive rates.
Comparing Coverage & Pricing Across Multiple Insurers
One of the biggest advantages of working with independent business insurance agents is their ability to comparison shop on your behalf. While you focus on running your business, they’re busy finding you the best coverage at the most competitive rates.
Think about it—independent agents typically work with thirteen different property and casualty insurance companies. That’s thirteen different quotes they can potentially gather for you, all without you having to fill out thirteen different applications or spend hours on the phone explaining your business over and over again.
This market access allows your agent to be your personal comparison shopper. They’ll present multiple quotes side-by-side in a format that makes sense, highlighting important differences that might not be obvious when you’re just looking at premium costs. After all, the cheapest policy isn’t always the best if it leaves critical gaps in your protection.
“My commercial package insurance was reduced to 1/3 of what it was. My workers compensation insurance was reduced by 50%,” shared one business owner after working with an independent agent. These kinds of savings happen because independent agents know how to leverage competition between carriers.
Beyond just price comparisons, your agent will point out unique advantages certain carriers might offer. Maybe one insurance company provides exceptional risk management services for your industry. Perhaps another has a particularly smooth claims process or specialized endorsements that would benefit your specific business model.
Today’s independent agencies use sophisticated technology platforms that can generate real-time quotes from multiple carriers simultaneously. This technology makes the process faster and more efficient than ever before, saving you valuable time.
The best independent agents focus on finding adequate coverage first, then competitive pricing. They understand that saving a few hundred dollars on premiums isn’t worth it if you’re left exposed to a potential six-figure claim. Their goal is to find that sweet spot where comprehensive protection meets budget-friendly pricing.
At Florida All Risk Insurance, we pride ourselves on being those kinds of agents—the ones who shop thoroughly, explain clearly, and prioritize your business’s long-term security over quick sales.
Step-By-Step: Working With Independent Business Insurance Agents
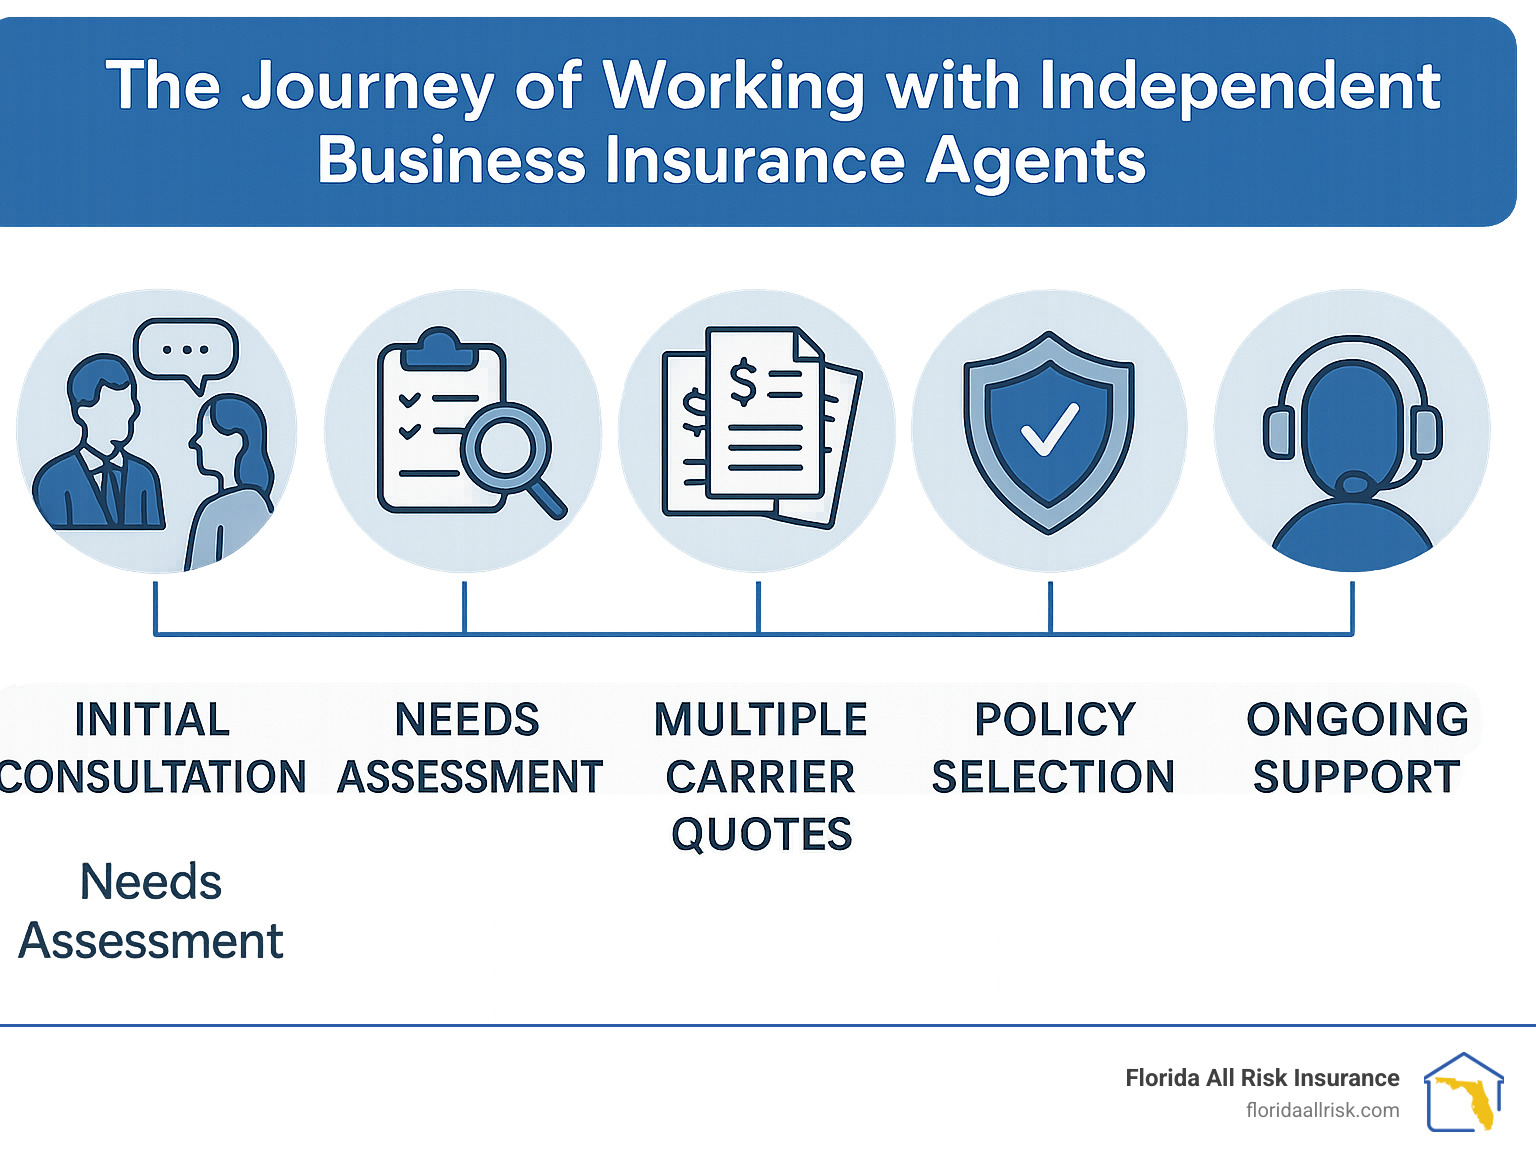
When you partner with an independent business insurance agent, you’re starting a relationship that follows a thoughtful, structured process. Let me walk you through what this journey typically looks like – from your first meeting to the ongoing support you’ll receive.
Initial Consultation (1-2 days)
Everything begins with a friendly chat where your agent gets to know your business. This first meeting is crucial – it’s where your agent learns about what makes your company tick, what keeps you up at night, and what you need to protect.
Don’t be shy during this meeting! This is your perfect opportunity to ask about the agent’s experience with businesses like yours, which insurance carriers they partner with, and how they’ll handle your account day-to-day. The best agents will be transparent and happy to share this information.
Risk Assessment (3-7 days)
After getting acquainted, your agent will roll up their sleeves and dive deeper into understanding your business risks. This typically takes about a week and might include:
A thorough review of your operations and locations, walking through your facilities to spot potential hazards, examining your current policies to find any coverage gaps, and identifying risks specific to your industry that you might not even be aware of.
As one business owner told us, “I was amazed at how many potential issues my agent identified that I’d never considered – it was like having a risk management consultant and insurance expert rolled into one.”
Market Submission (7-14 days)
Armed with a clear picture of your business, your independent business insurance agent creates detailed submissions for multiple insurance carriers. This is where their relationships with numerous insurers really shine. They’ll advocate for your business, explaining your risk management practices and why you’re a good candidate for competitive rates.
Proposal Presentation (14-21 days)
About two to three weeks into the process, your agent will present you with a comparison of the different options they’ve secured. This isn’t just a pile of quotes – a good agent will walk you through each proposal, explaining the coverage differences in plain English and highlighting why certain options might be better suited for your specific needs.
They’ll point out the trade-offs between premium costs and coverage breadth, helping you make an informed decision rather than just pushing the policy with the highest commission.
Policy Selection and Binding (21-30 days)
Once you’ve made your choice, your agent handles all the paperwork to bind your coverage – insurance-speak for “making it official.” You’ll receive your policy documents and clear instructions on payment options. The whole process, from first meeting to coverage in place, typically takes about a month.
Ongoing Service and Reviews (Throughout the policy term)
The relationship doesn’t end when the policy is issued. Your independent business insurance agent becomes a valuable business partner who’s there when you need them. They’ll check in regularly, especially when your business experiences changes like adding locations, purchasing new equipment, or hiring more employees.
The Process with Independent Business Insurance Agents
The beauty of working with independent agents is the personalized approach they bring to each step of the process.
Needs Analysis: Your agent will take time to truly understand your business. They’ll ask thoughtful questions about your operations, assets, employees, and potential risks. As one client put it: “They ask targeted questions to ensure all circumstances impacting your insurance needs are considered.” This isn’t a cookie-cutter approach – it’s insurance custom specifically to your business.
Risk Surveys: For larger businesses or those with unique exposures, your agent might arrange for detailed risk surveys. These on-site evaluations can identify potential hazards you might have overlooked. Better yet, implementing the recommendations can often improve safety while potentially lowering your premiums – a win-win.
Proposal Review: When presenting options from different carriers, your agent will help you understand what you’re actually getting for your money. They’ll translate insurance jargon into plain language and help you weigh the pros and cons of each option.
One business owner shared: “Stefan was professional, respectful, knowledgeable about insurance, and he guided me through the entire process.” This guidance is invaluable when making decisions about protecting your business.
Claims Support: When the unexpected happens, your agent becomes your advocate. They’ll help you document the loss properly, file the claim correctly, and communicate with adjusters. Having someone in your corner during stressful situations can make all the difference in how smoothly a claim is resolved.
Policy Management: Throughout your policy term, your agent provides ongoing support – issuing certificates of insurance when clients request them, making policy changes as your business evolves, and answering questions that arise. They’ll also conduct regular reviews to ensure your coverage keeps pace with your growing business.
How Independent Business Insurance Agents Are Paid
Understanding how your independent business insurance agent earns their living helps you better evaluate their recommendations and services.
Independent agents primarily earn income through commissions paid by the insurance companies they represent. For property and casualty insurance – like general liability, property, and auto policies – commissions typically range from 5% to 15% of your first-year premium. When you renew, the commission usually drops to around 2% to 5%.
For life and health insurance products, the commission structure looks different – often 60% to 80% of the first-year premium, with lower renewal commissions afterward.
Here’s the important part: these commissions are already built into the premium you pay. You’re not being charged extra for working with an agent versus going directly to the insurance company. The insurer pays these commissions directly to your agent from the premiums they collect.
Some independent agents also charge fees for certain specialized services, particularly for complex commercial accounts or detailed risk management consulting. Any such fees should be clearly explained upfront – if they’re not, that’s a red flag.
Commission rates can vary based on several factors: the type of insurance you’re buying, which carrier is providing it, the size and complexity of your business, and even regulations in your state.
Many carriers also offer their agencies “contingent commissions” or profit-sharing arrangements based on factors like growth, retention, and loss ratios. These incentives reward agents for bringing profitable business to the insurer.
As NerdWallet points out: “Fee-only planners don’t earn commissions, so they can give truly objective advice.” While this approach makes sense for certain types of insurance (particularly expensive permanent life policies), the traditional commission model works well for most business insurance needs – provided you’re working with a reputable agent who puts your interests first.
Choosing the Best Independent Agent for Your Business
Finding the right independent business insurance agent isn’t just about getting a policy—it’s about building a relationship with someone who’ll become a trusted advisor for your business. Let’s talk about what to look for when choosing an agent who’ll have your back.
First, consider their experience and expertise. You want someone who’s been around the block, especially in your industry. An agent who understands the specific challenges faced by, say, restaurants or manufacturing companies will know exactly which risks you face and which carriers offer the best coverage for those risks.
“When I found my agent, it was like night and day compared to my previous insurance experience,” one business owner told me. “She immediately understood the unique risks in my industry without me having to explain everything.”
The breadth of carrier relationships is another crucial factor. A strong independent business insurance agent should have partnerships with numerous insurance companies—both mainstream and specialty carriers. This diversity is what gives you access to more options and better pricing than you’d find with a captive agent.
Don’t overlook service standards when making your choice. Ask potential agents about their response times and whether you’ll have a dedicated account manager. The best agencies blend old-fashioned personal service with modern technology to make managing your policies as seamless as possible.
Professional credentials speak volumes about an agent’s commitment to their craft. Look for designations like CIC (Certified Insurance Counselor), CPCU (Chartered Property Casualty Underwriter), or AAI (Accredited Adviser in Insurance). These aren’t just fancy letters—they represent hundreds of hours of study and ongoing education.
Before making your final decision, ask for references from businesses similar to yours. There’s nothing like hearing from other business owners about their real-world experiences with an agent.
The way an agent handles claims can make or break your experience when you need them most. A good agent doesn’t just sell you a policy and disappear—they guide you through the claims process and advocate fiercely on your behalf when you suffer a loss.
Many quality independent agencies also offer risk management services beyond just placing your insurance. These value-added services can help identify potential problems before they happen, ultimately protecting your business and potentially lowering your premiums.
As one client shared about their experience: “Nicole was fantastic! She rescued us right before our closing and got us a great product, responding quickly and completing everything super quickly.”
For more insights about the advantages of working with an independent agency, check out Florida All Risk’s guide on working with independent agencies.
Red Flags and Questions to Ask
Not all independent business insurance agents are created equal. Here are some warning signs that should make you think twice before signing on the dotted line:
Be wary of an agent who claims to be independent but only mentions one or two carriers. True independence means access to numerous markets—that’s how you get the best coverage at the best price. If they’re only showing you quotes from a couple of companies, you’re not seeing the full picture.
Transparency about fees and commissions is essential. A reputable agent will be upfront about how they’re compensated. If they dance around these questions, consider it a red flag.
Pay attention to communication style during your initial interactions. If they’re slow to respond or vague when you’re still in the “courting” phase, imagine how frustrating it will be when you actually need them for a claim or policy change!
Watch out for agents who push coverage without clear explanations. A good agent educates you about different options and why they’re recommending specific coverages for your business. They should speak in plain English, not insurance jargon.
Industry knowledge is non-negotiable. If an agent doesn’t ask detailed questions about your operations or seems to be working from a generic checklist, they probably don’t have the specialized knowledge needed to properly protect your business.
When interviewing potential agents, here are some revealing questions to ask:
“How many carriers do you represent for businesses like mine?” This gives you a sense of their market access.
“What experience do you have with my industry?” Their answer will reveal whether they understand your specific risks.
“Walk me through how you handle claims.” Their response will tell you a lot about the support you can expect when you need it most.
“Beyond insurance placement, what other services do you provide?” This helps you understand the full value they bring to the table.
“How often will you review my coverage?” The best agents proactively review your policies as your business evolves.
Remember what one seasoned insurance professional told me: “Focus on adequate coverage over just the lowest premium.” A good agent prioritizes proper protection rather than simply offering the cheapest option.
Helpful Organizations & Networks
When searching for qualified independent business insurance agents, several professional organizations can serve as excellent resources. These groups not only support agents with education and resources but also maintain professional standards that benefit you as a client.
The Independent Insurance Agents & Brokers of America (IIABA)—affectionately known as the “Big I”—represents more than 25,000 independent agencies across the country. When an agent belongs to the IIABA, it signals their commitment to professionalism and continuing education. The organization provides its members with market access, educational resources, and advocacy support that ultimately benefits their clients.
Similarly, the Professional Insurance Agents (PIA) association supports independent agents who specialize in property and casualty insurance. PIA members can access continuing education and technical resources that help them stay current with industry developments and best practices.
The Big “I” Alliance offers special market access programs that can directly benefit your business. According to their materials, “The Blue program has no fees or volume commitments” and “agencies retain ownership of policy expirations.” This last point is particularly important—it means your relationship with your agent remains stable even if they change their carrier relationships.
Don’t overlook state-level insurance associations either. These groups provide local networking, education, and regulatory updates specifically relevant to your state’s insurance landscape. For perspective, Oregon alone has 192 independent insurance agencies, according to industry data.
When evaluating potential agents, ask about their involvement with these professional organizations. Active participation often indicates a genuine commitment to professional growth and staying on top of industry trends. These affiliations ensure your agent has access to continuing education that keeps them updated on the latest coverage options, emerging risks, and industry best practices.
“My agent’s involvement with the Big I means she’s always bringing fresh ideas to our annual reviews,” one business owner told me. “Last year, she identified a new cyber liability endorsement that saved us money while improving our coverage, all because she learned about it at an association conference.”
These professional networks also provide agents with problem-solving resources for complex insurance situations. If your business has unusual risks or needs specialized coverage, an agent with strong professional connections can tap into collective wisdom to find solutions that might not be immediately obvious.
Frequently Asked Questions about Independent Business Insurance Agents
What types of business insurance can an independent agent place?
When it comes to protecting your business, independent business insurance agents truly shine with their versatility. They can help you secure virtually any type of commercial coverage your business might need.
Most businesses start with fundamental protections like general liability insurance (which shields you from third-party injury claims) and commercial property coverage (protecting your buildings, equipment, and inventory). But that’s just the beginning of what these agents can offer.
Is your business vulnerable to interruptions? Your independent agent can arrange business interruption coverage to replace lost income if you’re temporarily forced to close after a covered loss. Do you have employees? They’ll help you steer workers’ compensation requirements in Florida.
For businesses with company vehicles, commercial auto insurance is essential, while professional service providers often need errors and omissions coverage to protect against claims of negligence. Cyber liability insurance has become increasingly important for businesses of all sizes.
Independent business insurance agents also excel at finding specialized coverages like employment practices liability (protecting against discrimination or harassment claims), directors and officers coverage (shielding your leadership team), and commercial umbrella policies that provide extra protection beyond your standard policy limits.
What makes independent agents particularly valuable is their ability to create customized insurance programs for specific industries, whether you’re a contractor, manufacturer, retailer, healthcare provider, or professional service firm.
How do independent agents assist with claims?
Filing an insurance claim can be one of the most stressful experiences for a business owner. This is where your independent business insurance agent truly becomes your advocate and ally.
When disaster strikes, your independent agent springs into action. They’ll help you report the claim promptly and correctly, ensuring you provide all the necessary details from the start. Many claims delays happen because of incomplete information, but your agent knows exactly what the insurance company needs.
Need to document your loss? Your agent will guide you through gathering the right evidence and paperwork. Not sure what’s covered? They’ll explain your policy provisions in plain English, not insurance jargon.
Perhaps most importantly, your independent agent serves as your buffer and translator with the insurance company. They speak both languages – yours and the insurer’s – ensuring clear communication throughout the process.
As one satisfied client shared: “Through accidents whether mine or not I’ve never had any problems and all of my questions through the years have been answered promptly and accurately.”
Your agent will keep tabs on your claim’s progress, following up with adjusters when things move too slowly. If disagreements arise about coverage or settlement amounts, they’ll leverage their carrier relationships to negotiate on your behalf.
This advocacy becomes especially valuable during complex business claims involving multiple coverage types or when calculating business interruption losses – areas where having an experienced professional in your corner can make a substantial difference in the outcome.
Are there situations where using an independent agent may not make sense?
While independent business insurance agents are the right choice for most businesses, I believe in complete transparency – there are a few scenarios where other options might be worth considering.
If you run a very simple business with minimal risks – perhaps a small home-based operation with no employees and few assets – direct-to-consumer insurance options might seem adequate. Similarly, if you’ve maintained a long, positive relationship with a specific carrier that offers competitive rates and all the coverage you need, you might not see immediate benefits from switching.
Very large corporations with complex global operations often work directly with specialized insurance brokers and risk management consultants rather than independent agents. These businesses typically have dedicated risk management departments that coordinate with multiple brokers.
Some business owners make insurance decisions based solely on finding the lowest premium. While online comparison tools might seem appealing for this approach, they often result in coverage gaps that can prove financially devastating when a claim occurs. As we like to say in the industry, “The most expensive insurance policy is the one that doesn’t cover your claim.”
Certain industries have association-sponsored insurance programs offering competitive rates for members. While these can sometimes be accessed directly, many business owners still value having an independent agent review these options alongside alternatives from the broader market.
Even in these scenarios, the objective advice, broader market perspective, and personalized service that independent business insurance agents provide typically outweigh any perceived advantages of going it alone. As one client put it: “You might think digital insurance will save you time or money, but independent agents are experts who protect your business with custom coverage.”
Conclusion
Navigating the complex world of business insurance can feel like trying to find your way through a maze blindfolded. That’s where independent business insurance agents come in – they’re like having a trusted guide with a map and flashlight.
Throughout this guide, we’ve seen why these agents handle about 80% of all commercial insurance in the United States. It’s no accident! Their ability to shop around and compare options across an average of thirteen different insurance companies means they can find that sweet spot where protection meets affordability for your specific business.
But the real value of working with an independent agent goes far beyond just getting you a good deal on day one. They become part of your business journey – conducting thorough risk assessments when you first meet, recommending coverage that actually makes sense for your operation, standing by your side during claims, and regularly reviewing your policies as your business grows and changes.
When you’re looking for the right independent agent, remember to consider their experience in your industry, which insurance carriers they work with, and their approach to customer service. Professional credentials like CIC or CPCU show they’re serious about their expertise, and don’t be shy about asking for references from businesses similar to yours.
At Florida All Risk Insurance, we take pride in our independence. From our home base in St. Petersburg, we serve businesses throughout Florida with personalized attention and access to numerous insurance carriers. This means we can find the right coverage at competitive rates whether you’re just starting out or you’ve been in business for decades.
We believe that every Florida business deserves insurance protection that fits like a glove – not too tight, not too loose, and definitely not one-size-fits-all. We’d love to show you the difference that working with an independent agency can make. Reach out today to discuss how we can help protect everything you’ve worked so hard to build.
For more details about commercial property coverage and other business insurance options, check out our commercial property coverage page.