

Homeowners insurance weston fl: Secure 2025
Protecting Your Most Valuable Investment in Weston
Finding the right homeowners insurance weston fl coverage is essential for protecting your most significant investment. Whether you’re a new homeowner or reviewing your current policy, understanding your options can save you money while ensuring comprehensive protection.
As a premier master-planned community in Broward County, Weston is known for its beautiful neighborhoods, excellent schools, and lush landscapes. This high quality of life is reflected in its property values, making the protection offered by a robust homeowners insurance policy not just a recommendation, but a necessity for financial security.
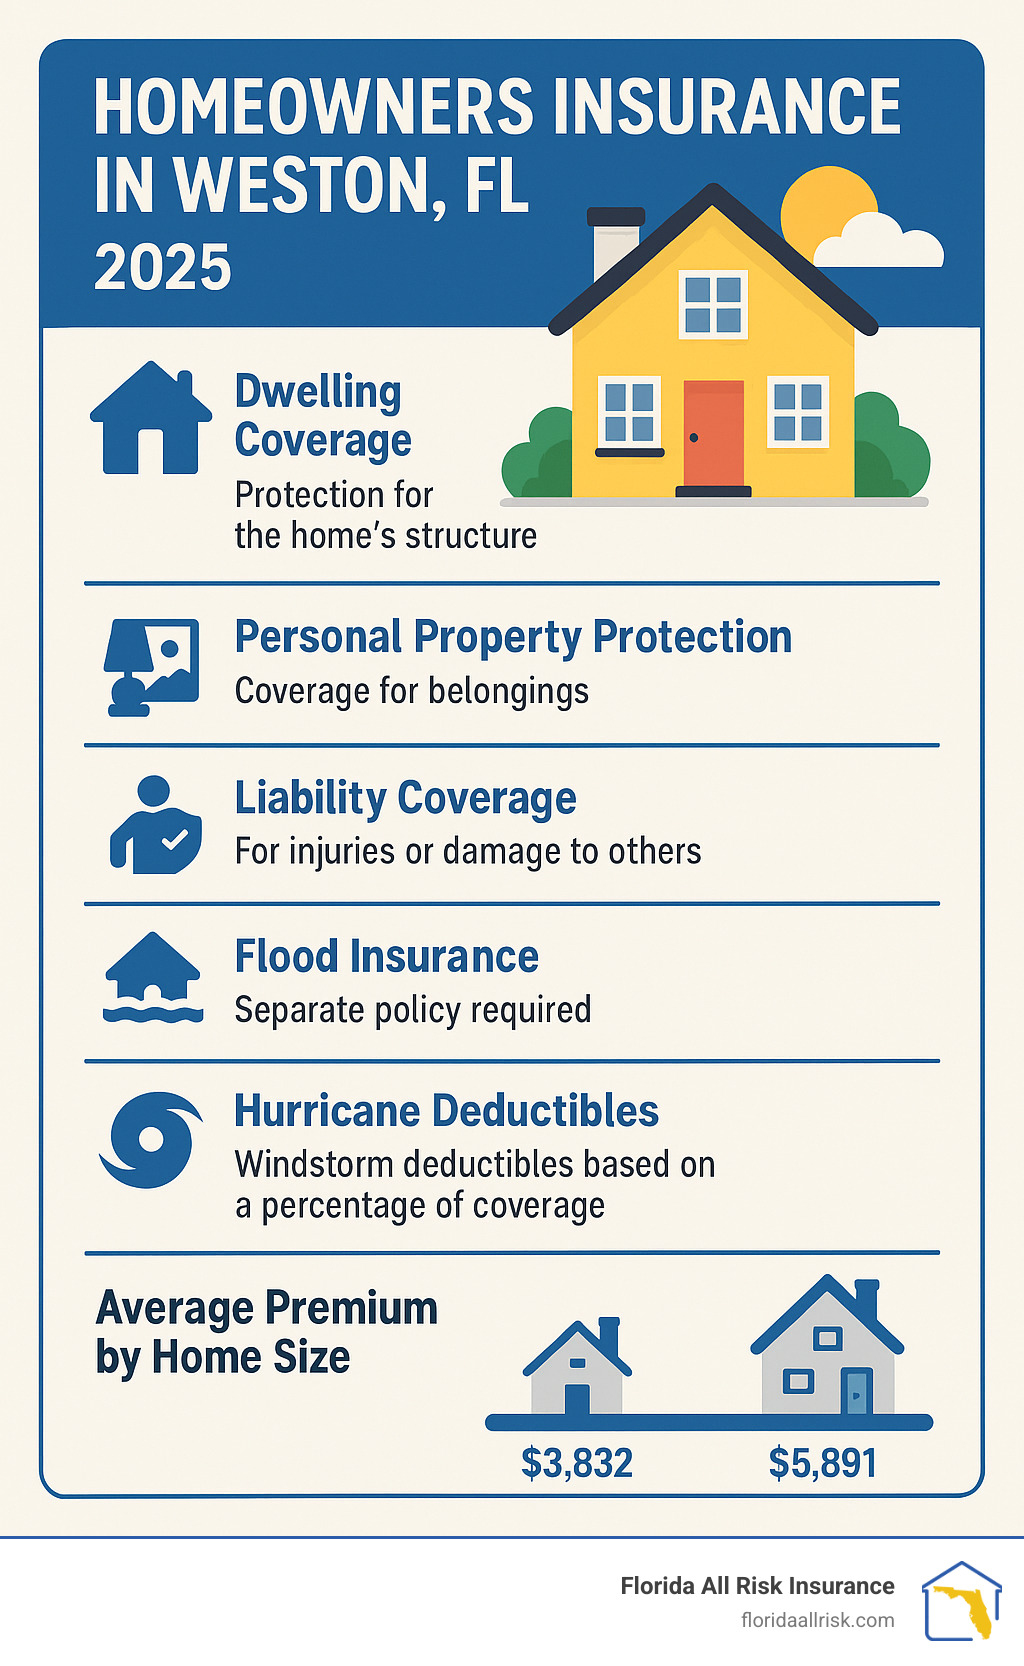
In Weston, the average annual premium is around $4,613 for homes valued at $444,283. However, this cost varies based on your home’s age, size, and location. For instance, homes over 2,500 square feet average $5,891 annually, while smaller homes average $3,832.
Key Coverage Areas to Consider:
- Dwelling protection for your home’s structure
- Personal property coverage for belongings
- Personal liability protection
- Additional living expenses if your home is uninhabitable
- Flood insurance (a separate policy, as standard policies exclude flood damage)
- Hurricane/windstorm coverage with percentage deductibles
Living in Weston means dealing with unique Florida risks like hurricanes and flooding. As Jason Miller, an insurance professional with over 20 years of Florida experience, I’ve helped thousands of homeowners steer the complex homeowners insurance weston fl market. My family’s combined 60+ years in Florida insurance gives Florida All Risk Insurance the expertise to find you the right coverage at competitive rates.
Basic homeowners insurance weston fl terms:
- homeowners insurance Florida
- florida homeowners insurance 2025
- another home insurance company leaving florida
Owning a home in Weston, FL, is a dream realized for many. This guide is designed to explain homeowners insurance, empowering you to protect your valuable asset from the unexpected. We’ll cover standard coverages, costs, and Florida-specific risks, ensuring you have the knowledge to make informed decisions.
Understanding Your Homeowners Insurance Policy in Weston
This section breaks down the essential components of a standard policy, helping you understand what’s protected. Knowing these details is the first step to ensuring you have the right coverage for your Weston home.
What a Standard Florida Homeowners Policy Covers
Your homeowners insurance weston fl policy is a safety net with multiple layers of protection. A standard Florida homeowners policy (typically an HO-3) includes the following:
-
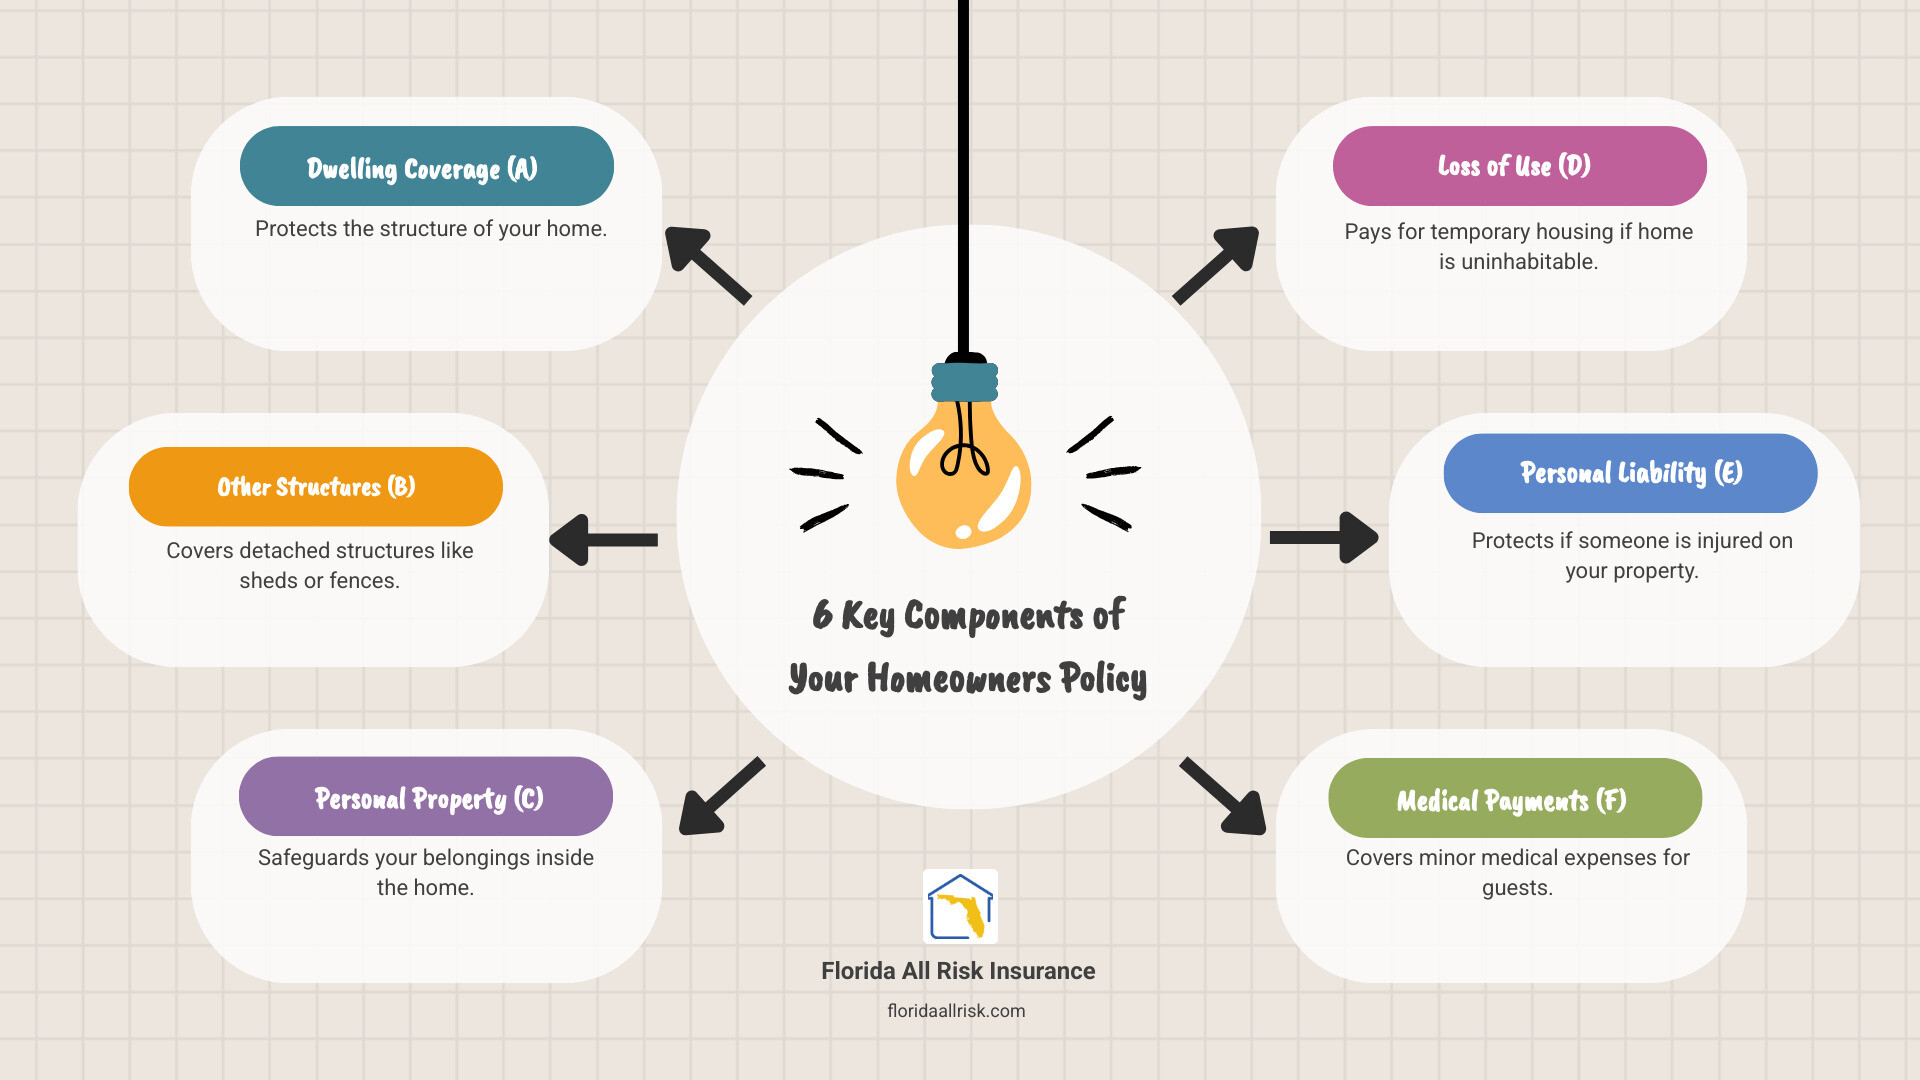
Dwelling Coverage (Coverage A): This is the heart of your policy, protecting the structure of your home, including the foundation, walls, roof, and built-in appliances. It pays for repairs or rebuilding after a covered event.
-
Other Structures (Coverage B): This extends protection to other buildings on your property not attached to the main house, such as a detached garage, shed, or fence. This is typically set at 10% of your dwelling coverage.
-
Personal Property (Coverage C): This protects your belongings—furniture, electronics, clothes, and more—if they are damaged, destroyed, or stolen. This coverage is often around 70% of your dwelling limit. For high-value items like jewelry or art, consider scheduled personal property coverage for broader protection.
-
Loss of Use (Coverage D): This becomes your lifeline if your home is temporarily uninhabitable due to a covered loss. It pays for additional living expenses like hotel bills and restaurant meals.
-
Personal Liability (Coverage E): This protects you financially if someone is injured on your property or you accidentally damage someone else’s belongings. It covers legal defense costs and settlements up to your policy limits.
-
Medical Payments to Others (Coverage F): This covers minor medical expenses for guests injured on your property, regardless of who is at fault, helping to resolve small incidents quickly.
For more details on Florida homeowners insurance products, visit Florida All Risk Insurance’s Homeowners Insurance page.
HO-3 vs. HO-5: Understanding Your Policy Type
While the HO-3 is the most common policy type in Florida, it’s beneficial to understand its counterpart, the HO-5. An HO-3 policy provides ‘open perils’ coverage for your dwelling (meaning it’s covered against all risks except those specifically excluded) but ‘named perils’ coverage for your personal property (meaning it’s only covered against risks explicitly listed in the policy, like fire, theft, and wind). In contrast, an HO-5 policy offers ‘open perils’ coverage for both your dwelling and your personal property. This provides broader protection for your belongings. While HO-5 policies typically come with a higher premium, they offer more comprehensive coverage and are often recommended for homeowners with high-value personal property. Discussing which policy type aligns best with your assets and risk tolerance is a critical conversation to have with your insurance agent.
Replacement Cost vs. Actual Cash Value: A Critical Choice
One of the most important decisions for your homeowners insurance weston fl policy is choosing how your property will be valued after a loss.
-
Replacement Cost (RC): This is the recommended option for most homeowners. It pays the full cost to replace your damaged items with new ones of similar kind and quality, without deducting for depreciation. If your five-year-old TV is destroyed, you get enough money to buy a new, comparable model.
-
Actual Cash Value (ACV): This pays the replacement cost minus depreciation (the decrease in value due to age and wear). For that same TV, you might only receive what it was worth at the time of the loss, which could be significantly less than the cost of a new one. ACV policies often have lower premiums but can leave you with a large out-of-pocket expense.
Understanding the difference between rebuilding costs and market value is also crucial. Your insurance should cover the cost to rebuild your home, which can be higher than its market value, especially with current labor and material prices.
| Item | Replacement Cost (RC) | Actual Cash Value (ACV) |
|---|---|---|
| 5-year-old TV | $800 | $300 |
| Roof after a storm | $15,000 | $7,000 |
Why Personal Liability Coverage is Non-Negotiable
Personal liability coverage is an essential shield that protects your financial assets. In a state like Florida, it is non-negotiable.
-
Guest Injuries: If a guest is injured on your property, from a slip on a wet deck to a trip on the stairs, this coverage handles the medical and potential legal costs.
-
Dog Bites: Most policies cover injuries caused by pets, but it’s important to verify coverage, as some insurers have breed restrictions.
-
Damage to Others’ Property: Protects you if you accidentally cause damage, such as a tree from your yard falling on a neighbor’s car.
-
Lawsuits & Asset Protection: This coverage pays for legal defense and settlements, creating a barrier between a claim and your personal assets like your savings and home.
Standard liability limits are typically $100,000 to $300,000, but we often recommend higher limits or an umbrella policy for greater peace of mind.
For more on insuring your home with pets, see Paws Policies: Navigating Homeowners Insurance with Dogs.
The Cost of Homeowners Insurance in Weston, FL
Premiums in Weston are influenced by a unique set of factors. Here, we’ll examine the average costs and explore the variables that insurers use to calculate your rate.
What is the Average Cost of Homeowners Insurance in Weston, FL?
Understanding what you might pay for homeowners insurance weston fl is key for budgeting. Based on recent data, Weston homeowners pay an average of $4,613 annually for a policy on a home valued around $444,283. This typically includes windstorm protection with a standard 2% deductible.
This is an average, and your actual premium will depend on your specific home and coverage needs. Here’s a general breakdown of average annual premiums in Weston by the amount of dwelling coverage needed:
- $200,000 to $299,000: $3,278
- $300,000 to $399,000: $3,932
- $400,000 to $499,000: $4,545
- $500,000 to $599,000: $5,384
- $600,000 to $699,000: $6,124
- $700,000 to $799,000: $7,038
The pattern is clear: the more it would cost to rebuild your home, the higher your premium will be.
Weston Premiums in Context
To put Weston’s average annual premium of $4,613 into perspective, it’s important to look at broader trends. The average cost of homeowners insurance in Florida as a whole is significantly higher than the national average, often cited as being three to four times more expensive. While Weston’s average is substantial, it reflects the high property values and the specific hurricane risk of South Florida. In contrast, the national average premium hovers around $1,500 to $2,000. This stark difference underscores why Florida homeowners, and particularly those in high-value areas like Weston, must be proactive in seeking discounts and working with knowledgeable agents to manage these high costs effectively.
Key Factors That Determine Your Weston Insurance Rates
Insurers assess numerous factors to determine the risk associated with your home and calculate your homeowners insurance weston fl premium.
-
Home’s Location: Your specific ZIP code (33326, 33327, 33331, or 33332) matters. Insurers consider proximity to the coast, local crime rates, and distance to the nearest fire station.
-
Flood Zones: While standard policies exclude flood damage, being in a high-risk flood zone indicates a higher overall weather risk, which can influence your premium.
-
Age and Construction: Newer homes built to modern codes (especially after 2002) often receive lower rates. Older homes may have outdated systems that pose a higher risk.
-
Roof’s Age and Condition: A newer roof, particularly one with wind-resistant features, is your home’s primary defense and can significantly lower your premium.
-
Claims History: A history of frequent claims, by you or previous owners, can lead to higher rates.
-
Credit Score: In Florida, insurers may use a credit-based insurance score to help determine rates, as studies show a correlation between credit management and claims frequency.
-
Protective Devices: You can earn discounts for having security systems, smoke detectors, and other safety features.
For more insights on Florida’s evolving insurance landscape, check out our analysis: Florida Homeowners Insurance 2025.
How Your Home’s Age and Size Impact Your Premium
Your home’s age and size are major factors in your homeowners insurance weston fl costs, as they directly relate to rebuilding expenses.
-
Older vs. Newer Homes: Older homes often have aging electrical and plumbing systems, increasing the risk of fire or water damage. Newer homes, built to stricter codes after Hurricane Andrew, are more resilient and cheaper to insure.
-
Size Matters: Larger homes cost more to rebuild, contain more personal property, and represent a greater financial risk to insurers. This is reflected in the premium.
In Weston, the data shows a clear size impact: homes greater than 2,500 square feet have average premiums of $5,891 annually, while homes under 2,500 square feet average $3,832 per year. This difference of over $2,000 highlights how significantly size affects your insurance costs.
Navigating Florida-Specific Risks: Floods, Hurricanes, and Liability
Living in South Florida requires preparing for its unique environmental challenges. Your standard homeowners insurance weston fl policy has critical gaps, particularly for flood and hurricane damage, that must be addressed for complete protection.
Do I Need Flood Insurance in Weston?
The short answer is yes. Flood insurance is essential for any Florida homeowner.
Crucially, flood damage is excluded from all standard homeowners insurance policies. This policy will cover wind damage from a hurricane, but it will not cover damage from storm surge or rising water. This is a detail many homeowners find too late.

Flood damage is defined as water covering normally dry land, affecting two or more properties. This can come from storm surge, overflowing rivers, or torrential rainfall. Weston’s proximity to the Everglades makes it susceptible to water accumulation.
While FEMA flood maps designate official risk zones, and lenders require flood insurance in high-risk areas, all homeowners should consider it. A significant percentage of flood claims occur in low-to-moderate risk zones.
You must purchase a separate flood policy. This can be done through the government’s National Flood Insurance Program (NFIP) or through a growing number of private flood insurance carriers. The NFIP offers standardized coverage with maximum limits of $250,000 for the dwelling and $100,000 for personal property, and it typically has a 30-day waiting period before coverage takes effect. Private flood insurance, on the other hand, can offer much higher coverage limits, may include coverage for additional living expenses (which the NFIP does not), and often has shorter waiting periods (e.g., 10-14 days). An independent agent can help you compare quotes from both the NFIP and private markets to find the best solution for your property’s value and your needs.
For more information, visit the National Flood Insurance Program{:target=”_blank”} website.
Understanding Hurricane Deductibles
Your homeowners insurance weston fl policy includes coverage for wind damage, but it comes with a special hurricane deductible.
-
Percentage-Based Deductible: Unlike your standard flat-dollar deductible, the hurricane deductible is a percentage of your dwelling coverage, typically 2% or 5%. For a home insured for $400,000 with a 2% deductible, you would be responsible for the first $8,000 of wind damage from a named storm.
-
Named Storm Trigger: This deductible only applies to damage caused by a storm officially named by the National Hurricane Center. Other wind events, like tornadoes, are subject to your regular policy deductible.
-
Annual Application: It’s also critical to understand that in Florida, the hurricane deductible is applied annually. This means if you are unfortunate enough to be hit by more than one named storm in a single hurricane season, you only have to pay the deductible once. After you’ve met it for the first storm, any subsequent wind damage from other named storms in that same year will be covered subject to your standard, all-peril deductible, which is usually a much lower flat dollar amount.
-
Wind Mitigation Savings: You can lower your windstorm premium by installing wind mitigation features. A certified inspection documenting features like hurricane shutters, a reinforced garage door, and a securely attached roof can lead to significant discounts. These savings often quickly repay the cost of the inspection.
I always recommend that my clients learn more about protective measures by visiting resources like the Insurance Institute for Business & Home Safety{:target=”_blank”}.
What is Umbrella Insurance and Should I Consider It?
Umbrella insurance is an extra layer of liability protection that sits on top of your existing homeowners and auto policies. For many Weston homeowners, it’s a smart investment.
-
Extends Liability Limits: If a serious accident occurs on your property and the legal judgment exceeds your standard liability limit (e.g., $300,000), your umbrella policy covers the excess amount, protecting your assets.
-
Broader Coverage: It can also cover claims not included in standard policies, such as libel, slander, and false arrest.
-
Affordable Protection: Umbrella policies are sold in increments of $1 million. The first million dollars of coverage is often very affordable, costing just a few hundred dollars per year.
For homeowners with significant assets—home equity, savings, investments—umbrella insurance provides critical protection against a catastrophic lawsuit.
For more detailed information, see our comprehensive guide: Homeowners Insurance in Florida.
How to Secure the Best Homeowners Insurance Weston FL
Finding the right policy at the right price requires a strategic approach. These tips will empower you to find the best value for your needs.
Actionable Ways to Lower Your Insurance Premiums
Saving money on homeowners insurance weston fl is about being a smart, low-risk policyholder, not cutting essential coverage.
- Increase Your Deductible: Choosing a higher deductible (e.g., $2,500 instead of $1,000) can lower your premium. Ensure you can comfortably pay this amount out-of-pocket.
- Bundle Policies: Combining your home and auto insurance with the same carrier often results in a multi-policy discount of 10-20%.
- Install Protective Devices: Monitored security systems, smoke detectors, and other safety features can earn you discounts.
- Improve Your Credit Score: In Florida, insurers may use a credit-based insurance score to determine rates. Better credit can lead to lower premiums.
- Get a Wind Mitigation Inspection: This is one of the most effective ways to save in Florida. Documenting wind-resistant features like hurricane shutters and a strong roof-to-wall connection can lead to substantial discounts.
- Maintain a Clean Claims History: Think twice before filing small claims. A history of frequent claims can increase your rates.
How to Get a Homeowners Insurance Weston FL Quote
Getting an accurate homeowners insurance weston fl quote requires providing detailed information and working with the right professional.
-
Information Needed: Be prepared to provide your home’s address, year built, square footage, construction type, and roof details (age and material). Your personal contact information and claims history will also be needed.
-
Work with an Independent Agent: An independent agent from a firm like Florida All Risk Insurance works with multiple carriers. We shop the market on your behalf, comparing prices, coverage, and service reputations to find the best fit for you.
-
Compare Coverage, Not Just Price: The cheapest quote isn’t always the best. It might have a high deductible or low limits that leave you underinsured. We help you compare the details to ensure you’re getting true value.
For a step-by-step guide on this process, see our comprehensive resource: Find the Best Homeowners Insurance in Florida 2025.
The Importance of a Home Inventory
A detailed home inventory is one of the most valuable things you can do to prepare for a potential claim. It provides proof of ownership and simplifies the claims process during a stressful time.
-
Document Everything: Go room by room and list your belongings, including furniture, electronics, clothing, and appliances. Don’t forget items in closets and the garage.
-
Use Photos and Videos: A visual record is powerful proof. Walk through your home with a smartphone, narrating what you see and capturing model or serial numbers on valuable items.
-
Keep Receipts: Store digital copies of receipts for major purchases in the cloud.
-
Store it Safely Off-Site: A home inventory is useless if it’s destroyed in the same event as your home. Use a cloud service or email a copy to yourself or a relative.
-
Expedite Your Claim: A complete inventory allows you to provide your insurer with a detailed list of lost items, leading to a faster, more accurate settlement.
Start your inventory with the Insurance Information Institute’s free tool{:target=”_blank”}. The time you invest now can save you significant trouble later.
Frequently Asked Questions About Weston Home Insurance
Here are quick answers to some of the most common questions homeowners have when navigating the insurance landscape in Weston.
Is homeowners insurance mandatory in Weston, FL?
No, the state of Florida does not legally require you to have homeowners insurance. However, if you have a mortgage, your lender will almost certainly require you to maintain a policy to protect their financial interest in the property. Even if you own your home outright, it is highly risky to go without insurance, as your home is likely your most valuable asset.
What is the difference between a captive agent and an independent agent?
A captive agent works for a single insurance company and can only offer that company’s products. An independent agent, like those at Florida All Risk Insurance, represents multiple insurance carriers. This allows us to shop the market on your behalf, compare a wide range of policies and prices, and find the coverage that best fits your specific needs. Our loyalty is to you, the client, not a single insurance company.
What should I do if my insurance company goes into liquidation?
While unsettling, Florida has a system to protect policyholders if an insurer becomes insolvent. The Florida Insurance Guaranty Association (FIGA) steps in to handle covered claims up to specific legal limits. If your insurer is liquidated, you must act quickly to secure new coverage, as your old policy will be canceled, typically within 30 days. An independent agent can be invaluable in this situation, helping you promptly find a new policy with a stable carrier to ensure you don’t have a lapse in coverage.
What is a 4-point inspection and why might I need one?
A 4-point inspection is a specific type of evaluation that insurance companies often require for older homes (typically those over 30 years old) before they will issue or renew a policy. It focuses on four key systems of the home: the Roof, Electrical, Plumbing, and HVAC (Heating, Ventilation, and Air Conditioning). The purpose is for the insurer to verify that these major systems are in good working condition and don’t pose an undue risk. If the inspection reveals issues, such as an outdated electrical panel or a roof near the end of its lifespan, you may be required to make repairs before you can obtain coverage.
Your Partner in Protecting Your Weston Home
Choosing the right homeowners insurance is a crucial decision for protecting your family and your most significant asset. By understanding your policy’s components, the factors that influence cost, and the specific risks associated with living in Weston, you can secure coverage that provides true peace of mind. An independent insurance agency like Florida All Risk Insurance can be an invaluable partner in this process, navigating the complex market to find a policy that is perfectly custom to your needs and budget.
Ready to protect your Weston home?
For a comprehensive review of your current policy or to explore the best options for your Weston home, get a personalized Florida Homeowners Insurance quote today.
Contact Us
If you’d like personalized guidance or have questions about insuring your Weston home, reach out. A licensed Florida All Risk Insurance advisor will respond promptly.
Florida All Risk Insurance
7901 4th St N, Suite 300, Saint Petersburg, FL 33702
Phone: (727) 474-9999
Email: [email protected]

