

Understanding Homeowners Insurance in Englewood, FL: A Comprehensive Guide
If you’re looking for homeowners insurance Englewood FL, here’s what you need to know:
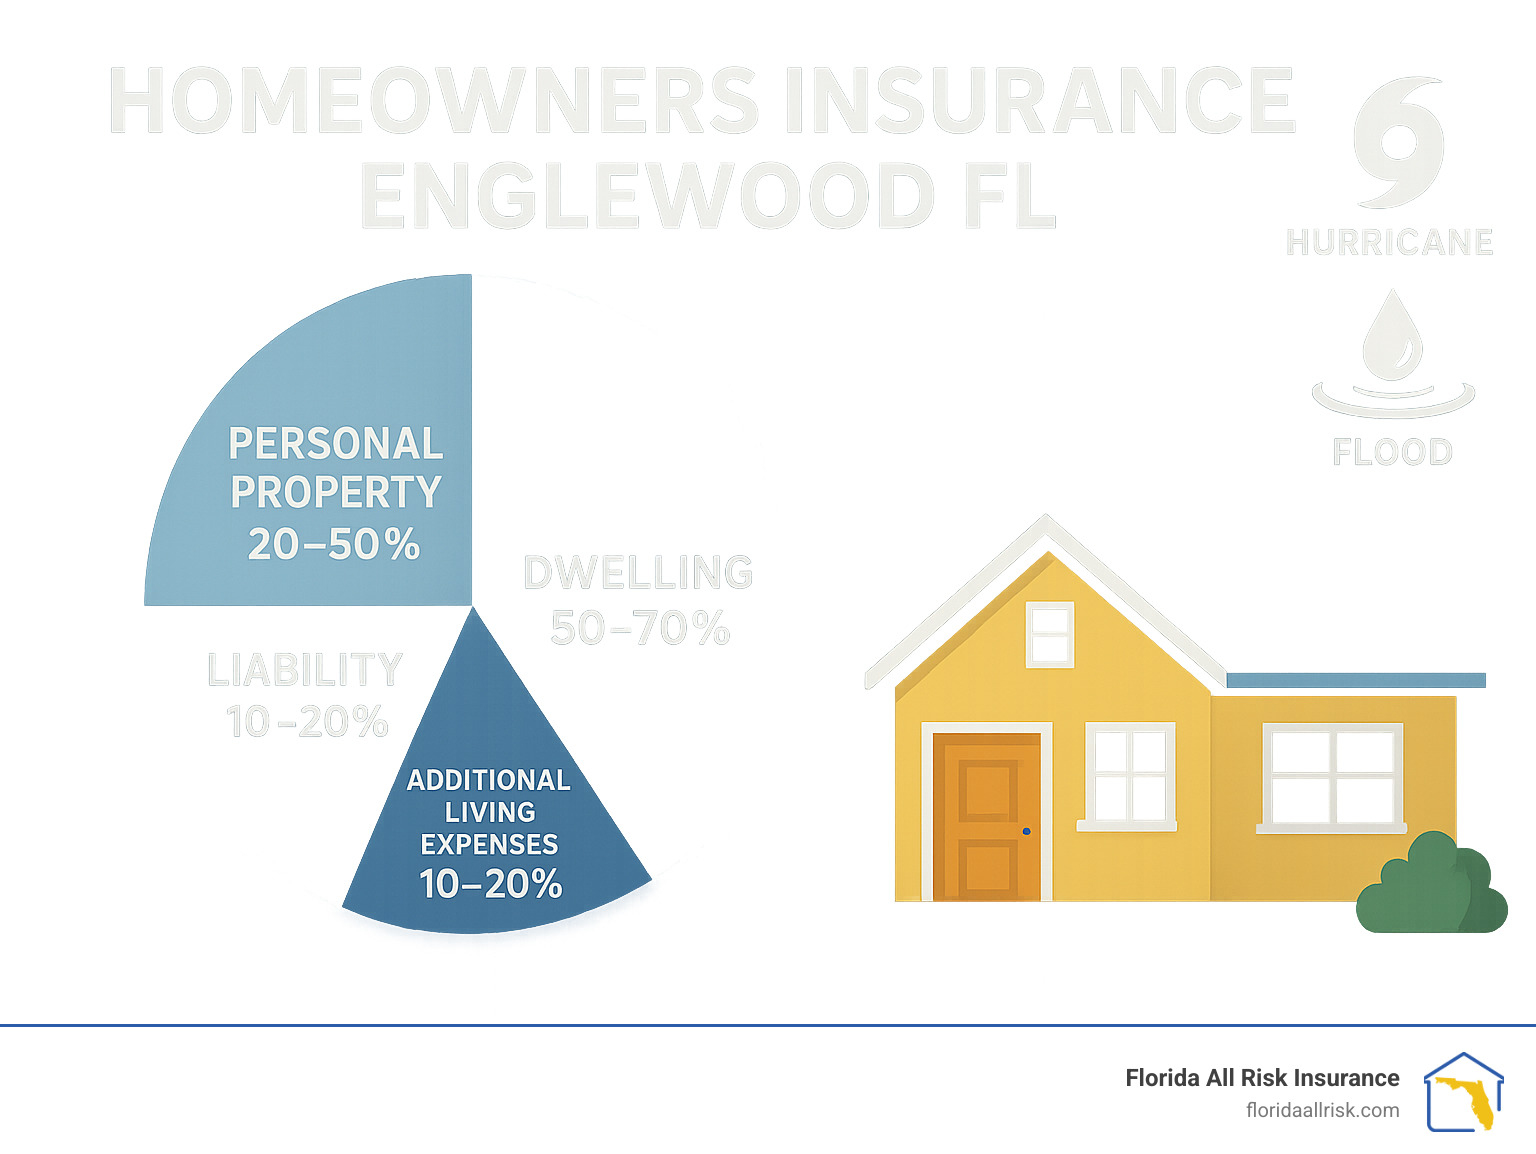
- Standard Coverage: Most policies cover dwelling structure, personal property, liability, and additional living expenses
- Average Cost: $3,000-$5,000 annually for typical Englewood homes (varies by location, home value, and construction)
- Required Coverage: Not mandatory by state law but required by mortgage lenders
- Hurricane/Flood Protection: Standard policies DO NOT include flood coverage; separate policies needed
- Local Considerations: Proximity to coast, flood zone, roof age, and wind mitigation features significantly impact rates
Owning a home in Englewood, Florida means enjoying paradise-like weather, beautiful beaches, and a relaxed coastal lifestyle. However, this slice of paradise comes with unique risks that require specialized protection. Homeowners insurance Englewood FL policies must address challenges that many other parts of the country don’t face – from hurricane exposure to flood risks and everything in between.
The insurance landscape in Florida has changed dramatically in recent years, with many carriers leaving the state or significantly increasing premiums. For Englewood homeowners, this means navigating a complex market to find adequate, affordable coverage that protects your most valuable asset.
I’m Jason Miller, a second-generation insurance professional with over 20 years of experience helping thousands of Florida homeowners find the right protection, including specialized homeowners insurance Englewood FL solutions for the unique coastal risks in our community.
Homeowners insurance englewood fl terms explained:
– another home insurance company leaving florida
– best homeowners insurance in florida 2025
– homeowners insurance in pinellas county florida
Why Englewood Homes Need Special Protection
Englewood’s beautiful coastal location is both its greatest asset and its biggest vulnerability. Located on Florida’s Gulf Coast, Englewood properties face unique exposures that require specialized insurance considerations.
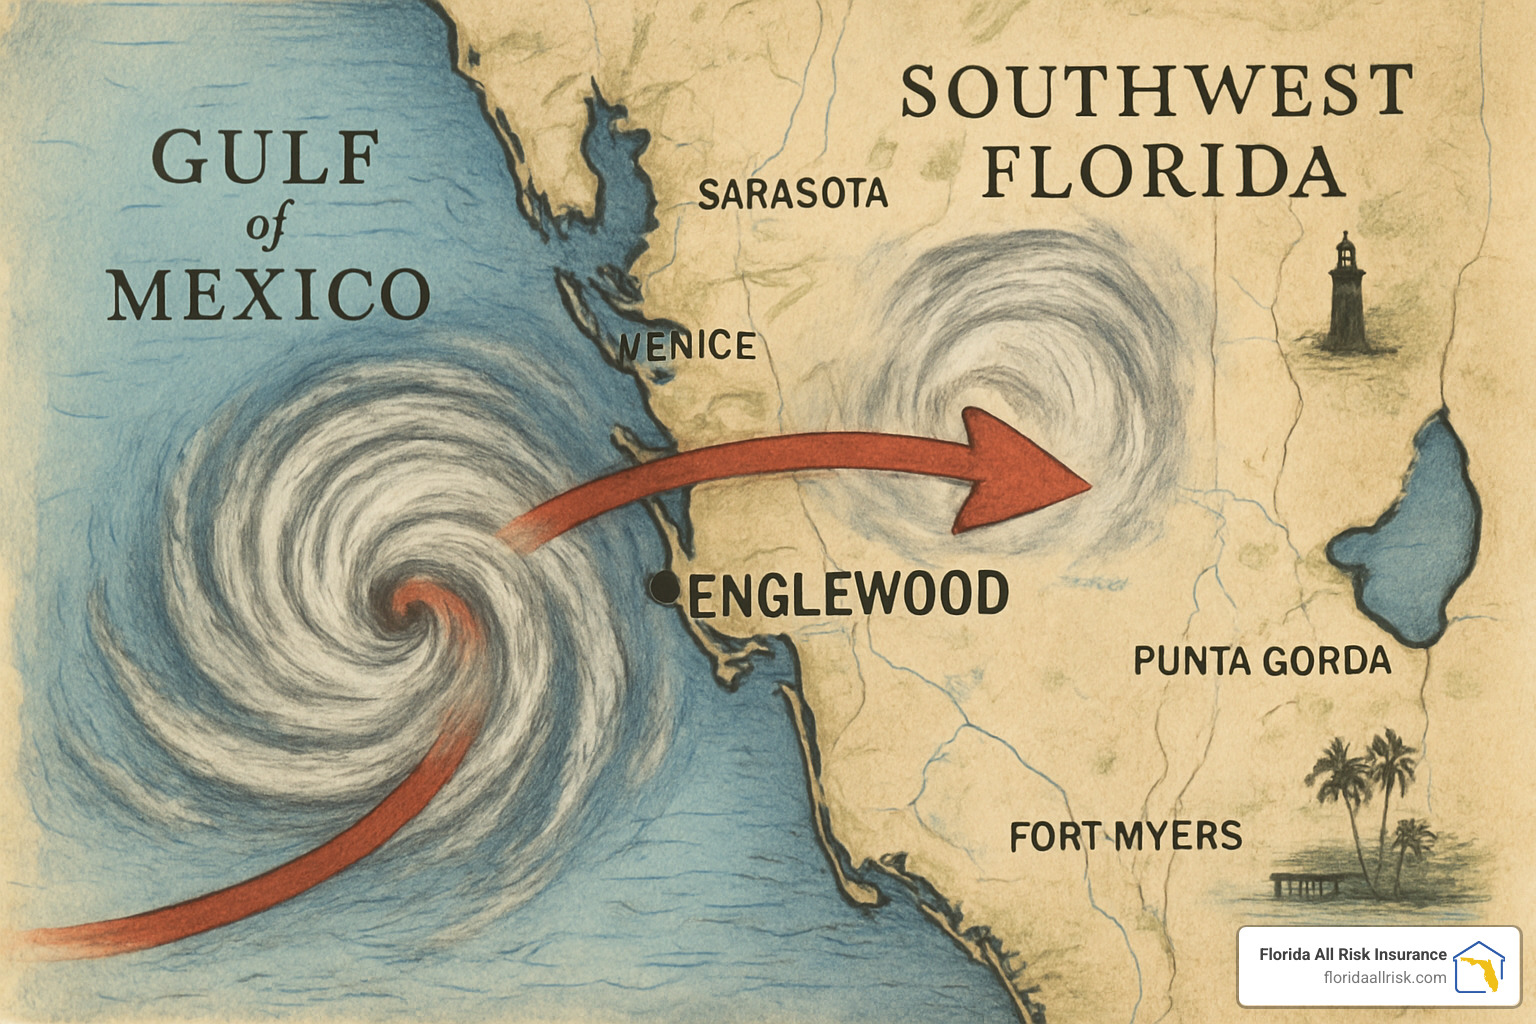
Living in paradise comes with its challenges. As a longtime Englewood resident myself, I’ve seen how our stunning beaches and waterfront views come with weather-related risks that folks in other states simply don’t face. When it comes to homeowners insurance Englewood FL, standard coverage designed for homes in Michigan or Ohio just won’t cut it here.
Our community sits in a particularly vulnerable position for tropical systems coming off the Gulf. During hurricane season (which seems to get longer every year!), we face the very real possibility of powerful storms bringing devastating winds that can exceed 100 mph. These storms don’t just bring wind – they’re package deals that include storm surge and rainfall measured in feet, not inches.
Flood risk is another major concern for Englewood homeowners. According to FEMA flood maps, significant portions of our community lie in designated flood zones. What surprises many new residents is learning that their standard homeowners insurance Englewood FL policy explicitly excludes flood damage – a separate policy is absolutely essential here.
Florida’s unofficial title as the “lightning capital of the United States” isn’t just talk – our afternoon thunderstorms bring spectacular (and dangerous) lightning displays that can damage electrical systems, appliances, and even cause house fires. And while Englewood doesn’t see as many sinkholes as central Florida, they remain a potential risk that may require additional coverage consideration.
For those lucky enough to live closer to our beautiful shoreline, coastal erosion represents a gradual but persistent threat that can undermine foundations and structures over time.
The Most Common Risks for Englewood Owners
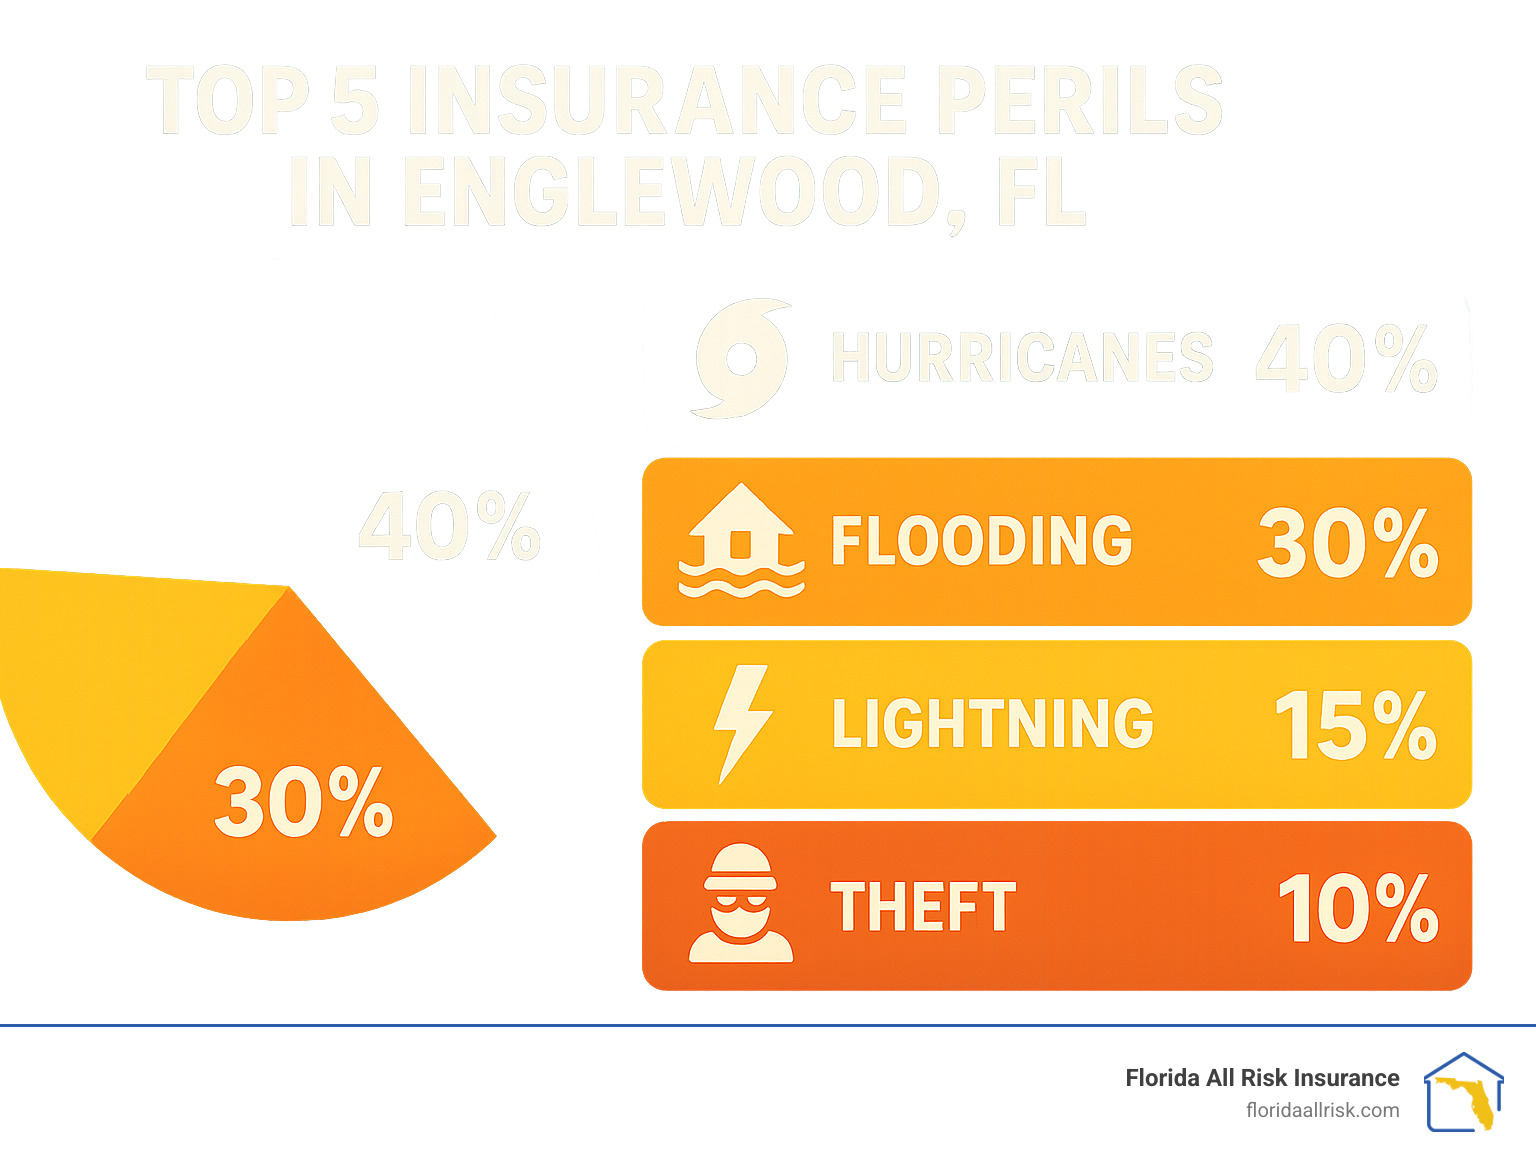
When we analyze claims data for homeowners insurance Englewood FL policies, several clear patterns emerge that highlight our unique local risks.
Storm surge tops the list of concerns for coastal properties. During hurricanes and strong tropical systems, the shallow waters of the Gulf can be pushed miles inland, causing devastating flooding even in areas that don’t typically flood during normal rain events. I’ve seen storm surge reach several feet high, turning streets into rivers and causing catastrophic damage to homes near the coast.
Even if you live away from the immediate shoreline, inland flooding remains a serious threat. Englewood’s relatively flat topography means heavy rainfall can quickly overwhelm drainage systems, particularly in low-lying areas or properties near canals, ponds, or other water features. Just a few inches of water inside your home can cause tens of thousands in damage.
During strong storms, wind-borne debris becomes a major hazard. Hurricane-force winds can turn patio furniture, tree limbs, and construction materials into dangerous projectiles. These airborne objects can shatter windows, damage doors, puncture roofs, and tear away siding – creating entry points for water and causing even more extensive damage.
Florida’s naturally humid climate creates the perfect conditions for mold growth following any water intrusion. After storm damage, mold can begin forming within 24-48 hours if not properly addressed. What starts as a small water stain can quickly become a major health hazard and expensive remediation project.
Understanding these unique local risks is the first step toward creating a truly comprehensive homeowners insurance Englewood FL plan that protects your most valuable asset. At Florida All Risk Insurance, we’ve helped thousands of Englewood homeowners find the right coverage combinations to address these specific regional challenges.
Homeowners Insurance Englewood FL: Core Coverages Explained
A standard homeowners insurance Englewood FL policy typically includes several core coverages, though the specifics can vary by carrier and policy type. Here’s what you should expect from a comprehensive policy:
Dwelling Coverage: This protects the physical structure of your home—the walls, roof, foundation, and attached structures like a garage. For Englewood homes, we recommend insuring for 100% of the replacement cost, which may be significantly higher than market value due to construction costs and building code requirements.
Other Structures Coverage: This covers detached structures on your property such as fences, sheds, detached garages, or pool enclosures. Typically, this is set at 10% of your dwelling coverage but can be increased if needed.
Personal Property Coverage: This protects your belongings inside the home, including furniture, clothing, electronics, and appliances. Standard coverage is usually 50-70% of your dwelling coverage. High-value items like jewelry or art may need additional scheduled coverage.
Liability Protection: This covers legal expenses and damages if someone is injured on your property or if you accidentally damage someone else’s property. Most policies start at $100,000, but we often recommend higher limits of $300,000 or more for Englewood homeowners.
Loss of Use/Additional Living Expenses: If your home becomes uninhabitable due to a covered loss, this helps pay for temporary housing, restaurant meals, and other extra costs. This is particularly important in hurricane-prone areas like Englewood, where repairs can take months.
Medical Payments: This covers smaller medical bills for guests injured on your property, regardless of fault. Typical coverage ranges from $1,000 to $5,000.
Ordinance & Law Coverage: This helps cover the increased costs of rebuilding to current building codes, which is critical in Florida where codes have strengthened significantly over the years. Standard policies may include 10%, but we often recommend increasing this to 25-50% for older Englewood homes.
Water Backup Coverage: This protects against damage from backed-up sewers or drains, which is not covered under standard policies or flood insurance.
Mold Endorsement: Given Florida’s humid climate, additional mold coverage beyond the standard limited amount can be valuable for Englewood homeowners.
Standard Policies vs. Specialty Options in Homeowners Insurance Englewood FL
When shopping for homeowners insurance Englewood FL, you’ll encounter several policy types, each designed for specific property types and coverage needs:
HO3 Policies (Special Form): This is the most common policy type for single-family homes in Englewood. It covers the home on an “open perils” basis (all risks except those specifically excluded) and personal property on a “named perils” basis (only specific listed risks).
HO5 Policies (Comprehensive Form): These premium policies offer the broadest coverage, with both dwelling and personal property covered on an “open perils” basis. They typically include higher limits and fewer exclusions, making them ideal for high-value Englewood homes.
HO6 Policies (Condo Form): Designed specifically for condominium owners, these policies cover personal property, liability, and improvements to the unit. The condo association’s master policy typically covers the building structure.
DP1-DP3 Policies (Dwelling Fire): These policies are designed for rental properties, vacation homes, or older homes that don’t qualify for standard homeowners insurance. DP1 offers basic coverage, while DP3 provides more comprehensive protection.
Wind-Only Policies: In some cases, Englewood homeowners may need to obtain separate wind coverage through Citizens Property Insurance Corporation or other specialized carriers if wind damage is excluded from their standard policy.
Does Homeowners Insurance Englewood FL Cover Floods or Hurricanes?
This is perhaps the most critical question for Englewood homeowners, and the answer requires careful attention:
Flood Coverage: Standard homeowners insurance Englewood FL policies DO NOT cover flood damage, regardless of the cause. This includes storm surge from hurricanes, heavy rainfall, or overflowing bodies of water. Flood insurance must be purchased separately, typically through the National Flood Insurance Program (NFIP) or private flood insurers.
Given Englewood’s coastal location, flood insurance is essential for most homeowners, even those not in designated high-risk flood zones. According to insurance industry data, about 40% of flood claims come from properties outside high-risk zones.
Hurricane Coverage: Most homeowners policies in Englewood do cover wind damage from hurricanes, but with important caveats:
-
Hurricane Deductibles: Florida policies typically include a separate hurricane deductible, usually 2-10% of your dwelling coverage. This means if your home is insured for $300,000, your hurricane deductible could be $6,000-$30,000, much higher than your standard deductible.
-
Wind Exclusions: Some policies in high-risk coastal areas may exclude wind damage entirely, requiring a separate wind policy.
For comprehensive protection in Englewood, most homeowners need both a standard homeowners policy and a separate flood policy. For more information about flood insurance options, visit our Flood Insurance page or consult official FEMA flood resources.
What Determines Your Premium—and How to Pay Less
Ever wonder why your neighbor’s homeowners insurance Englewood FL premium might be lower than yours? Understanding what drives your insurance costs can help you make smarter decisions about coverage—and potentially save hundreds or even thousands each year.
Your home’s construction type plays a huge role in what you’ll pay. Here in Englewood, concrete block homes typically enjoy better rates than wood frame structures. It makes sense—those CBS (Concrete Block Structure) homes simply stand up better to our hurricane winds.
That roof over your head? It matters more than you might think. Newer roofs (especially those under 10 years old) can dramatically reduce your premium. If you’re considering a replacement, metal roofs often qualify for significant discounts while providing excellent storm protection.
Living the beachfront dream comes with a price tag. Your distance to the coast directly impacts your rates, with Gulf-front properties facing the highest premiums. Even moving just a few miles inland can substantially lower your insurance costs.
Your claims history follows you like a shadow. Previous water damage claims are particularly concerning to insurers—both claims you’ve filed personally and those filed on your property before you owned it. That leaky roof claim from three years ago? Insurance companies remember.
While Florida has some restrictions on using credit information, many insurers still consider your credit-based insurance score when calculating rates. Maintaining healthy credit can benefit more than just your mortgage rate.
One of the simplest ways to lower your premium is adjusting your deductible choice. Opting for a $2,500 deductible instead of $1,000 might save you 15-20% on your annual premium. Just make sure you have that extra cash available if you need to file a claim!
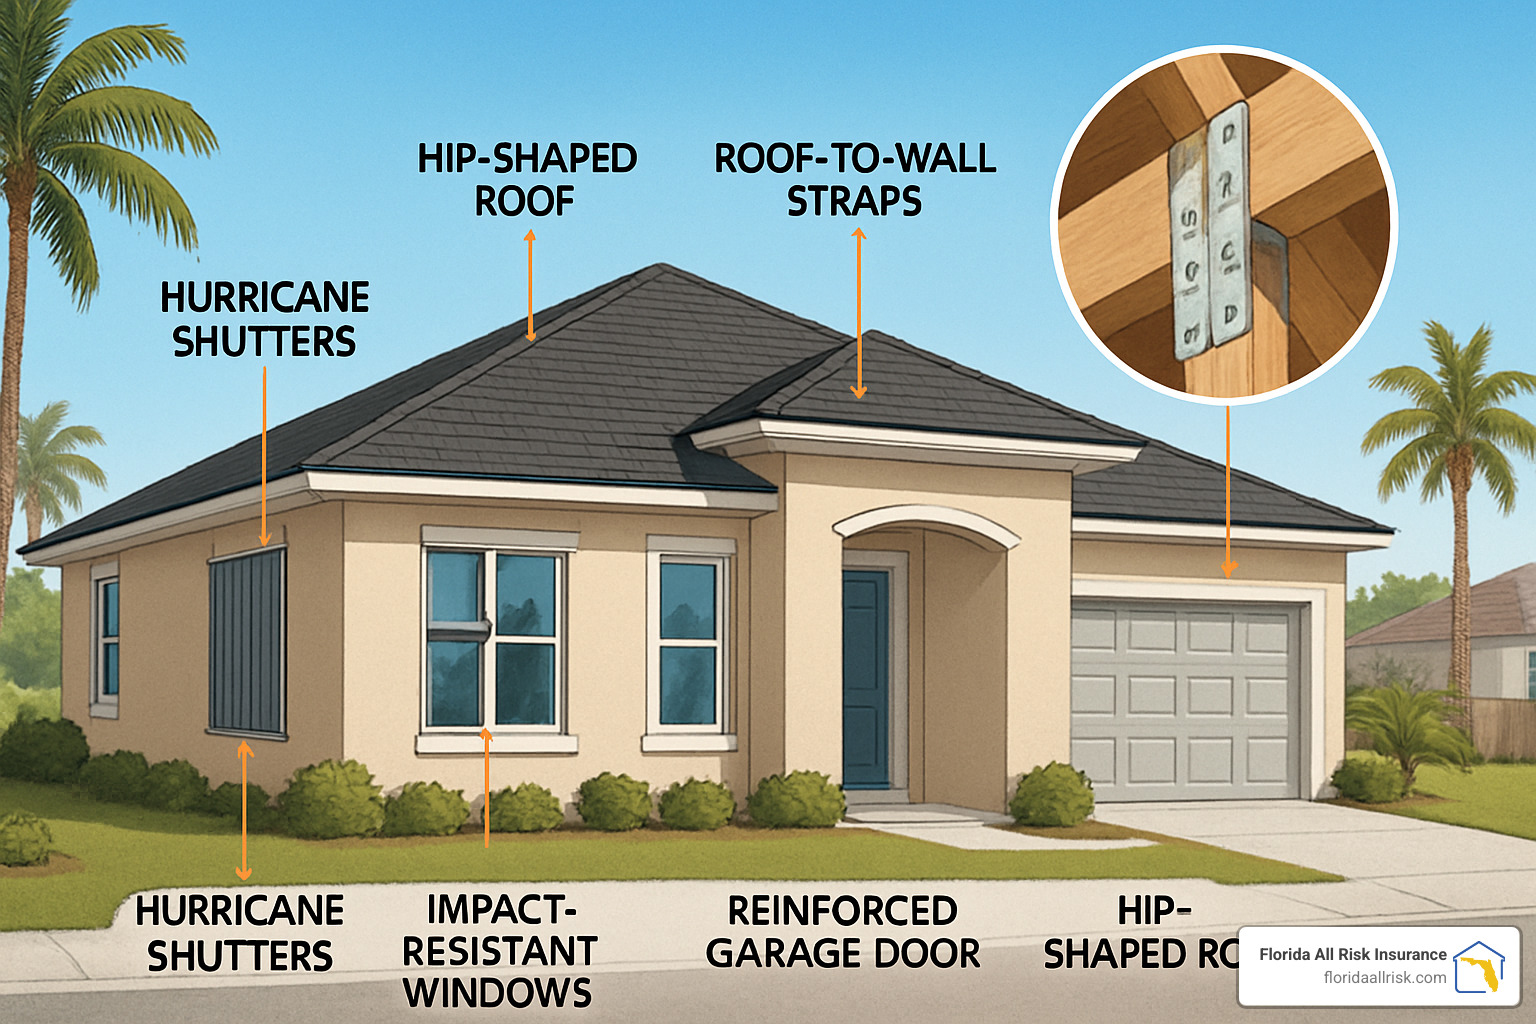
Florida law requires insurance companies to offer mitigation credits for hurricane protection features. These aren’t small discounts, either—impact windows, hurricane shutters, and reinforced roof attachments can reduce premiums by 20-50%. That’s serious savings while making your home safer.
Discounts Available for Homeowners in Englewood
At Florida All Risk Insurance, we’re committed to finding every possible discount for our neighbors here in Englewood.
Bundling your policies is perhaps the easiest way to save. The multi-policy discount typically saves 10-15% when you combine home and auto insurance with the same carrier. That’s money back in your pocket without changing your coverage.
Just replaced your roof? Make sure your insurance company knows! A new roof discount can yield significant premium savings—often enough that the roof practically pays for itself over a few years through reduced insurance costs.
Those impact-resistant windows and doors aren’t just for hurricane protection. They also qualify for substantial wind mitigation credits while giving you peace of mind during storm season.
Don’t overlook alarm system discounts. Monitored security systems, smoke detectors, and water leak detection devices can reduce premiums by 5-20% with many carriers. Plus, they help protect what matters most.
Many of our Englewood clients benefit from senior/retiree discounts. If you’re over 55 or retired and spending more time at home, be sure to mention this when getting quotes.
Maintaining a claim-free record for 3-5 years can qualify you for reduced premiums with many carriers. It’s one more reason to think carefully before filing smaller claims.
Practical Ways to Lower Your Bill
Beyond the standard discounts, here are some proven strategies we recommend to our Englewood clients looking to reduce their homeowners insurance Englewood FL costs:
Consider raising your deductible if you have adequate savings. The premium savings can be substantial, but make sure you’re comfortable with the higher out-of-pocket expense if you need to file a claim.
Updating utilities and systems isn’t just about modern convenience. Replacing outdated electrical, plumbing, and HVAC systems can lower your premiums while reducing the risk of water damage and fires—a win-win for your home and wallet.
Make your home more storm-resistant with hurricane protection features. Adding hurricane shutters, impact windows, or reinforced garage doors can substantially reduce premiums while protecting your most valuable asset during storm season.
As an independent agency, we can shop multiple carriers to find the best combination of coverage and price for your specific situation. Different insurers weigh risk factors differently, and what’s expensive with one company might be affordable with another.
Pay attention to your credit score. Paying bills on time and managing debt responsibly can positively impact your insurance score and premiums over time.
Schedule an annual policy review with us. Insurance needs change, and we can help ensure you’re not over-insured or carrying unnecessary coverages. Sometimes a quick 15-minute review can save hundreds of dollars.
For more detailed strategies on reducing your homeowners insurance costs, visit our Homeowners Insurance Savings resource page.
Living in paradise doesn’t have to break the bank. With the right approach to your homeowners insurance Englewood FL policy, you can enjoy comprehensive protection at a price that works for your budget.
From Damage to Payout: The Englewood Claims Roadmap
When disaster strikes your Englewood home, knowing what to do next can make all the difference. Even with the best insurance protection, navigating the claims process can feel overwhelming – especially when you’re already dealing with property damage and potential displacement.
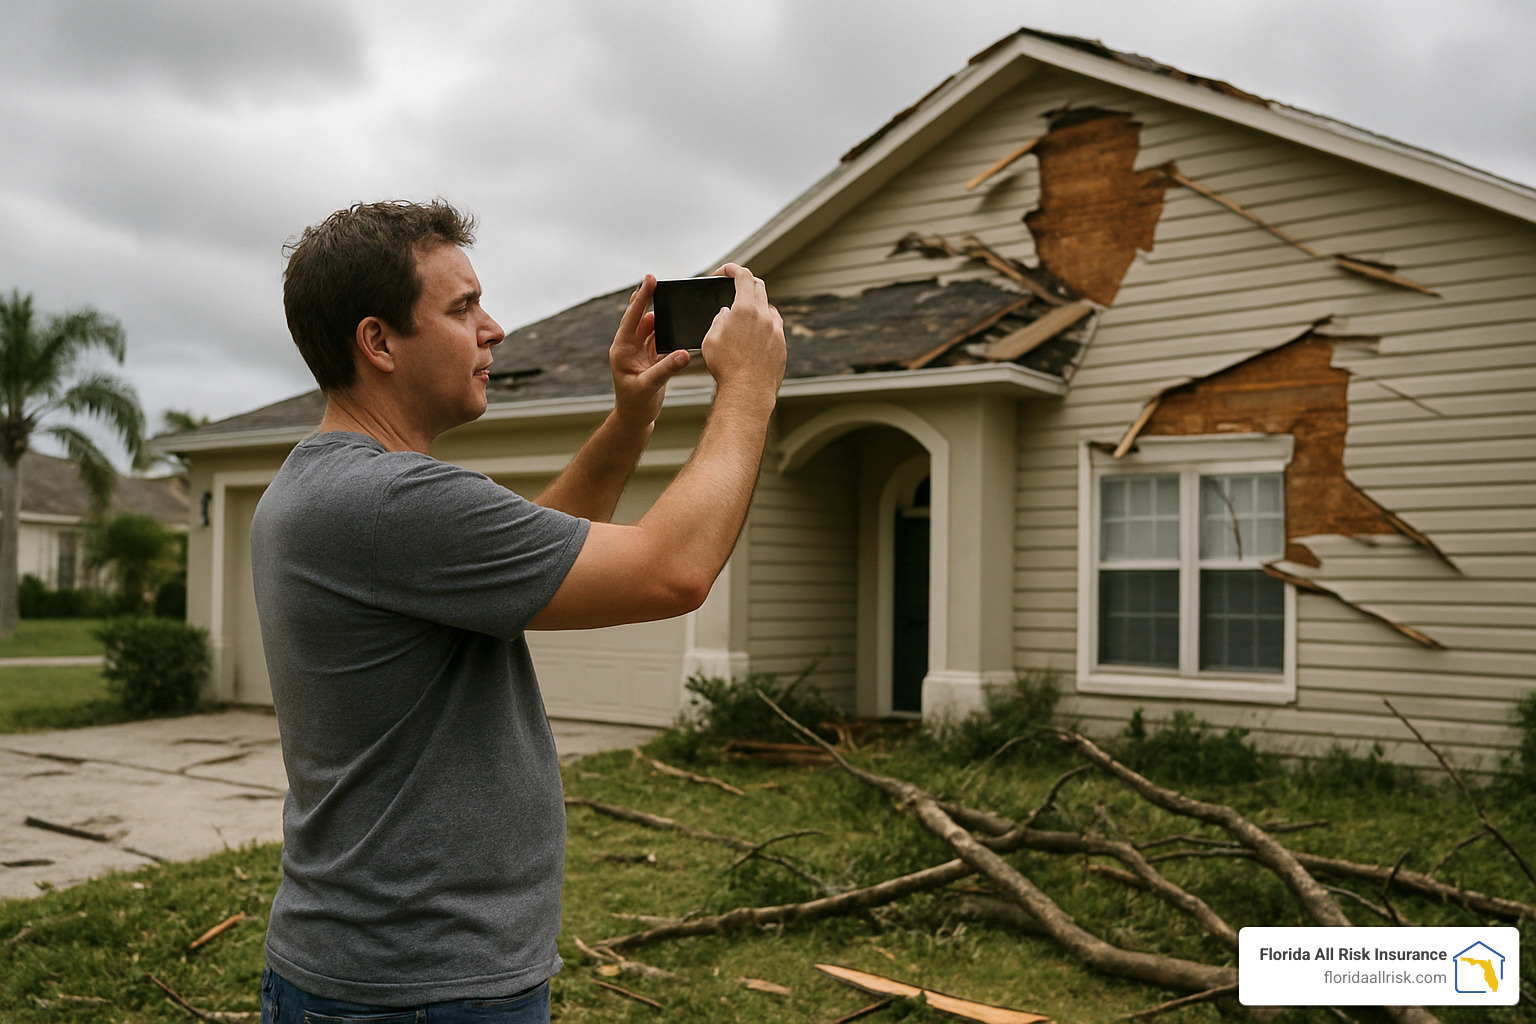
The good news? You don’t have to figure it out alone. Let me walk you through what happens after damage occurs when you have homeowners insurance Englewood FL.
The journey typically begins with 24-hour reporting – contacting your insurance company as soon as possible after finding damage. Most carriers offer round-the-clock claims hotlines because they understand disasters don’t conveniently happen during business hours.
Before you touch anything, grab your phone and start taking pictures. Photo documentation creates a visual record that will prove invaluable during the claims process. Capture everything from multiple angles – the more thorough, the better.
Sometimes you can’t wait for the insurance company’s approval before addressing immediate concerns. If your roof is damaged during a storm, for example, you’ll need to make emergency repairs to prevent water from causing additional damage inside your home. Just be sure to save every receipt for these temporary fixes, as they’re typically reimbursable.
Next comes the adjuster visit. This insurance professional will assess the damage either in person or, increasingly common these days, through virtual tools. Try to be present during this inspection if possible – you know your home best and can point out damage the adjuster might miss.
After the inspection, you’ll need to submit a formal proof-of-loss statement detailing everything damaged and its value. This is where that home inventory you hopefully created before disaster struck becomes worth its weight in gold. (No inventory? Start one today – your future self will thank you!)
Finally, there’s the payment timeline, which varies based on your insurer and the complexity of your claim. A straightforward claim might be settled within weeks, while extensive hurricane damage could take months to resolve completely.
Filing a Homeowners Insurance Englewood FL Claim Step-by-Step
When you’re facing property damage, follow these steps to ensure the smoothest possible claims experience:
First, contact your carrier immediately. Have your policy number handy when you call the claims number on your insurance documents. Provide basic information about what happened and the extent of damage.
While waiting for the adjuster, mitigate further damage by taking reasonable protective measures. This might mean shutting off water for a pipe burst, covering a damaged roof with a tarp, or boarding up broken windows. Your policy actually requires these preventative steps – failing to take them could jeopardize your claim.
Document everything carefully. Before moving or disposing of anything, take detailed photos and videos of all damage. Create an inventory listing damaged items with descriptions, approximate age, and estimated value.
Keep track of every expense related to your loss. Save all receipts for emergency repairs, temporary housing, restaurant meals, and other costs. These may be reimbursable under your additional living expenses coverage.
When it’s time to meet with the adjuster, be prepared. Gather any relevant documents like home inventories, receipts for valuable items, and contractor estimates if you already have them.
After the inspection, carefully review the settlement offer when it arrives. If the amount seems insufficient based on your documentation and research, you can dispute it by providing additional information or, in some cases, by hiring a public adjuster to advocate on your behalf.
Throughout the process, track your claim status regularly. Most insurers now offer online tracking systems, but don’t hesitate to contact your claims representative directly for updates.
Why a Local Agent Matters
There’s a world of difference between working with a local independent agent and dealing with an anonymous call center representative for your homeowners insurance Englewood FL needs.
A local agent brings invaluable neighborhood knowledge to the table. We understand Englewood’s unique vulnerabilities – from hurricane exposure to flood zones – and can ensure your coverage addresses these specific risks. We know which carriers offer the best protection for coastal properties and which ones might exclude certain coverages you need.
Independent agencies like Florida All Risk Insurance maintain relationships with multiple insurance companies, providing a carrier network that gives you more options than agents who represent just one company. This means we can shop around for the best combination of coverage and price for your specific situation.
When claims happen, having a local agent means having an advocate who knows you personally. We’ll help explain the process, follow up with adjusters, and intervene if things aren’t progressing as they should. Sometimes just having someone say “I’ve got your back” makes all the difference during stressful situations.
The personalized advice you receive from a local agent simply can’t be matched by online algorithms or distant call centers. We take the time to understand your specific property, your concerns, and your budget before making recommendations custom to your situation.
Perhaps most importantly, local agents offer faster claims follow-up. When needed, we can personally visit your property to help assess damage and expedite the claims process. After major storms, when call centers are overwhelmed, having a direct line to your agent can be invaluable.
As Englewood residents ourselves, we’ve weathered the same storms you have. We’ve helped countless neighbors through the claims process after hurricanes and other disasters. That shared experience creates a level of understanding and commitment you simply won’t find elsewhere.
Frequently Asked Questions about Homeowners Insurance Englewood FL
Is homeowners insurance required by law in Florida?
Contrary to what many new Florida residents believe, there’s no state law requiring you to have homeowners insurance. That said, if you’re like most Englewood homeowners with a mortgage, your lender absolutely will require coverage to protect their investment in your property.
Even if you own your home outright (congratulations!), going without homeowners insurance Englewood FL would be extremely risky given our area’s vulnerability to hurricanes, flooding, and other coastal perils. It’s a bit like going boating without life jackets—technically allowed, but not a gamble most would take with their largest investment.
There is one notable exception worth mentioning: If you’re seeking coverage through Citizens Property Insurance Corporation (Florida’s insurer of last resort), they require flood insurance for properties in designated flood zones as a condition of eligibility.
How do recent Florida insurance law changes affect Englewood residents?
Florida’s insurance landscape has been shifting dramatically in recent years, with lawmakers working to address our state’s ongoing insurance crisis. These changes directly impact your options and costs for homeowners insurance Englewood FL.
The Assignment of Benefits (AOB) reform has been particularly significant. These new restrictions help curb those questionable claims practices that were driving premiums through the roof for all of us. While you can still assign benefits to contractors, the new rules provide more transparency and protections against fraud.
For Englewood homeowners with older roofs, recent rule changes allow insurers to offer roof deductibles and actual cash value (depreciated) coverage options rather than full replacement cost. This might sound like a downgrade, but it’s actually helped make coverage more available for homes with aging roofs that might otherwise be uninsurable.
The litigation reforms have also been a positive step. By limiting excessive lawsuits against insurance companies, these changes have helped stabilize our market somewhat—though we’re still paying significantly more than homeowners in most other states.
The state has also implemented reinsurance assistance programs that help insurance companies manage their own risk costs, encouraging some carriers to continue writing policies in Florida when they might otherwise have left the market entirely.
While these changes won’t magically transform Florida into a low-cost insurance state overnight, they’re steps in the right direction that may eventually bring more options and stability to Englewood homeowners.
How can new homebuyers in Englewood get an accurate quote?
If you’re buying a home in Englewood, sorting out your insurance should be a top priority—not an afterthought. Here’s my honest advice after helping hundreds of new homebuyers in our area:
Start your insurance search at least 30 days before closing. I’ve seen too many buyers scramble at the last minute only to face closing delays or settle for overpriced policies because they ran out of time to shop around.
Be ready with detailed information about your new home. Insurers will want to know about construction materials, the age and type of roof, square footage, and any special features or risks. The more accurate information you provide, the more accurate your quote will be.
Wind mitigation inspections are worth every penny in our hurricane-prone area. This $75-150 inspection documents hurricane-resistant features of your home and can save you thousands in premium dollars over the years. Some of my clients have seen premium reductions of 25% or more from these inspections.
For homes over 30 years old (which describes many charming Englewood properties), most insurers will require a 4-point inspection examining the electrical, plumbing, HVAC, and roofing systems. Having this completed early can prevent unpleasant surprises during the insurance process.
Don’t forget to check the property’s flood zone designation. This affects both your flood insurance requirements and rates, and it’s information you’ll want before finalizing your purchase.
Working with an independent insurance agent who knows Englewood gives you access to multiple carriers rather than just one company’s options. At Florida All Risk Insurance, we’ve helped countless new Englewood homeowners steer these waters, often saving them significant money through proper coverage structuring and identifying all available discounts.
The cheapest policy isn’t always the best value—especially in a coastal community with our unique risks. The right coverage gives you peace of mind that your new Englewood dream home is properly protected against whatever nature throws our way.
Conclusion
Protecting your Englewood home isn’t just about checking a box on your mortgage requirements—it’s about creating a safety net that lets you truly enjoy coastal living without constant worry. The right homeowners insurance Englewood FL plan provides that essential peace of mind, custom specifically to our unique Florida risks and your individual property needs.

Here at Florida All Risk Insurance, we’ve walked alongside thousands of Englewood homeowners through hurricanes, flooding events, and everything in between. We’ve seen how proper coverage makes the difference between a temporary inconvenience and a financial disaster. As your neighbors who experience the same weather challenges and insurance market conditions you do, we understand what’s at stake.
What makes our approach different? As an independent agency, we’re not tied to a single insurance carrier with one-size-fits-all solutions. Instead, we can shop multiple options to find the protection that truly fits your home’s construction, location, and your personal priorities. When the winds pick up and storms approach, you’ll appreciate having an advocate who knows exactly what your policy covers—and who will be there to guide you through the claims process if needed.
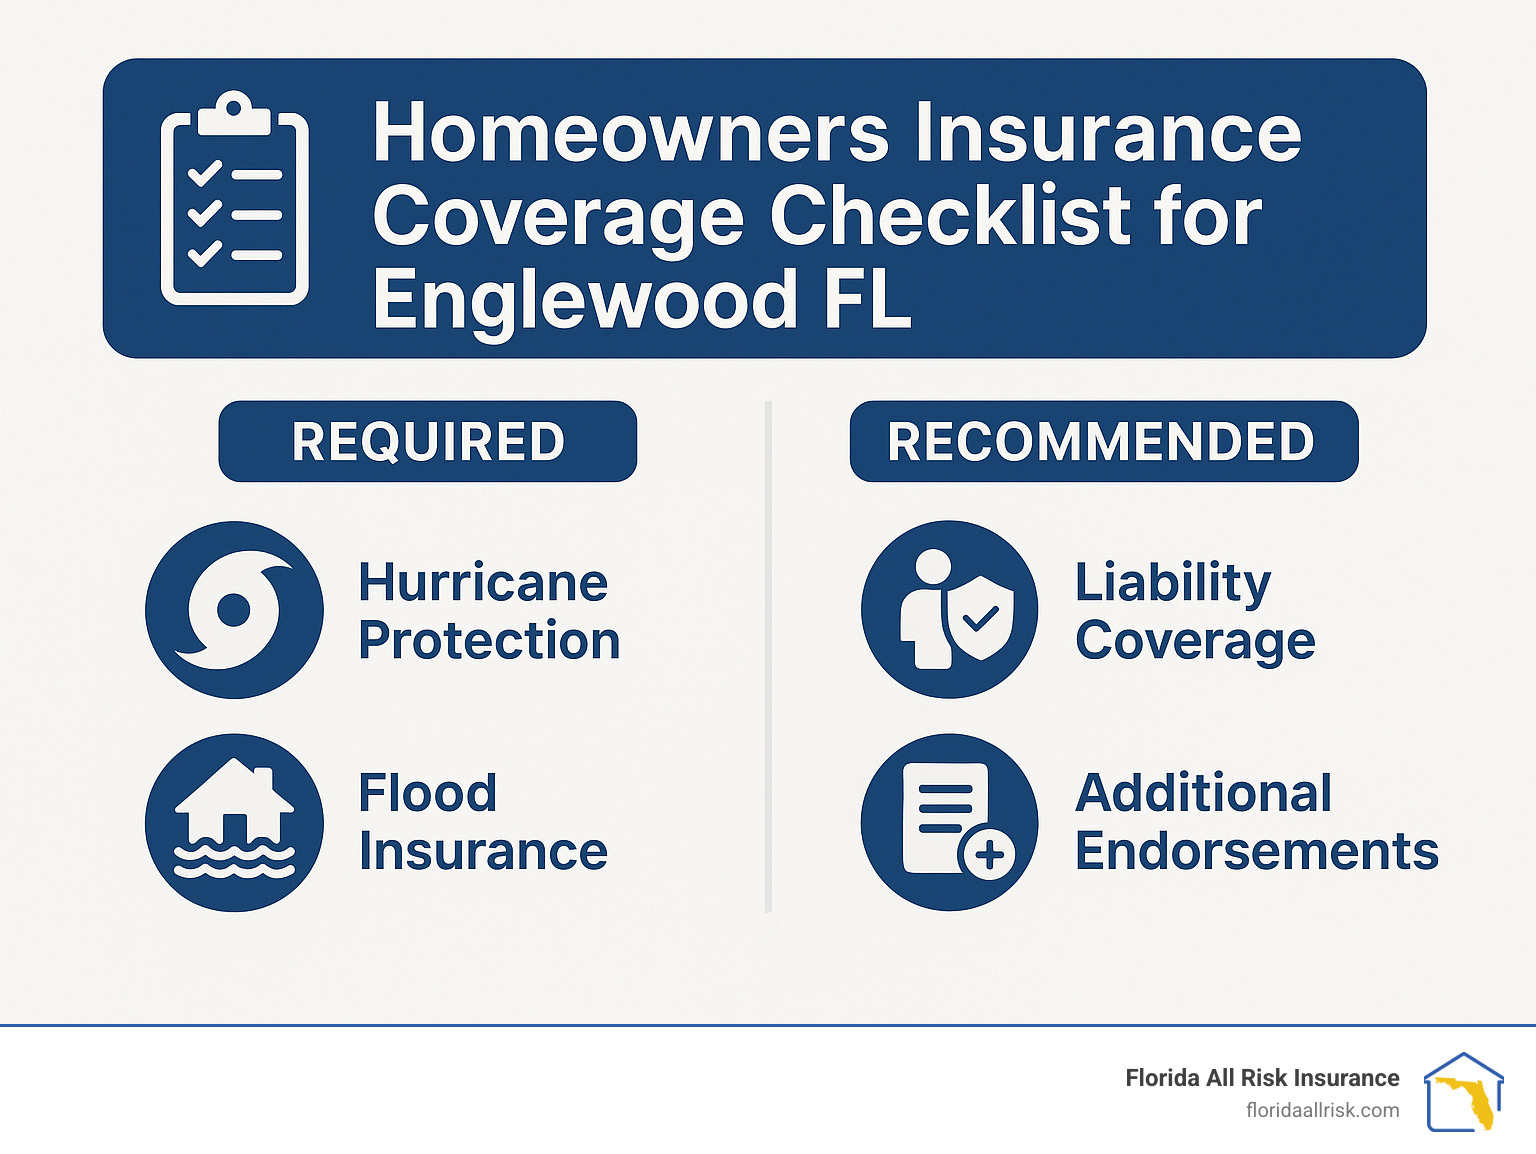
The reality is that insurance isn’t something to set up once and forget. Your home evolves—perhaps you’ve added hurricane shutters, replaced that aging roof, or installed a security system. Each improvement not only protects your home but potentially qualifies you for valuable premium discounts. That’s why we recommend annual reviews of your homeowners insurance Englewood FL coverage to ensure it still matches your current situation.
Don’t wait until you see a hurricane forming in the Gulf to wonder if your coverage is adequate. Take a proactive approach today. Whether you’re buying a new home, renewing existing coverage, or simply want a second opinion on your current policy, our team is ready to help with straightforward advice and local expertise.
For more information about custom coverage options specifically designed for Englewood properties, visit our custom coverage options page or give us a call. We’re committed to helping you protect what matters most—your home, your treasured possessions, and your financial well-being.
When it comes to finding the right homeowners insurance Englewood FL, having a local team who understands our unique coastal challenges makes all the difference. Let’s work together to create protection that lets you enjoy paradise with confidence.

