

Protecting Your Home in The Villages: Essential Insurance Guide
Home insurance the villages fl is a critical investment for residents of this popular retirement community. If you’re looking for the best insurance options in The Villages, here’s what you need to know:
- Average Cost: $2,479/year for a $150,000 home, $4,484 for a $300,000 home
- Savings Opportunity: Rates in The Villages are approximately 25% lower than Florida state averages
- Key Coverage Needs: Hurricane protection, flood insurance (separate policy), and wind mitigation
- Best Practices: Bundle policies, implement wind mitigation features, compare multiple quotes
The Villages presents unique insurance considerations due to its inland location, community-specific amenities, and Florida’s weather patterns. While rates are more affordable than coastal areas, residents still need comprehensive coverage that addresses potential risks from hurricanes, flooding, and other hazards.
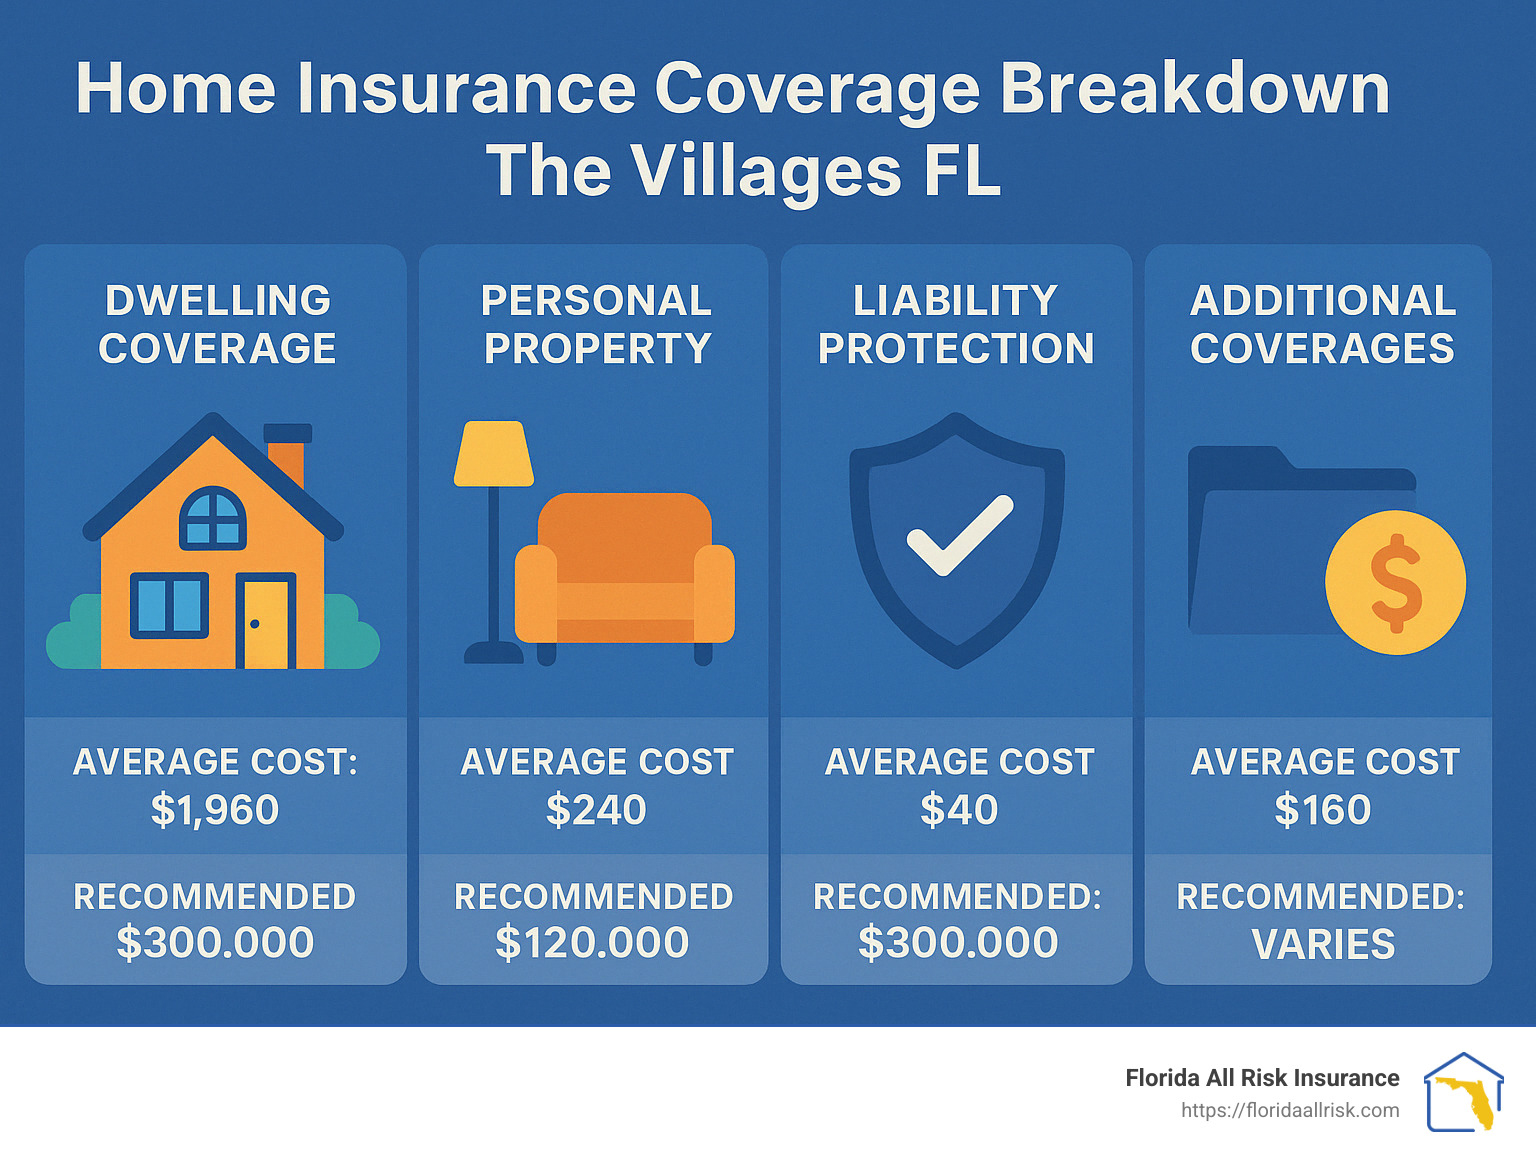
Most standard policies include dwelling coverage, personal property protection, liability coverage, and additional living expenses. However, they typically exclude flood damage, which requires a separate policy.
I’m Jason Miller, a second-generation insurance professional with over 20 years of experience helping Florida homeowners find the right coverage, including specialized home insurance the villages fl solutions custom to this unique community’s needs.
The Average Cost of Homeowners Insurance in The Villages, FL
Good news for residents of The Villages! If you’re looking for home insurance the villages fl, you’ll be pleased to know that your wallet might not take as big a hit as folks in other parts of Florida.
Thanks to The Villages’ inland location—safely tucked away from the direct coastal hurricane threats—insurance companies view homes here as lower risk. This geographical advantage translates directly into more affordable premiums for homeowners.
Let’s look at what you can actually expect to pay:
| Home Value | Average Annual Premium in The Villages | Florida State Average | Savings |
|---|---|---|---|
| $150,000 | $2,479 | $3,325 | 25% |
| $300,000 | $4,484 | $6,026 | 26% |
| $450,000 | $6,436 | $8,644 | 26% |
As you can see, living in The Villages means you’ll likely save about a quarter of what the average Floridian pays for similar coverage. That’s a significant difference—especially for retirees and others living on fixed incomes who call this community home.
Insurance analysts have noticed this trend too. In fact, one analysis pointed out that “No company in The Villages comes in over the state average,” highlighting just how favorable the insurance market is in this community.
Of course, these figures represent averages, and your actual premium could be higher or lower. Your specific rate will depend on factors like your home’s age, construction type, and the protective features you’ve installed. We’ll dive into these factors in the next section to help you understand what might affect your personal home insurance the villages fl premium.
For many residents, these savings make The Villages not just a wonderful place to live, but a financially sensible choice as well. And who doesn’t appreciate keeping a little extra money in their pocket each year?
Factors Influencing Home Insurance Rates in The Villages
When you’re shopping for home insurance the villages fl, you’ll quickly find that not all homes are created equal in the eyes of insurance companies. Several key factors determine your premium, and understanding these can help you make smarter decisions about your home and coverage.
Home Construction Type
The bones of your home matter tremendously when it comes to insurance rates. Homes built with concrete block structure (CBS) typically enjoy lower premiums because they stand up better to Florida’s wild weather. In contrast, wood-frame homes often come with higher premiums since they’re more vulnerable to wind damage and fire.
Your roof style makes a difference too. Those hip roofs (sloped on all four sides) are insurance darlings because they handle high winds better than gable roofs (two slopes meeting at a ridge).
I remember talking with a Villages resident who told me, “We were hit by the tornado in ’07 and our insurance took care of it all. Having a concrete block home with proper wind mitigation features definitely helped keep our premiums reasonable despite the claim.” Stories like this highlight how construction choices impact both safety and affordability.
Home Age
In The Villages, your home’s birth certificate matters almost as much as its construction type. Homes fall into three main age brackets that affect insurance costs:
Pre-2001 homes were built before Florida’s updated building codes and often face higher premiums unless they’ve been upgraded with modern safety features. These charming older homes can still be insurance-friendly with the right improvements.
Homes built between 2001-2004 incorporate improved building standards and typically qualify for more moderate insurance rates
The new kids on the block (2005-present) usually qualify for the best insurance rates since they meet or exceed current building codes. The difference is substantial
Wind Mitigation Features
In Florida, wind mitigation is the magic word for insurance savings. These features help your home withstand high winds, and insurers love them because they reduce the likelihood of costly claims.
Hurricane straps (those metal connectors securing your roof to the walls) might not be visible to visitors, but your insurance company definitely notices them. Impact-resistant windows and doors, reinforced garage doors, and secondary water resistance under your roof shingles are all features that can significantly reduce your premium.
A wind mitigation inspection typically costs between $75-150, but it’s money well spent. One client called me laughing after her inspection, saying, “I just spent $100 to save $1,200 on my annual premium. Why didn’t I do this years ago?” It’s one of the smartest insurance investments you can make in The Villages.
Location Within The Villages
Even within this planned community, location matters. Homes in newer sections of The Villages often have updated construction standards that insurance companies reward with better rates. Your proximity to fire stations can also impact your premium
Your flood zone designation matters too. While flood insurance is separate from your homeowners policy (more on that later), your location’s flood risk can affect your overall insurance picture.
Weather-Related Hazards in The Villages
The Villages may be inland, but Florida’s weather doesn’t play favorites. Several weather-related risks still impact home insurance the villages fl rates for residents.
Hurricane Risk
Being inland gives The Villages some protection from hurricanes, but as recent storms have shown in 2024 and 2025, these massive storms can still cause significant damage even miles from the coast.
Most policies in The Villages include a separate hurricane deductible, typically 2% of your dwelling coverage. For a $300,000 home, that means you’d pay the first $6,000 in hurricane damage before your insurance kicks in. Unlike some coastal areas where wind coverage might be separated from standard policies, this is less common in The Villages thanks to its inland location
Flooding Concerns
Don’t let The Villages’ inland location fool you
I’ll never forget what one Villages resident told me after a particularly wet week in 2025: “After a heavy week of rain, several homes near our golf course had water come in. Those without flood insurance faced out-of-pocket costs averaging $25,000. Even 1 inch of water can cause that much damage.”
The critical thing to remember is that standard home insurance the villages fl policies do not cover flood damage
Sinkhole Risk
Living in central Florida means living above limestone, which can dissolve over time and create underground voids
The Role of Wind Mitigation in Home Insurance Premiums in The Villages, FL
When it comes to lowering your home insurance the villages fl premium, nothing packs a bigger punch than wind mitigation features.
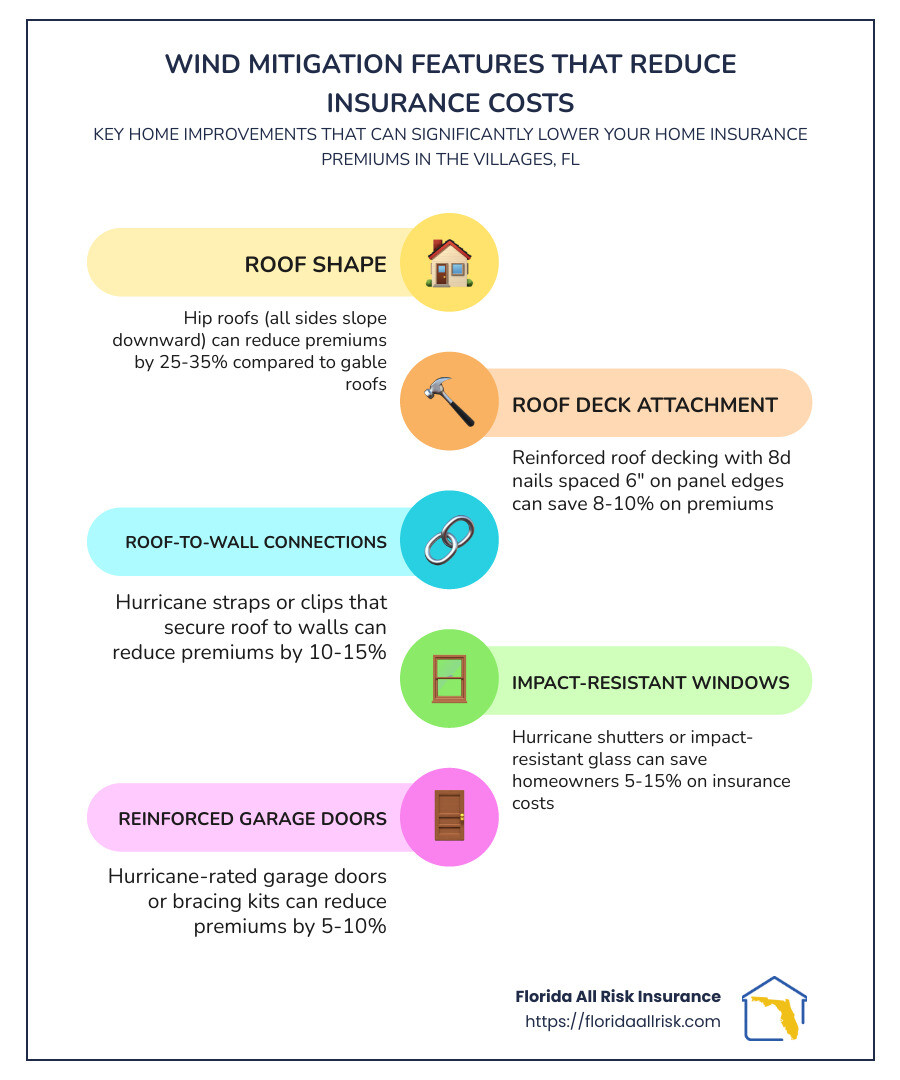
“Wind mitigation is important in Florida because of the devastation hurricanes have caused to properties in the past. Insurers are required by law to reward homeowners whose houses have effective wind mitigation measures with a steep discount on premiums.”
The savings potential is impressive. A pre-2001 home valued at $300,000 without wind mitigation might cost $5,200 annually to insure, while the same home with proper wind mitigation features might cost just $4,100
The most valuable wind mitigation features include your roof covering (when was it last replaced and does it meet current codes?), roof deck attachment (how securely is the decking attached to the structure?), and roof-to-wall connection (are hurricane clips or straps installed?).
Your roof geometry matters too
To get credit for these features, you’ll need a wind mitigation inspection from a licensed inspector. The report they provide becomes your ticket to potential discounts with your insurance company.
As one happy Villages resident told me, “After getting our wind mitigation inspection, our annual premium dropped by over $800. The inspection cost $125, so it paid for itself many times over in just the first year.” That’s the kind of math we all appreciate!
Understanding Standard Homeowners Insurance Coverage in The Villages
When you buy a home in The Villages, getting the right home insurance the villages fl policy isn’t just smart—it’s essential for protecting what might be your largest investment. Let’s break down what a typical policy includes, in plain English.
Dwelling Coverage (Coverage A)
Think of dwelling coverage as the backbone of your policy. It protects the actual structure of your home—the walls, roof, floors, built-in appliances, and attached structures like your garage.
If a windstorm tears off part of your roof or a fire damages your kitchen, this is the coverage that rebuilds your home. For Villages residents, experts strongly recommend setting your dwelling coverage at 100% of your home’s rebuilding cost—not its market value or purchase price. These numbers can be quite different, especially in today’s real estate market!
A local Villages homeowner recently told me, “I was shocked to learn rebuilding my $350,000 home would actually cost about $400,000 due to current construction costs. Adjusting my coverage saved me from potential disaster.”
Other Structures Coverage (Coverage B)
This part of your home insurance the villages fl policy covers the standalone structures on your property—that detached golf cart garage, your garden shed, fences, or that lovely gazebo where you enjoy morning coffee.
These structures typically receive coverage equal to about 10-20% of your dwelling coverage amount. So if your home is insured for $300,000, you might have $30,000-$60,000 to protect these other structures. In The Villages, where many residents have custom outdoor living spaces, this coverage is particularly important.
Personal Property Coverage (Coverage C)
Your furniture, clothing, electronics, kitchenware, artwork, and other possessions fall under personal property coverage. Standard policies typically provide personal property coverage at 50-70% of your dwelling amount.
Many Villages residents have downsized from larger homes, bringing valuable items with them. It’s worth creating a home inventory with photos or video to document your belongings. Items like jewelry, firearms, or collectibles usually have special limits (often between $1,000-$2,500) unless you specifically add them to your policy with scheduled personal property coverage.
Loss of Use Coverage (Coverage D)
Imagine a severe storm damages your home so badly you can’t live there during repairs. Where would you stay? How would you pay for temporary housing? That’s where loss of use coverage comes in.
This coverage, typically set at 20% of your dwelling amount, helps pay for additional living expenses if you’re displaced from your home due to a covered loss. It covers hotel stays, restaurant meals (beyond what you’d normally spend on food), pet boarding, and even laundry costs. For Villages residents on fixed incomes, this protection provides tremendous peace of mind.
Personal Liability Protection (Coverage E)
We all try to be careful, but accidents happen. If someone slips on your wet floor and breaks their wrist, or your golf cart causes property damage, personal liability coverage protects your assets.
This coverage starts at $100,000 on most policies, but in today’s litigious society, many Florida All Risk Insurance agents recommend at least $300,000 or more. It pays for legal defense, settlements, and judgments if you’re found liable. Did you know that dog bites account for about one-third of all liability claims nationwide? Even the friendliest pets can have bad days.
Medical Payments (Coverage F)
If a visitor suffers a minor injury on your property, medical payments coverage pays for smaller medical bills regardless of who was at fault. This coverage (typically $1,000-$5,000) helps preserve friendships by taking care of things like a doctor’s visit after your neighbor trips on your garden hose.
Common Exclusions in Home Insurance Policies in The Villages, FL
Understanding what your home insurance the villages fl policy doesn’t cover is just as important as knowing what it does cover.
Flood Damage
Perhaps the biggest surprise for many homeowners is learning that standard policies provide absolutely no coverage for flood damage—regardless of what caused the flooding. Whether it’s from heavy rain, rising water tables, or overflowing retention ponds, flood damage requires a separate flood insurance policy.
“Flood damage can be incredibly costly, and many homeowners aren’t aware that homeowners insurance doesn’t cover it.”
Even though The Villages sits inland, flooding can still occur. In fact, over 20% of flood claims come from properties outside designated flood zones. A separate flood insurance policy through the National Flood Insurance Program (NFIP) or private insurers is essential for comprehensive protection.
Earth Movement
Standard home insurance the villages fl policies exclude damage from earthquakes, landslides, and general earth shifting. While earthquakes are rare in Florida, these exclusions are still important to understand. Specialized coverage can be added if you’re concerned about these risks.
Sinkhole Damage
Florida’s limestone geology makes sinkholes a real concern. While catastrophic ground cover collapse (when a sinkhole causes your home to become uninhabitable) is covered under Florida law, regular sinkhole damage often requires additional coverage. Given The Villages’ location in central Florida, this is something worth discussing with your Florida All Risk Insurance agent.
Neglect and Maintenance Issues
Your policy won’t cover damage resulting from poor maintenance or neglect. That slow leak under your sink that eventually caused mold? Not covered. Termite damage? Also not covered. Insurance is designed for sudden, accidental damage—not gradual deterioration or pest infestations.
A surprising 41% of Americans mistakenly believe mold damage is covered by standard homeowner policies. In reality, it’s only covered if it results directly from a covered event, like a burst pipe, and not from ongoing moisture or maintenance issues.
Having the right home insurance the villages fl policy gives you confidence that your retirement dream home is protected. The peace of mind that comes from knowing exactly what’s covered—and what isn’t—is invaluable for Villages residents looking to enjoy their active adult lifestyle without financial worries.
Additional Coverages to Consider for Your Home in The Villages
When it comes to protecting your home in The Villages, standard insurance is just the starting point. Let’s explore some additional coverages that can give you comprehensive protection and peace of mind.
Flood Insurance
Florida’s rainy climate makes flood insurance perhaps the most crucial additional coverage for Villages residents, even though we’re located inland.
“Flood damage can be incredibly costly, and many homeowners aren’t aware that homeowners insurance doesn’t cover it.”
Did you know that just one inch of water can cause $25,000 in damage to your home? That’s a sobering thought, especially since standard home insurance the villages fl policies provide zero coverage for flood damage.
You’ll need to purchase flood insurance as a separate policy, either through the National Flood Insurance Program (NFIP) or from private insurers. There’s typically a 30-day waiting period before coverage takes effect, so don’t wait until storm clouds are gathering to get protected.
Even if you’re not in a designated flood zone, flood insurance is still worth considering. In fact, over 20% of flood claims come from properties outside high-risk zones. With Florida’s heavy rainfall patterns, your beautiful Villages home deserves this extra layer of protection.
Scheduled Personal Property
Those special items you’ve collected over the years may need extra protection beyond what your standard policy provides. Home insurance the villages fl policies typically set sub-limits on valuables like jewelry, fine art, collectibles, firearms, and musical instruments.
With scheduled personal property coverage, you can insure these treasures for their full value. This coverage often comes with perks like no deductible and protection against accidental loss (like that diamond earring that mysteriously disappeared). You’ll typically need appraisals or receipts for high-value items, but the peace of mind is worth the extra paperwork.
Water Backup Coverage
Florida’s rainy season can put a strain on drainage systems. Water backup coverage protects you from damage caused by backed-up drains, sewers, or sump pumps—something not included in your standard home insurance the villages fl policy.
For about $25-50 annually, you can get $5,000-$10,000 in water backup coverage. That’s a small price to pay to avoid the headache (and expense) of dealing with water damage from a backed-up drain during a heavy Florida downpour.
Screened Enclosure Coverage
Those lovely lanais and screened enclosures that make Florida living so enjoyable need special attention in your insurance planning. Many standard policies limit or completely exclude coverage for these structures, which are particularly vulnerable to wind damage.
You can add an endorsement to your home insurance the villages fl policy to cover these spaces. Given how central these outdoor living areas are to the Villages lifestyle, this coverage is well worth considering.
Service Line Coverage
Hidden beneath your property lie utility lines that can cause major headaches when they fail. Service line coverage protects the water, sewer, gas, electric, and communication lines on your property.
For approximately $40 annually, you can get about $10,000 in coverage—a small investment that can save you thousands if an underground line fails. This coverage is especially valuable in older sections of The Villages where infrastructure may be aging.
Golf Cart Coverage
What’s life in The Villages without a golf cart? These essential vehicles need proper insurance too. Your homeowners policy might provide limited coverage when the cart is on your property, but that’s typically not enough.
You have several options: add coverage to your auto policy, include an endorsement on your homeowners policy, or purchase a separate golf cart policy. With so many golf carts zipping around The Villages, proper liability protection is essential—accidents involving these vehicles can lead to significant claims.
Equipment Breakdown Coverage
Today’s homes are filled with complex systems and appliances. Equipment breakdown coverage protects your HVAC systems, water heaters, kitchen appliances, and even pool equipment from sudden and accidental breakdowns.
Unlike home warranties, this coverage is typically more comprehensive and cost-effective. For homes in The Villages with multiple sophisticated systems, this coverage can save you from unexpected repair or replacement costs.
Ordinance or Law Coverage
Building codes evolve over time, and if your home suffers damage, you might be required to rebuild according to current standards. Ordinance or law coverage pays for the increased costs associated with bringing your home up to code during repairs.
This coverage is particularly important for older homes in The Villages built before current Florida building codes. It covers not only the cost difference between pre-damage condition and current requirements but also any necessary demolition of undamaged portions that must be removed to comply with codes.
Each of these coverages addresses specific risks that Villages residents face. While they add to your premium, they also provide targeted protection that can save you thousands in the long run. At Florida All Risk Insurance, we’re happy to help you assess which of these additional coverages make sense for your unique situation.
Tips to Save on Home Insurance Premiums in The Villages, FL
Looking to keep more money in your pocket while still protecting your home? You’re not alone! Many residents in The Villages are finding smart ways to reduce their home insurance the villages fl costs without cutting corners on essential coverage.
Implement Wind Mitigation Measures
Remember those wind mitigation features we discussed earlier? They’re not just good for protecting your home—they’re fantastic for your wallet too. Having a certified inspector perform a wind mitigation inspection (typically $75-150) could save you hundreds or even thousands annually.
One Villages resident told me, “After documenting our hurricane straps and impact windows, our premium dropped by $780 a year. The inspection paid for itself in the first month!” If you’re renovating, consider upgrading to wind-resistant features—they’ll pay for themselves through insurance savings before you know it.
Choose Newer Construction When Possible
Homes built to recent building codes are insurance companies’ favorites. If you’re house hunting in The Villages, keep in mind that homes built after 2005 often qualify for the best rates. The difference can be substantial—sometimes 20-30% less than a similar pre-2001 home.
Even if you already own an older home, consider mentioning any major renovations to your insurer. That new roof or updated electrical system might qualify you for better rates.
Bundle Multiple Policies
The old saying “there’s strength in numbers” applies perfectly to insurance. Combining your policies with the same insurer typically leads to significant discounts on all of them.
Home and auto bundles are the most common, often saving 10-15% across both policies. Many Villages residents also find that adding their golf cart insurance to the bundle creates even more savings. One homeowner shared, “By bundling everything with one company, we’re saving over $500 annually—that’s a lot of rounds of golf!”
Increase Your Deductible
It’s a simple equation: higher deductible = lower premium. If you have a healthy emergency fund, consider raising your standard deductible from $500 to $1,000 or even $2,500. This simple change might save you 10-15% on your premium.
Just be careful with your hurricane deductible, which in Florida is typically percentage-based (1%, 2%, or 5% of your dwelling coverage). For a $300,000 home, a 2% hurricane deductible means you’d pay the first $6,000 in hurricane damage before insurance kicks in.
Install Security Features
Insurance companies love it when you protect your home, and they’ll reward you for it. A monitored alarm system can earn you discounts of 5-20% on your home insurance the villages fl. Fire protection measures like smoke detectors, sprinkler systems, and fire extinguishers also help lower your rates.
One of the newest discount opportunities comes from water leak detection systems. These smart devices can detect leaks and automatically shut off your water, preventing the most common cause of home insurance claims. Some insurers offer discounts up to 15% for these systems.
Maintain Good Credit
You might not realize it, but in Florida, your credit score affects your insurance rates. Insurance companies use credit-based insurance scores to help determine premiums, with better scores typically resulting in lower rates.
Check your credit reports regularly and correct any errors you find. Simple habits like paying bills on time and reducing debt can improve your insurance score—and your premiums—over time.
Shop Around and Compare Quotes
Perhaps the most powerful way to save is also the simplest: comparison shopping. Insurance markets change constantly, so even if you’re happy with your current insurer, it’s worth checking rates every 2-3 years.
Working with an independent agency like Florida All Risk Insurance gives you access to multiple carriers without doing all the legwork yourself. They can help you compare not just prices but also coverage differences, company reputations, and claims service quality.
As one satisfied customer put it, “I thought I was getting a good deal until my agent showed me three other options. I ended up with better coverage for $430 less per year!”
Ask About Additional Discounts
Many insurers offer discounts that aren’t automatically applied—you have to ask for them. As a Villages resident, you might qualify for:
Retiree discounts that reward your life experience with lower rates. Claims-free discounts for those who haven’t filed claims over a certain period. Some professional organizations and alumni associations qualify members for special group rates. And don’t forget loyalty discounts—some insurers reward customers who stick with them for several years.
A quick 15-minute conversation with your agent about available discounts could save you hundreds each year. After all, as we like to say in the insurance world, “It never hurts to ask!”
Frequently Asked Questions about Home Insurance in The Villages, FL
How does the location of a home in The Villages affect insurance premiums?
When you’re shopping for home insurance the villages fl, your specific location within this beautiful retirement community plays a bigger role than you might think.
Homes in the newer sections of The Villages often qualify for better insurance rates thanks to their updated construction standards and compliance with recent building codes. It’s like buying a new car versus a classic – both have their charms, but the newer model comes with modern safety features that insurers love.
Your flood zone designation is another crucial factor. While this doesn’t affect your standard homeowners policy premium, it dramatically impacts what you’ll pay for flood insurance. Some neighborhoods in The Villages sit at slightly higher elevations, providing both peace of mind and potential savings.
Living closer to fire stations can shave dollars off your premium too. Insurance companies know that faster emergency response times often mean less damage during a crisis. It’s one of those hidden benefits of certain Villages locations that your insurance agent might point out.
Some neighborhoods may have higher rates based simply on claims history. If your particular area has experienced multiple weather events or has a higher-than-average claim rate, that statistical data follows the neighborhood.
One delighted resident told me: “We moved here from Tampa and our insurance premium dropped by almost 40% for a similarly valued home. The inland location makes a huge difference!”
What are the benefits of bundling multiple insurance policies in The Villages?
Bundling your insurance policies is like buying in bulk at Costco – it just makes financial sense, especially for Villages residents.
The most obvious benefit is the premium discount. Most insurers offer 10-15% savings when you bundle your home insurance the villages fl with your auto policy. For the average Villages household, this can mean $300-600 back in your pocket annually.
Beyond the savings, bundling creates simplicity in your life. One company, one agent who knows your situation, one billing cycle to manage, and often just one deductible to worry about for related claims. At a stage of life when simplifying becomes increasingly important, this benefit shouldn’t be underestimated.
Coverage gaps become less likely when all your policies live under one roof. Your agent can see the complete picture of your insurance needs and spot potential vulnerabilities that might otherwise go unnoticed between separate companies.
Insurance companies also tend to show more flexibility with long-term customers who have multiple policies. When you need to file a claim or request a policy adjustment, that established relationship often translates to smoother service.
As one satisfied Villages resident shared: “After bundling our home, auto, and umbrella policies, not only did we save about $600 annually, but when we had a minor claim, our agent handled everything seamlessly across all our coverage. I didn’t have to call multiple companies or explain my situation repeatedly.”
How can homeowners in The Villages save on their insurance premiums?
Beyond the standard savings strategies we covered earlier, Villages residents have several unique opportunities to keep their home insurance the villages fl costs manageable.
Community programs can be a hidden source of savings. Some homeowners associations and community groups in The Villages have negotiated group insurance rates that individual homeowners can access. Ask your neighbors or HOA representative if such programs exist in your neighborhood.
Annual policy reviews are absolutely essential in Florida’s dynamic insurance market. Schedule a yearly sit-down with your agent to ensure you’re not paying for unnecessary coverage or missing new discounts that have become available. Insurance companies regularly update their discount programs, and without a review, you might leave money on the table.
Document home improvements carefully. That new impact-resistant garage door or roof upgrade isn’t just protecting your home—it could be saving you money if your insurance company knows about it. Keep receipts, take photos, and make sure your agent updates your policy accordingly.
Pay-in-full discounts can save you 5-10% compared to monthly payment plans. If you can manage the larger upfront payment, many insurers will reward you with meaningful savings.
Continuous coverage matters to insurance companies. Avoid lapses in your insurance, as companies often charge higher rates when you need to reinstate coverage after a gap. This shows them you’re a responsible homeowner who values protection.
For older homes in The Villages, consider actual cash value coverage for aging roofs. While replacement cost coverage is generally preferred for most of your home, accepting actual cash value for an older roof might significantly reduce your premium until you’re ready to replace it.
As one savvy Villages resident told me: “By implementing several of these strategies and working closely with our agent, we’ve managed to keep our insurance premium increase to less than 5% over the past three years, despite the challenging Florida insurance market. In today’s environment, that feels like a win!”
Conclusion
Securing the right home insurance the villages fl isn’t just about checking a box—it’s about protecting the retirement dream you’ve worked so hard to achieve. While residents of The Villages enjoy more affordable insurance rates than many Floridians, the unique risks of this community require thoughtful consideration when selecting coverage.
Throughout this guide, we’ve explored several critical aspects of home insurance in The Villages. Let’s take a moment to bring it all together.
The inland location of The Villages provides a significant financial advantage, with insurance rates approximately 25% lower than the Florida state average. This is welcome news for retirees and residents on fixed incomes who still want comprehensive protection.
Your home’s construction type, age, and wind mitigation features dramatically influence what you’ll pay. Newer homes built with concrete block construction and proper wind mitigation features can save thousands annually compared to older, frame-built homes without these protections.
Perhaps most importantly, we’ve highlighted the crucial gaps in standard policies. Flood damage—which can be catastrophic and expensive—requires a separate policy regardless of your flood zone. One inch of water can cause $25,000 in damage, making flood insurance a wise investment even for homes not in designated flood zones.
Beyond the basics, The Villages lifestyle often calls for additional coverages like scheduled personal property protection for valuables, water backup coverage for Florida’s rainy seasons, and appropriate golf cart insurance for your primary mode of transportation around the community.
Smart Villages residents can achieve substantial savings through several strategies: bundling policies with one insurer, implementing wind mitigation measures, choosing appropriate deductibles, and installing security features. Working with an experienced independent agent who can shop multiple carriers often yields the best combination of coverage and value.
At Florida All Risk Insurance, we understand The Villages isn’t just any community, and you aren’t just any homeowner. Your insurance needs are as unique as your lifestyle. As an independent agency, we offer access to numerous carriers, ensuring you receive personalized coverage options that protect what matters most to you.
Whether you’re just moving to The Villages or reassessing your current coverage, we’re here to help you steer Florida’s complex insurance landscape with straightforward advice and friendly service. No insurance jargon—just clear guidance from neighbors who understand your needs.
For more comprehensive information about protecting your Florida home, visit our homeowners insurance Florida page or reach out today for a personalized quote custom to your specific situation in The Villages.
For additional resources on Florida insurance topics, you can also check out the Florida Office of Insurance Regulation website for official state information about homeowners insurance regulations and consumer protections.

