

Home Insurance Palm Harbor FL 2025: Best Guide
Why Palm Harbor Homeowners Need Specialized Insurance Protection
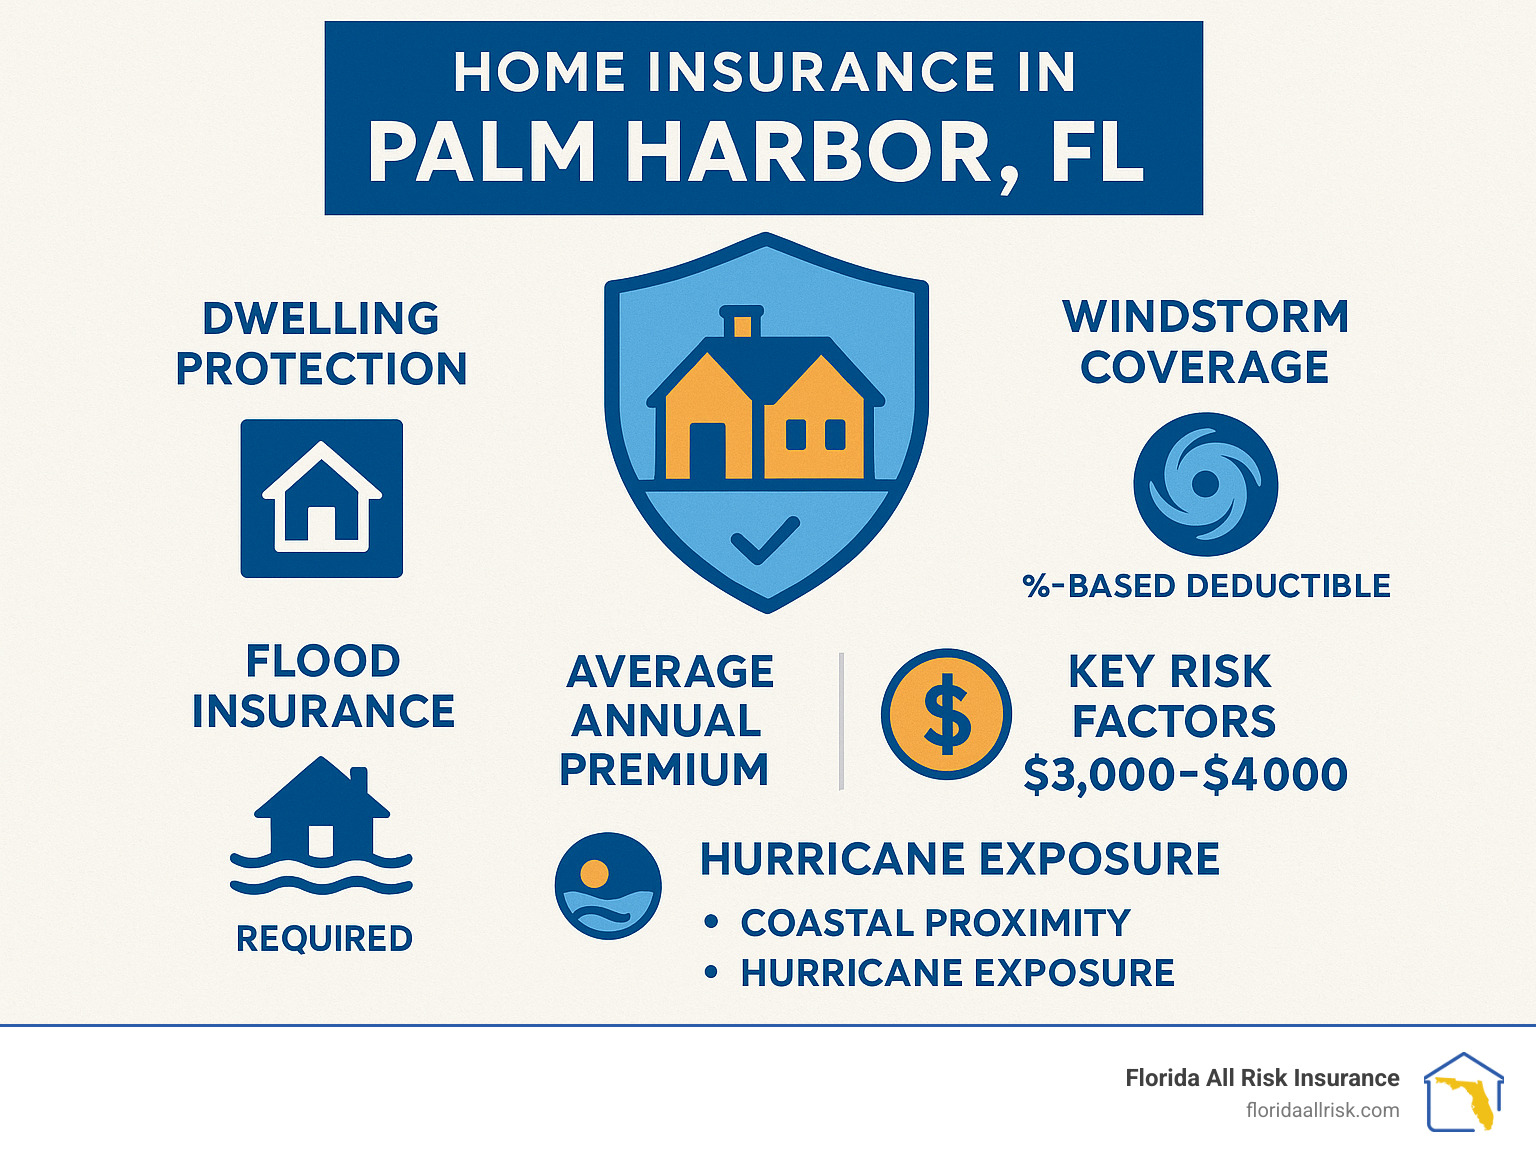
Home insurance palm harbor fl is essential for protecting your most valuable asset in a region prone to hurricanes, flooding, and other coastal risks. Homeowners here face unique challenges that require specialized coverage beyond a standard policy.
Quick Overview – Home Insurance in Palm Harbor, FL:
- Average Annual Premium: $3,000-$4,000 (higher than national average)
- Required Coverage: Windstorm/hurricane protection with separate deductibles
- Essential Add-On: Flood insurance (not included in standard policies)
- Key Risk Factors: Proximity to coast, hurricane exposure, potential flooding
- Mandatory Requirement: Required by mortgage lenders, not Florida law
- Best Strategy: Work with independent agents to compare multiple carriers
Palm Harbor’s coastal location in Pinellas County creates specific insurance needs. Standard homeowners policies exclude flood damage, a common cause of property loss in Florida. Additionally, hurricane deductibles can be 2-10% of your home’s insured value, meaning a $400,000 home could have a deductible of $8,000 to $40,000.
The Florida insurance market has become increasingly volatile, with many national carriers reducing their presence. This makes it crucial to work with knowledgeable local professionals who understand the evolving market and can help you find the right protection.
For more information on related topics, you can explore these resources:
- homeowners insurance in pinellas county florida
- best homeowners insurance in florida 2025
- top 10 homeowners insurance companies in florida
Understanding Your Homeowners Insurance Coverage in Palm Harbor
Your Palm Harbor home is a significant financial investment, and home insurance palm harbor fl is its primary shield. A standard homeowners policy (typically an HO-3) bundles multiple coverages to protect your property and financial well-being. Understanding these components is key to ensuring you are not underinsured when disaster strikes.
Standard Policy Coverages
A comprehensive policy includes several distinct protections:
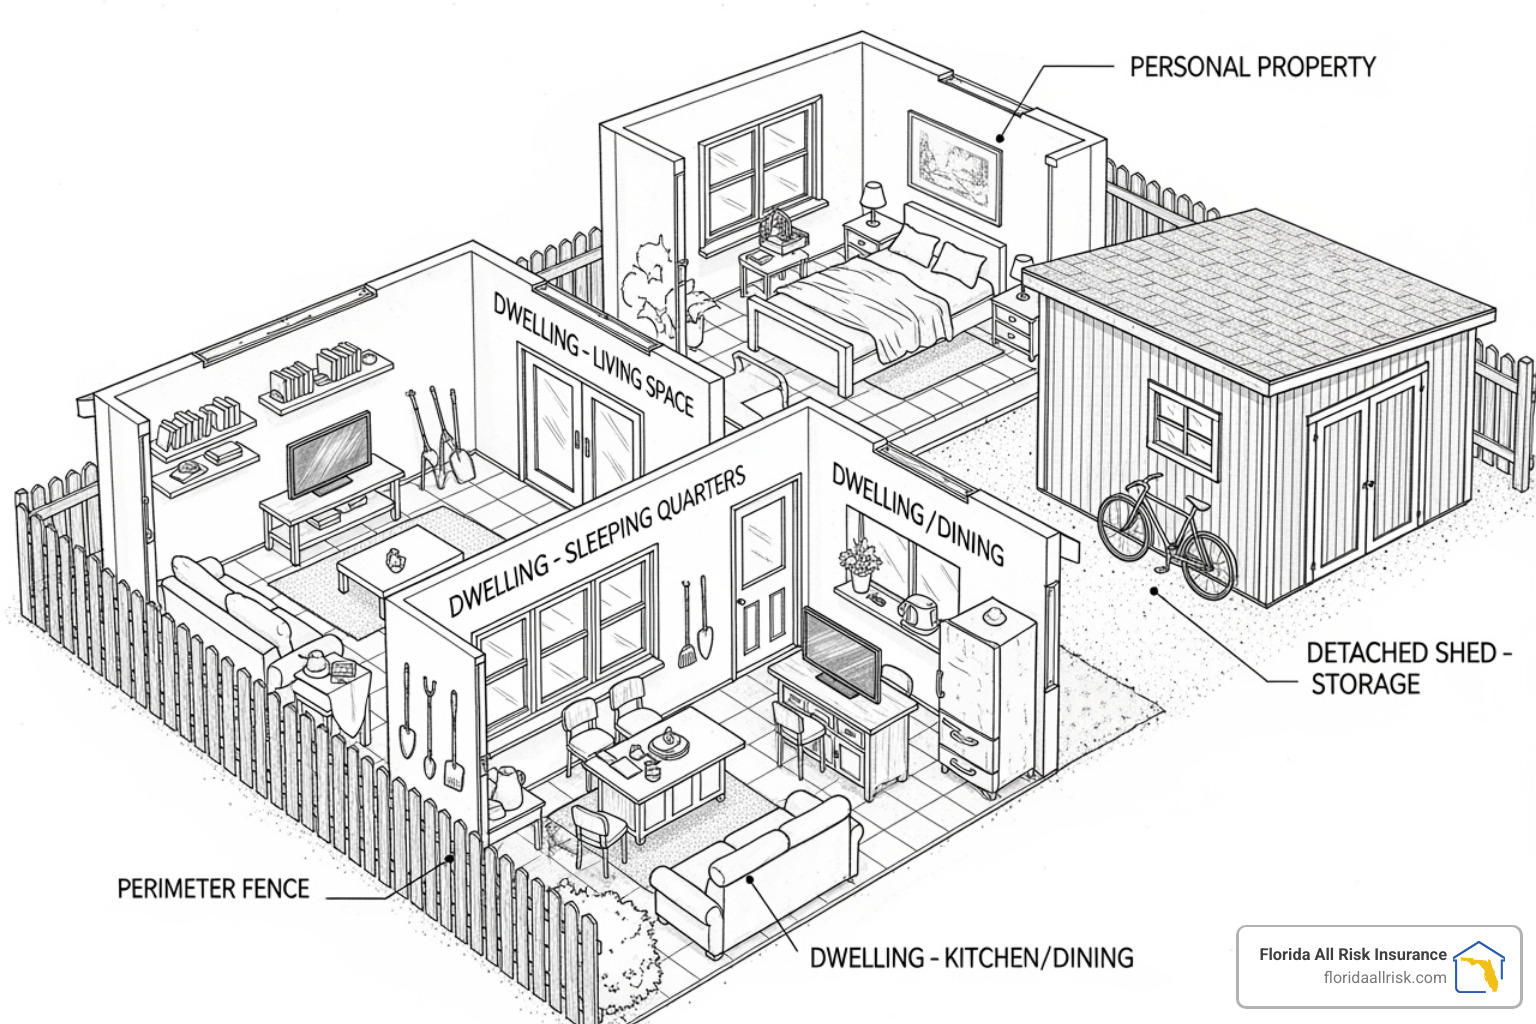
Dwelling Coverage: This protects the physical structure of your home, from the foundation to the roof. The coverage amount should reflect the cost to completely rebuild your home, not its market value. With construction costs fluctuating in Florida, review this amount regularly to avoid being underinsured.
Other Structures: This covers structures on your property not attached to the main house, like a detached garage, shed, or fence. It’s typically set at 10% of your dwelling coverage, but this limit can often be increased if needed.
Personal Property: This protects your belongings—furniture, clothes, electronics—against perils like fire, theft, and windstorm damage. You must choose between Replacement Cost (pays to replace items with new ones) and Actual Cash Value (pays the depreciated value). Replacement Cost coverage is highly recommended as it better allows you to replace what you’ve lost.
Personal Liability Protection: This is your financial shield if someone is injured on your property or you accidentally cause damage elsewhere. It covers medical bills, legal fees, and potential judgments.
Additional Living Expenses (Loss of Use): If your home becomes uninhabitable due to a covered loss, this pays for temporary living costs like hotel bills and restaurant meals that exceed your normal expenses.
Medical Payments to Others: This covers minor medical expenses for guests injured on your property, regardless of fault, helping to avoid larger liability claims.
For more details on these coverages, see our guide on Homeowners Insurance Florida.
Common Policy Types Available
While the HO-3 is most common, other types serve different needs:
- HO-3 (Special Form): The standard for single-family homes. It offers “open perils” coverage for the dwelling (protecting against all losses except those specifically excluded) and “named perils” for personal property (protecting only against listed dangers).
- HO-5 (Comprehensive Form): Offers broader protection by providing “open perils” coverage for both your dwelling and personal property.
- HO-6 (Condo Insurance): Designed for condo owners, this “walls-in” policy covers your unit’s interior, personal belongings, and liability, supplementing the condo association’s master policy.
- HO-4 (Renters Insurance): Protects a renter’s personal property and provides liability coverage.
Learn more about local needs on our Homeowners Insurance in Pinellas County Florida page.
What Standard Policies Typically Exclude
Knowing what your home insurance palm harbor fl policy doesn’t cover is critical. Common exclusions include:
- Flood Damage: Standard policies never cover damage from flooding, whether from storm surge, heavy rain, or a broken water main. This requires a separate policy.
- Sinkhole Damage: Given Pinellas County’s geology, this is a key exclusion. Comprehensive sinkhole protection requires a special endorsement.
- Termite and Pest Damage: Considered a maintenance issue, damage from insects or rodents is not covered.
- Wear and Tear: Insurance is for sudden and accidental events, not for gradual deterioration or damage from deferred maintenance.
- Earthquake Damage & Intentional Damage: These are also standard exclusions.
Understanding these exclusions is vital in the current market. Learn more about recent challenges on our page about Another Home Insurance Company Leaving Florida.
The Critical Difference: Homeowners vs. Flood & Windstorm Insurance
In a coastal community like Palm Harbor, it’s a dangerous misconception that a standard homeowners policy covers all storm-related damage. In reality, you need separate or specific coverage for the most common catastrophic events in Florida: flooding and hurricane winds.
Why Every Palm Harbor Homeowner Needs Flood Insurance
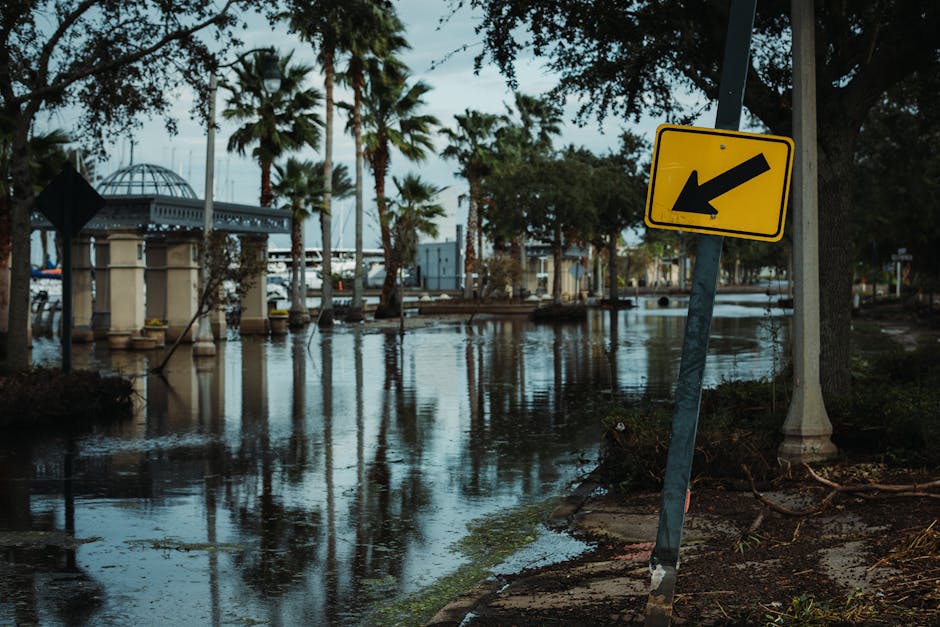
A standard homeowners policy will not pay for flood damage, regardless of the source. This includes heavy rain, overflowing rivers, or hurricane storm surge, which presents the greatest risk to Palm Harbor. Storm surge can push feet of ocean water miles inland, flooding homes that have never been affected before.
If you have a mortgage on a property in a high-risk flood zone, federal law requires you to carry flood insurance. Even if not required, it’s a wise investment. Most flood insurance is provided through the government-backed National Flood Insurance Program (NFIP), but private flood insurance companies are also an option, sometimes offering more competitive rates or better coverage.
To begin, check your property’s flood risk on the FEMA Flood Map Service Center. Flood maps and weather patterns change, so don’t assume you’re safe just because you haven’t flooded before. We’ve helped homeowners understand these risks across Florida, including areas like Home Insurance Santa Rosa Beach FL.
Understanding Hurricane & Windstorm Deductibles
While your policy includes windstorm coverage, it comes with a separate, much higher deductible for hurricane damage. Unlike your standard flat-dollar deductible, a hurricane deductible is percentage-based, calculated from your home’s insured value.
For example, on a home insured for $400,000:
- A 2% hurricane deductible means you pay the first $8,000 of damage.
- A 5% deductible means you pay the first $20,000.
Choosing a higher deductible lowers your premium but increases your out-of-pocket cost after a storm. Some policies apply this deductible once per calendar year, while others apply it per named storm, which can be costly in an active season. The deductible is typically triggered when a named tropical storm or hurricane warning is issued for your area. This system helps keep policies available and affordable despite Florida’s high risk of catastrophic wind damage.
Decoding the Cost of Home Insurance Palm Harbor FL
Florida’s insurance market is the most expensive in the nation, and Palm Harbor is no exception. Annual premiums often range from $3,000 to $4,000, far exceeding the national average. This is driven by the state’s high risk of catastrophic weather. Understanding the factors that influence your premium is the first step toward managing these costs.

Key Factors That Influence Your Premiums
Insurers assess numerous factors to determine your home’s risk profile and calculate your premium:
- Location: Proximity to the coast significantly increases premiums due to higher hurricane and storm surge risk.
- Age and Construction: Newer homes built to modern codes and those with concrete block (CBS) construction are less risky and cheaper to insure than older, wood-frame homes.
- Roof Age and Shape: A newer roof (under 15 years old) is crucial. Hip roofs, which slope on all four sides, are more wind-resistant than gable roofs and earn significant discounts.
- Replacement Cost: This is the cost to rebuild your home from scratch, not its market value. Higher replacement costs lead to higher premiums.
- Claims History: A history of filing claims can lead to higher rates.
- Credit-Based Insurance Score: Insurers use a specialized score to predict risk. A better score can result in lower premiums.
- Protective Devices: Monitored security systems, smoke detectors, and hurricane shutters can qualify you for discounts.
For more on market trends, see our guide on Florida Homeowners Insurance 2025.
How to Lower Your Home Insurance Palm Harbor FL Premiums
While rates are high, you can take steps to lower your premium:
- Wind Mitigation Inspection: This is the single biggest opportunity for savings. An inspection that verifies wind-resistant features (e.g., strong roof attachments, impact-rated windows) can lead to substantial discounts.
- Raise Your Deductible: Choosing a higher deductible lowers your annual premium, but ensure you can afford the out-of-pocket cost if you need to file a claim.
- Bundle Policies: Insuring your home and auto with the same carrier usually results in a multi-policy discount.
- Improve Home Safety: Installing monitored security and fire alarm systems can earn you discounts.
- Maintain Good Credit: A strong credit history can positively impact your insurance score and lower your rates over time.
- Work with an Independent Agent: An independent agent can shop multiple carriers to find the best combination of coverage and price for your specific needs.
Explore more savings strategies on our Best Homeowners Insurance in Florida 2025 page.
The Practicalities: Quotes, Claims, and Extra Protection
Once you understand the coverage and costs, it’s time to handle the logistics. From getting a quote to filing a claim, being prepared makes the process smoother.
Is Homeowners Insurance Mandatory in Florida?
While Florida does not have a state law requiring homeowners insurance, it is a practical necessity. If you have a mortgage, your lender will require you to maintain a policy to protect their financial interest in the property. If your policy lapses, the lender can purchase insurance on your behalf, which is often more expensive and less comprehensive.
Even if you own your home outright, insurance is vital for protecting your equity. A single disaster like a hurricane or fire could wipe out your largest financial asset, forcing you to pay for rebuilding out of pocket. Insurance provides essential financial security and peace of mind. For more on regional requirements, see our page on Homeowners Insurance Weston FL.
Getting an Accurate Home Insurance Quote in Palm Harbor, FL
To get an accurate quote for home insurance palm harbor fl, you’ll need to provide specific details about your property and personal information. The more complete the information, the more accurate the quote.
Information Needed for a Quote:
- Property Details: Address, year built, square footage, and construction type (e.g., concrete block vs. wood frame).
- Roof Information: The age, material (shingle, tile, metal), and shape (hip vs. gable) of your roof are critical factors.
- Personal Information: Your date of birth is needed to generate a credit-based insurance score, which significantly impacts rates.
- Coverage Needs: Desired coverage limits for your dwelling and personal property, as well as your preferred deductible amounts.
- Insurance History: Any prior claims history will be considered.
An independent agent uses this information to compare options from multiple carriers, finding the best fit for your needs and budget.
How to File a Claim and Steer the Aftermath
No one wants to file a claim, but knowing the steps can reduce stress during a difficult time.
- Prioritize Safety: Ensure everyone is safe. If the home is hazardous, evacuate and call emergency services.
- Document the Damage: Take extensive photos and videos of all damage to the structure and your personal belongings before making any repairs.
- Contact Your Agent: Call your insurance agent immediately. They are your advocate and will guide you through the process and help initiate the claim with the carrier.
- Make Temporary Repairs: Take steps to prevent further damage, such as tarping a roof. Keep all receipts, as these costs are typically reimbursable. Do not make permanent repairs until an adjuster has assessed the damage.
- Keep Detailed Records: Log all communications with your insurance company, including dates, names, and conversation summaries.
- Work with the Adjuster: Be prepared to show the adjuster the damage and provide your documentation.
For more on preparing for severe weather, visit Learn more about hurricane preparedness at Ready.gov.
When to Consider an Umbrella Policy for Extra Liability
An umbrella policy provides extra liability protection that extends beyond the limits of your standard homeowners policy. It’s a cost-effective way to protect your assets from a major lawsuit.
Consider an umbrella policy if your net worth (home equity, savings, investments) exceeds your current liability limits. Features like a swimming pool, trampoline, or even a dog can increase your liability risk. If a serious accident occurs on your property and a lawsuit exceeds your policy limits, your personal assets could be at risk. An umbrella policy covers that gap, providing an additional layer of financial security. This coverage also typically extends to incidents involving your vehicles and other situations away from home. For more on protecting your assets, see our services for areas like Homeowners Insurance Pembroke Pines FL.
Frequently Asked Questions about Home Insurance in Palm Harbor
Here are straightforward answers to some of the most common questions we hear from Palm Harbor homeowners.
Why is home insurance so expensive in Palm Harbor and the rest of Florida?
Florida’s high insurance costs are driven by several factors. The primary reason is the significant risk of hurricanes, which leads to frequent and costly claims. This increases the cost of reinsurance (insurance for insurance companies), which is passed on to consumers. A litigious environment, insurance fraud, and rising construction and labor costs also contribute to Florida having the highest premiums in the nation, with Palm Harbor rates often ranging from $3,000 to $4,000 annually.
Do I need sinkhole coverage in Palm Harbor?
Pinellas County has moderate sinkhole activity, and this type of damage is not covered by a standard homeowners policy. While most policies include limited “Catastrophic Ground Cover Collapse” coverage for severe incidents, it is very restrictive. For broader protection against sinkhole damage, you must purchase a separate endorsement. Given the local geology, it is wise to discuss this optional coverage with your agent to determine if it’s right for you.
How often should I review my home insurance policy?
You should review your policy at least once a year at renewal time. It is also crucial to review it after any significant life changes (like a marriage or new baby) or major home improvements (like a kitchen remodel or adding a pool). Updating your policy ensures your coverage limits for dwelling, personal property, and liability remain adequate for your current situation, preventing dangerous gaps in protection.
Your Partner in Protecting Your Palm Harbor Home
Securing the right home insurance palm harbor fl doesn’t have to be a complicated process. The key is finding a policy that truly protects what matters most to you. Your home is your sanctuary and your biggest financial investment, and it deserves coverage that works when you need it most.
Working with an independent insurance agency like Florida All Risk Insurance provides a significant advantage: choice. Unlike captive agents who represent a single company, we have relationships with multiple carriers. This allows us to compare policies side-by-side to find the best balance of comprehensive coverage and affordable cost for you.
The Florida insurance market is challenging, with rising rates and fewer carriers. Our deep understanding of Florida’s unique risks means we can steer this landscape to find excellent options for our clients. We don’t just sell you a policy; we explain the details so you can make an informed decision. You’re not just getting insurance—you’re getting a local team that understands Palm Harbor’s challenges and is here to support you.
Contact Us
Florida All Risk Insurance
Address:
Saint Petersburg, FL
Phone:
(727) 522-6677
Email:
[email protected]
About Us | Testimonials | Blog

