

Protecting Your Okeechobee Home: Insurance Essentials
If you’re looking for home insurance Okeechobee FL providers, here’s what you need to know:
| Top Local Home Insurance Providers in Okeechobee | Contact Information | Key Offerings |
|---|---|---|
| Florida All Risk Insurance | (863) 467-0600 | Multi-carrier quotes, flood insurance, windstorm coverage |
Home insurance Okeechobee FL is essential for protecting your most valuable asset in a region vulnerable to unique weather risks. Located near Lake Okeechobee and in hurricane territory, homes here face distinctive challenges that require specialized coverage beyond standard policies. The average Florida homeowner pays approximately $2,000 annually for coverage, though Okeechobee rates may vary based on proximity to water, construction type, and home age.
Standard homeowners policies in Okeechobee typically don’t cover flood damage, which requires separate coverage through the National Flood Insurance Program or private insurers. With Florida’s hurricane season lasting six months each year, understanding your policy’s wind damage provisions is crucial for complete protection.
I’m Jason Miller, a second-generation insurance professional with over 20 years of experience providing home insurance Okeechobee FL solutions through Florida All Risk Insurance, helping thousands of local homeowners find the right coverage at competitive rates.
Home insurance okeechobee fl terms simplified:
- best homeowners insurance in florida 2025
- another home insurance company leaving florida
- homeowners insurance in pinellas county florida
Understanding home insurance Okeechobee FL Basics
When you own a home in Okeechobee, insurance isn’t just another monthly bill—it’s your financial safety net when the unexpected happens. Living in this beautiful lakeside community comes with unique challenges that make proper coverage not just smart, but essential.
Your home insurance Okeechobee FL policy works as a shield between your family’s financial security and potential disaster. Without it, a single storm, fire, or accident could wipe out years of hard work and savings.
“I’ve seen how proper insurance makes the difference between a temporary setback and financial devastation,” says Juan Duque, a local insurance expert. “For Okeechobee homeowners, good coverage isn’t a luxury—it’s a necessity.”
What is “home insurance okeechobee fl” and why every resident needs it?
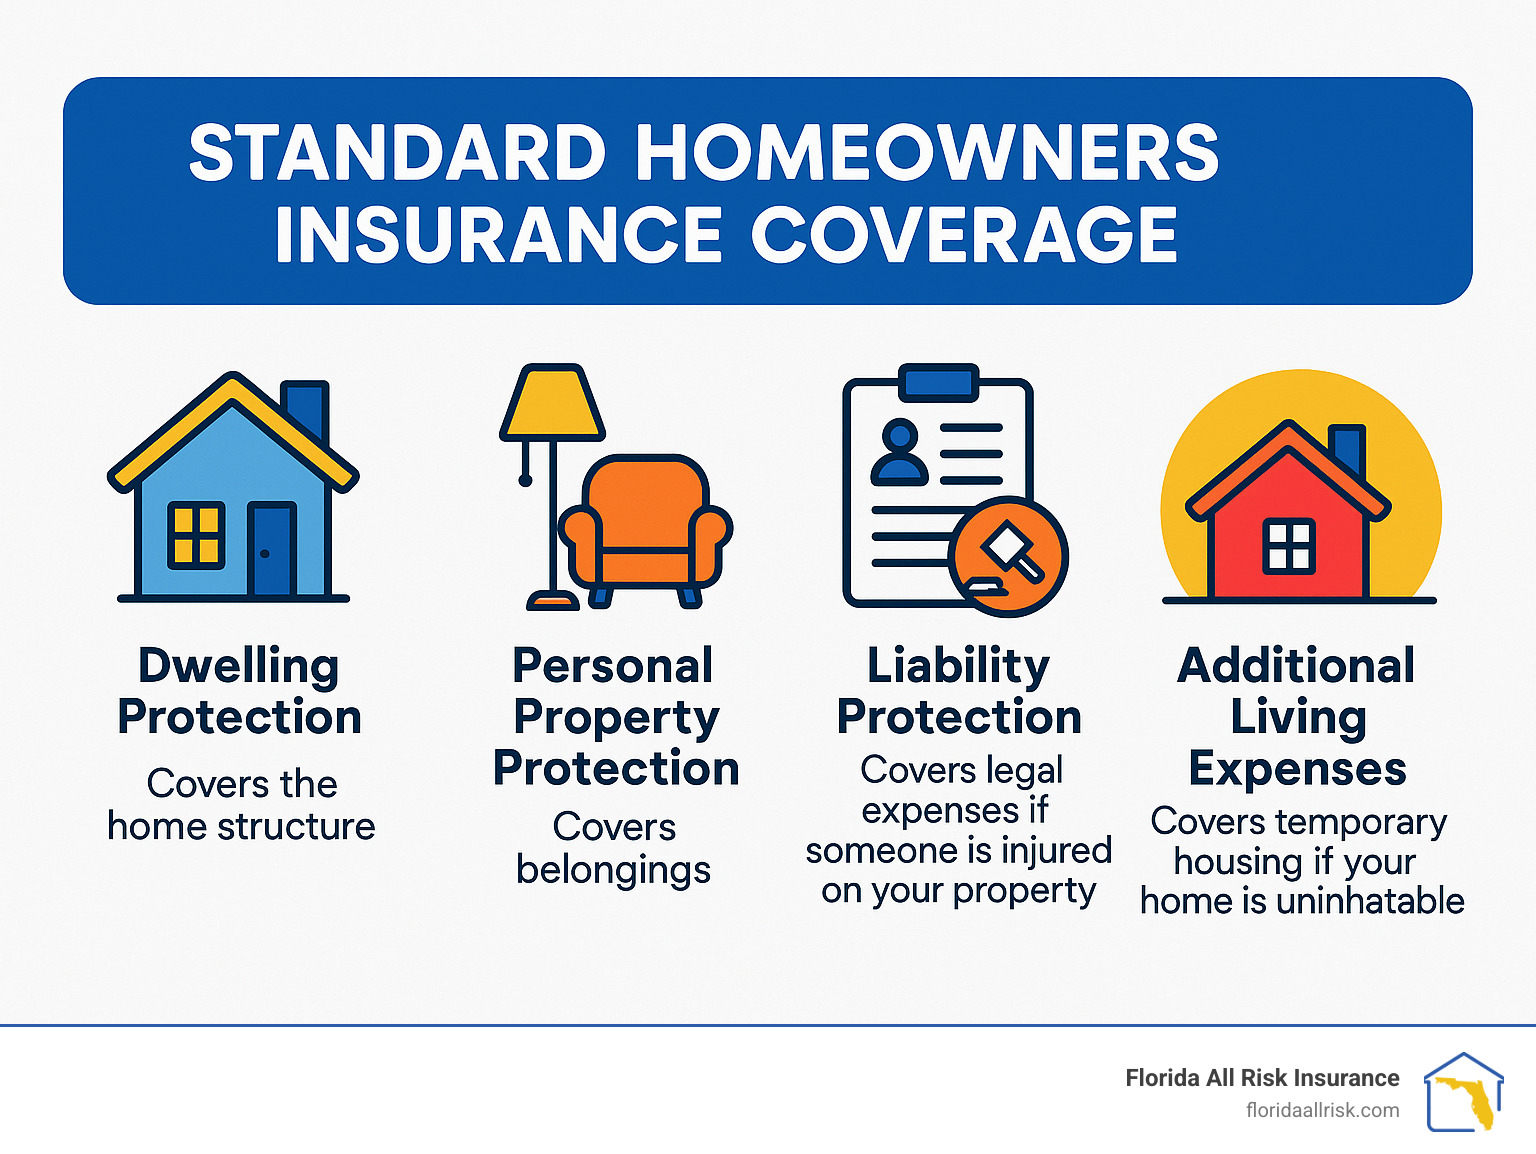
At its core, home insurance Okeechobee FL is a custom protection package designed specifically for the unique risks our community faces. Standard policies typically protect your:
Dwelling – This covers the actual structure of your home if it’s damaged by covered events like fire or windstorms. For Okeechobee homes, this is particularly important given our exposure to severe weather.
Personal property – From furniture and electronics to clothing and kitchenware, this coverage helps replace your belongings after a covered loss.
Liability protection – If someone gets injured on your property and sues, this coverage helps with legal expenses and potential settlements.
Loss of use – Should your home become temporarily uninhabitable after a covered event, this helps cover additional living expenses while repairs are made.
While Florida law doesn’t technically require homeowners insurance, mortgage lenders invariably do. And even if you own your home outright, going without coverage leaves your most valuable asset completely exposed to disaster.
Key reasons Okeechobee’s location raises the stakes
Living near Lake Okeechobee creates unique insurance considerations that homeowners simply can’t ignore:
Our hurricane vulnerability puts every home at risk during storm season. Even a relatively “minor” Category 1 hurricane can tear off roofing, damage siding, and cause significant structural problems. Your home insurance Okeechobee FL policy needs specific provisions to address these wind risks.
Proximity to Lake Okeechobee means flooding is a real concern. As one insurance professional notes, “Just a few inches of water can cause tens of thousands in damage to Florida homes.” Standard policies typically exclude flood damage, making supplemental coverage crucial for lakeside properties.
Many parts of Okeechobee County have longer emergency response times due to their rural nature. This can increase the extent of fire damage before help arrives, making comprehensive fire coverage especially important.
Our unique environmental factors, from sinkholes to severe thunderstorms, create insurance challenges that require specialized knowledge and coverage options.
What a Standard Policy Covers & What It Doesn’t
Buying home insurance Okeechobee FL can feel like navigating a maze of insurance jargon. Let’s break down what’s actually covered (and what isn’t) in plain English, so you know exactly what protection you’re getting for your money.
Your standard homeowners policy is like a protective umbrella with six main sections of coverage. First, there’s Dwelling Coverage (Coverage A), which protects the actual structure of your home and attached structures like your garage. For Okeechobee homeowners, this should be based on replacement cost, not what you paid or the current market value.
Next comes Other Structures (Coverage B), covering those detached buildings on your property—your garden shed, fence, or that workshop you built last summer. This is typically set at about 10% of your dwelling coverage.
Your belongings get protection through Personal Property (Coverage C). This covers everything from your furniture to your clothes to your kitchen appliances—usually at 50-70% of your dwelling amount. If disaster strikes and you can’t live in your home, Loss of Use (Coverage D) steps in to cover hotel stays, restaurant meals, and other expenses while your home is being repaired.
Personal Liability (Coverage E) might be the most underrated coverage—it protects you financially if someone gets hurt on your property or you accidentally damage someone else’s property. While standard coverage starts at $100,000, most Okeechobee homeowners should consider higher limits given our litigious society.
Rounding things out is Medical Payments (Coverage F), which handles smaller medical bills for guests injured on your property, regardless of who’s at fault—typically $1,000-$5,000 in coverage.
Now for the reality check—what’s NOT covered:
| Covered Perils | Excluded Perils |
|---|---|
| Fire and smoke | Flooding |
| Lightning strikes | Earth movement/sinkholes |
| Windstorm damage (with limitations) | Mold (beyond limited coverage) |
| Theft | Termite/pest damage |
| Vandalism | Wear and tear |
| Falling objects | Neglect |
| Weight of ice/snow | War or nuclear hazards |
| Sudden water damage from plumbing | Intentional loss |
Standard policies don’t cover flood damage, earth movement (including those Florida sinkholes), most mold issues, termite damage, normal wear and tear, or damage from neglect. High-value items like jewelry or art typically have limited coverage unless specifically scheduled.
Does a standard policy include flood or windstorm losses?
Here’s a critical fact that surprises many Okeechobee homeowners: standard homeowners insurance policies do not cover flood damage. This exclusion is particularly important for homes near Lake Okeechobee or in designated flood zones.
As one local agent put it, “I’ve seen too many homeowners devastated to learn their policy doesn’t cover rising water after a heavy rain event.” For flood protection, you’ll need a separate policy through the National Flood Insurance Program (NFIP) or a private flood insurer.
Regarding windstorm coverage, the situation is a bit more nuanced for Okeechobee residents. Standard policies typically include wind damage, but with some important asterisks:
Most Florida policies have separate hurricane deductibles that are percentage-based (usually 2-5% of your dwelling coverage) rather than a flat amount. This means if you have a $300,000 home with a 2% hurricane deductible, you’d pay the first $6,000 of hurricane damage before insurance kicks in.
Some high-risk areas may even require separate wind-only policies, and certain types of wind damage might have coverage limitations. As one Okeechobee insurance professional notes, “Even homes in the same neighborhood can have different risk profiles when it comes to wind exposure.”
What about valuable items and outbuildings?
That diamond engagement ring? Your grandfather’s coin collection? Your professional camera equipment? A standard home insurance Okeechobee FL policy includes some coverage for these items, but with strict limits—typically $1,000-$2,500 per category.
For valuable items that exceed these sublimits, you’ll need additional “scheduled personal property” coverage. This means individually listing these items on your policy, often with appraisals to document their value. It costs a bit more, but provides broader protection with no deductible for these specific items.
Your standard policy does include coverage for outbuildings (typically 10% of your dwelling coverage). This protects detached garages, storage sheds, gazebos, fences, and workshops. However, there’s an important caveat for many Okeechobee residents—structures used for business purposes or farming likely won’t be adequately covered under a standard homeowners policy.
If you have farm outbuildings, barns, or equipment storage, you should talk with your agent about specialized farm or ranch coverage. As one local puts it, “Your homeowners policy is designed for residential risks, not agricultural ones—there’s a big difference in coverage needs.”
Understanding these coverage details isn’t just insurance minutiae—it’s about making sure your Okeechobee home and belongings have the protection they deserve when the unexpected happens.
Florida Rules: Is Homeowners Insurance Required?
Navigating Florida’s insurance requirements can feel like a maze, but I’m here to help Okeechobee homeowners understand what’s truly necessary. While Florida doesn’t technically force you to insure your home by law, the reality is a bit more nuanced.
Must you carry “home insurance okeechobee fl” by law?
Here’s the straightforward truth – Florida state law doesn’t explicitly require you to have home insurance Okeechobee FL if you own your property free and clear. But before you consider going without coverage, understand that several factors effectively make insurance a necessity for most homeowners:
Most importantly, if you have a mortgage (as most homeowners do), your lender will absolutely require insurance coverage. This isn’t just them being cautious – they’re protecting their investment in your property.
“While homeowners insurance isn’t mandated by Florida law, your mortgage lender won’t give you a choice in the matter,” explains Jason Miller of Florida All Risk Insurance. “They need to know their collateral – your home – is protected against disaster.”
Similarly, if you live in a community with a homeowners association, your HOA covenant likely requires certain minimum insurance levels. These requirements are legally binding once you’ve signed your HOA agreement.
For condo owners, you’ll need an HO-6 policy (condo insurance) that works alongside your association’s master policy. And if you own a mobile or manufactured home in Okeechobee, specialized mobile home insurance is essential, as these structures face unique risks.
Even without these requirements, going without coverage in Okeechobee is like swimming in Lake Okeechobee during storm season – technically possible, but extremely risky. One hurricane or serious fire could wipe out your life savings without proper protection.
How hurricane deductibles work in Florida
Florida’s approach to hurricane deductibles is unique and particularly important for Okeechobee residents to understand:
Unlike your standard deductible (typically a flat amount like $1,000), hurricane deductibles are calculated as a percentage of your home’s insured value – usually between 2-5%. This makes a significant difference in what you’ll pay out-of-pocket after a storm.
For example, if your home insurance Okeechobee FL policy covers your house for $300,000 with a 2% hurricane deductible, you’d be responsible for the first $6,000 in hurricane damage before your insurance kicks in. That’s considerably more than a typical $1,000 standard deductible!
The good news is that hurricane deductibles apply just once per calendar year, not per storm. So if you’re unfortunate enough to face multiple named storms in one season (which has happened before in Florida), you’d only pay that percentage deductible once.
“Many Okeechobee homeowners are caught off guard by their hurricane deductible when they file their first claim,” notes Miller. “We recommend setting aside your deductible amount in an emergency fund before storm season begins.”
Your hurricane deductible is officially triggered when the National Weather Service declares a hurricane watch or warning for any part of Florida and remains in effect until 72 hours after the last warning is lifted. Florida law also requires insurers to clearly explain these deductibles and provide examples in your policy documents.
For Okeechobee residents living near the lake or in flood-prone areas, understanding these deductibles is essential for your financial well-being. A smart approach is to contact your agent seasonally to review your coverage – especially before hurricane season begins in June.
What Drives Your Premium in Okeechobee?
When it comes to home insurance Okeechobee FL rates, several factors unique to our region affect what you’ll pay. Understanding these can help you make smart decisions about your coverage and potentially save money.
Your home’s age plays a major role in determining your premium. Older homes often come with higher insurance costs due to outdated building materials and systems. If your home was built before 2002, when Florida updated its building codes, you might be looking at significantly higher premiums than your neighbors with newer homes.
“The age of your roof and the material it’s made from can make a dramatic difference in what you pay each month,” explains a local insurance agent. Metal roofs, with their superior wind resistance, often qualify for substantial discounts compared to traditional shingle roofs. A brand-new tile roof might slash your rates compared to that 15-year-old shingle roof that’s seen better days.
Your home’s construction type matters too, especially in hurricane-prone Okeechobee. CBS (Concrete Block Structure) homes typically enjoy better rates than wood-frame houses because they stand up better to our strong Florida winds.
Living near beautiful Lake Okeechobee comes with perks, but proximity to water affects both your flood risk and windstorm exposure. Homes closer to the lake often face higher premiums to account for this increased risk.
Your claims history follows you like a shadow. Both your personal history of filing claims and the claims history for your specific property can significantly impact rates. As one Okeechobee agent puts it, “We’ll always have your back when you need to file a claim, but multiple claims can lead to higher premiums down the road.”
Even your credit score plays a part. In Florida, insurers can use credit-based insurance scores to set premiums, with better credit typically translating to lower rates.
Typical cost range & latest averages
While the average Florida homeowner pays around $2,000 annually for insurance, Okeechobee rates vary widely based on the factors we’ve discussed. Depending on your specific situation, you might see premiums closer to:
- $1,800-$2,200 for newer homes (built after 2002) with wind mitigation features
- $2,500-$3,500 for older homes without wind mitigation
- $3,000-$4,500 for homes very close to Lake Okeechobee or with previous water damage claims
These figures represent just your base homeowners policy. Flood insurance—which is separate and essential for many Okeechobee residents—typically adds another $500-$1,500 annually depending on your flood zone and elevation.
“Shopping for insurance can be overwhelming, but our staff does the heavy lifting for you,” notes a local agent. Working with an independent agency like Florida All Risk Insurance allows you to compare multiple carriers at once, often finding better coverage at lower rates than you’d find on your own.
Wind-mitigation features that save money
Making your home more hurricane-resistant isn’t just about safety—it can significantly reduce your home insurance Okeechobee FL premiums too.
A hip roof design, where all sides slope downward, performs much better in high winds than traditional gable roofs. If you’re due for a roof replacement, considering this design change could pay for itself through insurance savings over time.
Impact-resistant windows and doors might seem expensive upfront, but they can withstand flying debris during storms and often qualify for premium discounts of 10-15%. Similarly, installing hurricane straps or clips to secure your roof to your walls prevents the catastrophic damage that occurs when roofs lift during storms.
“Wind-resistant home features directly translate into premium savings,” says one Okeechobee agent. “Some of my clients have cut their premiums by 25% or more after making these improvements.”
Secondary water resistance—a special underlayment beneath your roof covering—provides extra protection if your shingles get damaged. Reinforced garage doors are another smart investment since garage doors are typically the first point of failure during hurricanes.
The key to capturing these savings is getting a formal wind mitigation inspection by a licensed inspector. This documentation proves to insurance companies that your home is better equipped to withstand storms, potentially saving hundreds or even thousands on your annual premiums.
Even if you’re not planning major renovations, ask your agent about which smaller improvements might qualify for discounts. Sometimes even modest changes can lead to meaningful savings on your home insurance Okeechobee FL policy.
Beyond the Basics: Extra Protection Worth Considering
When it comes to protecting your Okeechobee home, standard coverage often falls short of addressing the unique risks we face in this region. As your neighbors and fellow Floridians, we understand that peace of mind comes from knowing you’re fully protected against everything Mother Nature might throw our way.
Flood insurance explained for Okeechobee addresses
If there’s one additional coverage Okeechobee homeowners simply can’t afford to skip, it’s flood insurance. With our community nestled near Lake Okeechobee and vulnerable to Florida’s notorious downpours, flood protection isn’t optional—it’s essential.
“I’ve seen families lose everything because they assumed their regular policy covered flooding,” shares Maria Sanchez, a local claims adjuster. “The heartbreak on their faces when they learn standard homeowners insurance doesn’t cover a single penny of flood damage is something I’ll never forget.”
Your flood risk in Okeechobee depends largely on your FEMA flood zone designation. Properties in zones beginning with “A” or “V” face higher risks and often require mandatory flood insurance if you have a mortgage. But here’s the reality check—more than 20% of flood claims come from properties in “X” zones, which are considered lower-risk. In Okeechobee, water doesn’t read flood maps.
An elevation certificate can be your financial lifesaver, potentially saving you hundreds annually on flood premiums by documenting exactly how high your home sits above the base flood elevation. The higher your home sits, the lower your risk—and your premium.
When shopping for flood coverage, you’ll typically choose between:
- Building coverage (protecting your home’s structure)
- Contents coverage (protecting your belongings)
- Additional living expenses (if you need temporary housing)
The National Flood Insurance Program (NFIP) offers coverage up to $250,000 for your dwelling and $100,000 for contents, while private flood insurers might offer higher limits and potentially lower rates depending on your situation.
Most flood policies have a 30-day waiting period before they take effect—so don’t wait until you see storm clouds gathering. As one client recently told us, “The $700 I spend annually on flood insurance seemed expensive until my neighbor without it had to come up with $78,000 out-of-pocket after last year’s storms.”
For more comprehensive information about Florida flood coverage options, visit Florida All Risk’s homeowners insurance page.
Windstorm & hurricane add-ons
While your standard home insurance Okeechobee FL policy includes wind coverage, the reality of living in hurricane territory often demands stronger protection.
Citizens wind-only policies might become necessary if you live in particularly high-risk areas where standard carriers won’t provide wind coverage. While Citizens is Florida’s insurer of last resort, their specialized wind policies can provide crucial protection when other options aren’t available.
Roof coverage improvement is worth every penny in Okeechobee. Standard policies increasingly cover older roofs at depreciated “actual cash value” rather than “replacement cost.” The difference? On a 15-year-old roof, you might get $4,000 for repairs that actually cost $15,000. Improved roof coverage eliminates this gap.
After Hurricane Irma, many Okeechobee homeowners were shocked by the cost of debris removal. Standard policies typically offer limited coverage for this expense—usually 5% of your dwelling coverage. Improved debris removal coverage increases these limits, preventing out-of-pocket expenses when you’re already dealing with storm recovery.
Ordinance or law coverage becomes critical if your older home suffers substantial damage. When rebuilding, local building codes will require you to meet current standards—which can increase rebuilding costs by 25-50%. Without this coverage, you’ll pay that difference yourself.
“When we upgraded our policy to include improved hurricane protection, it added about $120 to our annual premium,” shares Tom Wilson, an Okeechobee homeowner. “After last year’s close call with Hurricane Ian, I sleep better knowing we have the extra coverage.”
Some carriers offer exclusive add-ons like Better Roof Replacement® that automatically upgrade your roof to more wind-resistant materials after a covered loss—particularly valuable in our hurricane-prone region.
Smart Ways to Lower Your Premium Today
Despite Florida’s rising insurance costs, there are plenty of ways to trim your home insurance Okeechobee FL premium without sacrificing quality protection. With some strategic choices and home improvements, you can potentially save hundreds of dollars annually.
Discounts available locally
The good news? Local insurance providers offer numerous discounts that can significantly reduce what you pay for home insurance Okeechobee FL.
One of the simplest ways to save is by bundling your policies. When you combine your home and auto insurance with the same carrier, you’ll typically save 10-15% on both policies. As Sarah, one of our local Okeechobee agents, tells clients: “Bundling is like buying in bulk at the grocery store—you get more for less.”
If you’ve gone claim-free for several years, don’t be shy about mentioning it! Homeowners without claims for 3-5 years often qualify for reduced rates of 5-10%. Your good track record deserves recognition.
For our more mature homeowners, many carriers offer special senior citizen discounts for those over age 55. These discounts acknowledge your experience and typically more responsible home maintenance habits.
Protecting your home with a monitored security system doesn’t just provide peace of mind—it can also reduce your premiums by 5-10%. Insurance companies appreciate when you take steps to prevent theft and fire damage.
The wind mitigation discounts we discussed earlier can save you 15-40% on the wind portion of your premium, which is substantial in hurricane-prone Okeechobee.
Newer homes often qualify for lower rates, as do loyal customers who’ve stayed with the same insurer for multiple years. At Florida All Risk Insurance, we work with multiple carriers to ensure you receive every discount you qualify for, often finding savings that single-carrier agents might miss.
How to earn savings before your next renewal
Beyond standard discounts, making strategic improvements to your home can generate substantial premium reductions before your next renewal date.
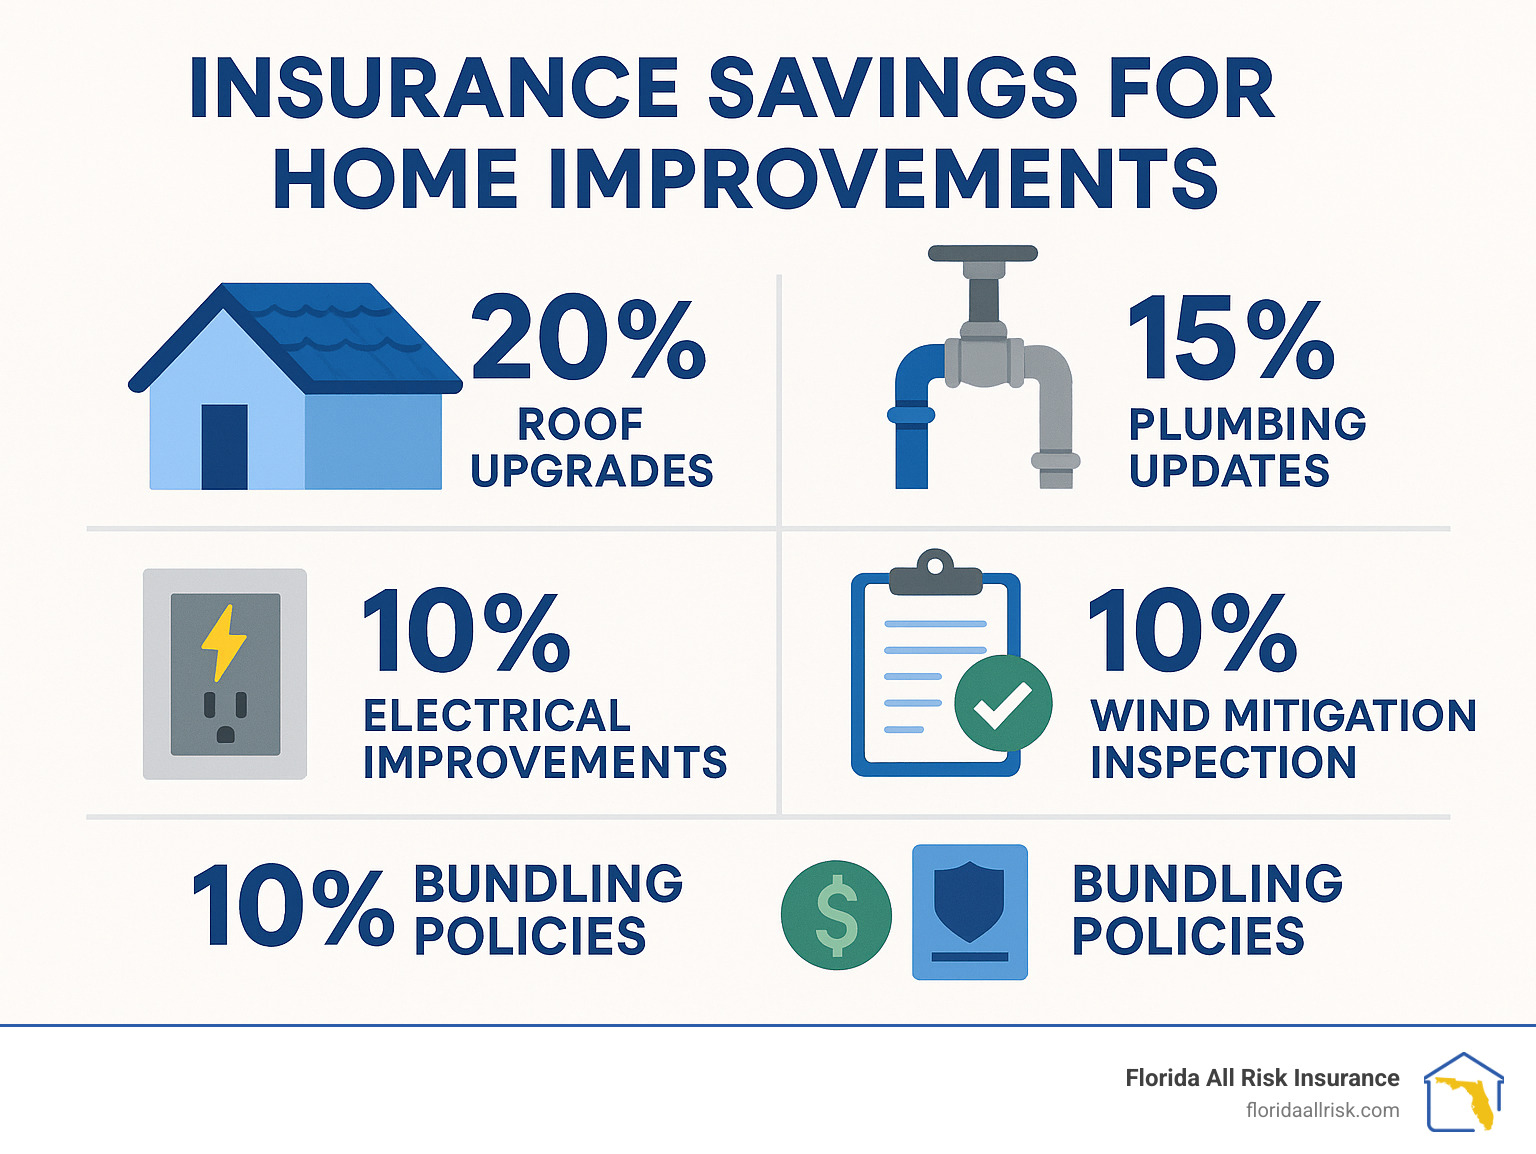
Roof upgrades offer perhaps the biggest potential savings. Replacing an older roof with a new, wind-resistant one can dramatically lower premiums—sometimes by 20% or more. Metal roofs, in particular, often qualify for significant discounts because of their durability during storms.
“A new roof isn’t just about preventing leaks,” explains Tom, one of our Okeechobee insurance specialists. “It’s also one of the best insurance investments you can make, often paying for itself over time through premium savings.”
Plumbing updates can also lead to significant savings. Replacing older pipes (especially galvanized or polybutylene) with copper or PEX reduces water damage risk and can lower your premiums. Similarly, electrical improvements like updating from fuse boxes to circuit breakers or replacing aluminum wiring can qualify you for safety discounts.
A professional wind mitigation inspection is worth its weight in gold. Having a certified inspector document your home’s wind-resistant features can open up substantial discounts, often paying for itself many times over in the first year alone.
Consider increasing your standard deductible (not your hurricane deductible). Raising it from $500 to $1,000 or higher can reduce premiums by 10-15%. Just make sure you keep enough savings to cover that higher deductible if you need to file a claim.
Don’t overlook your credit score—better credit translates to lower insurance rates in Florida. Paying down debt and correcting errors on your credit report can lead to meaningful premium reductions.
Common Claims & How to File One
When disaster strikes your Okeechobee home, knowing how to steer the claims process can make all the difference between a smooth recovery and added stress. Let’s walk through what you need to know about common claims and the filing process.
Okeechobee homeowners typically file home insurance Okeechobee FL claims for a handful of common issues. Water damage from plumbing failures tops the list—those burst pipes, failed water heaters, and washing machine hose ruptures can cause extensive damage in a matter of minutes. Wind and hurricane damage follows close behind, with roof damage and fallen trees being particularly problematic during Florida’s lengthy storm season.
“Last year, we saw a significant uptick in lightning-related claims,” shares Maria, a local claims specialist. “Many homeowners don’t realize Florida leads the nation in lightning strikes, which can fry electrical systems or even spark devastating fires.”
Theft and break-ins, unfortunately, remain common reasons for claims, along with fire damage from kitchen accidents or electrical malfunctions.
Step-by-step claims roadmap for Okeechobee homeowners
When the unexpected happens, follow these steps to ensure your home insurance Okeechobee FL claim goes as smoothly as possible:
Safety comes first—always ensure your family is safe and the property is secure before worrying about insurance matters. Once everyone’s safe, grab your phone and start documenting. Take extensive photos and videos of all damage before touching anything.
“Document all hurricane-related damages with photos and videos before filing,” advises Jim Roberts, a veteran insurance adjuster. “The photos you take in those first moments are often the most powerful evidence for your claim.”
Next, make only those temporary repairs necessary to prevent further damage. Cover that damaged roof with a tarp, board up broken windows, but don’t start major repairs until the insurance company has assessed the damage. Save every receipt for these emergency measures—they’re typically reimbursable.
Contact your insurance company or agent promptly. At Florida All Risk Insurance, we pride ourselves on guiding clients through this often confusing process, helping explain what to expect next and advocating on your behalf.
When the adjuster visits, be present and prepared. Consider having a trusted contractor there too—they might spot damage the adjuster misses. You can verify an adjuster’s license through FINRA’s BrokerCheck for peace of mind.
Review the settlement offer carefully before accepting. Don’t hesitate to question items that seem undervalued—this is your home we’re talking about! Once you’ve agreed on a fair settlement, complete repairs using licensed, insured contractors who stand behind their work.
Throughout the entire process, maintain a detailed file of all communications and receipts. This documentation can prove invaluable if questions arise later.
Claim documentation checklist
Thorough documentation dramatically improves your chances of a successful home insurance Okeechobee FL claim. Start with detailed photographs from multiple angles showing all damage. Don’t just snap a few quick pics—take the time to document everything thoroughly.
A video walkthrough with narration can be incredibly helpful. “Walk through your home, describing what you’re seeing as you record,” suggests Sarah Miller from Florida All Risk Insurance. “Mention when items were purchased and any details that might not be obvious from just looking at them.”
Create a comprehensive inventory of damaged items, noting approximate purchase dates and values. For high-value possessions like electronics, jewelry, or artwork, locate original receipts if possible. When getting repairs estimated, obtain written quotes from licensed contractors rather than verbal ballpark figures.
“If you have ‘before’ photos showing your property’s condition prior to the damage, these can be worth their weight in gold,” notes one claims specialist. “Annual home inventory videos or photos are something we strongly recommend to all our clients.”
Maintenance records can also help demonstrate that damage wasn’t pre-existing or due to neglect—important if there’s any question about coverage.
At Florida All Risk Insurance, we understand that filing a claim can be overwhelming, especially when you’re already dealing with property damage or loss. That’s why we’re committed to standing beside you throughout the entire process, from initial filing to final settlement. As your advocate, we’ll help ensure you receive the full benefits you’re entitled to under your policy.
“Claims can be filed online, by phone, or through an agent,” explains Jason Miller at Florida All Risk Insurance. “But having someone who knows the system guiding you through can make all the difference in the outcome.”
Choosing the Right Insurer & Getting Quotes
Selecting the right insurance provider is just as important as choosing the right coverage. Here’s how to make an informed decision:
How to get affordable “home insurance okeechobee fl” quotes fast
To efficiently compare home insurance Okeechobee FL options:
-
Work with an independent agency: Independent agencies like Florida All Risk Insurance represent multiple carriers, allowing you to compare options with a single contact. As one local agent notes, “As an independent agency, they shop multiple A-rated carriers to find the best value.”
-
Gather necessary information: To get accurate quotes, you’ll need:
- Home details (square footage, year built, construction type)
- Roof information (age, material, shape)
- Safety features (alarm systems, impact windows)
- Claims history (past 5 years)
- Personal information (credit may be checked)
-
Request comparable coverage: Ensure all quotes include the same coverage limits and deductibles for fair comparison.
-
Ask about instant-bind options: Some carriers offer immediate coverage binding, while others require inspections first.
-
Explore online quote tools: Many carriers and agencies offer online quote request forms for 24/7 convenience.
At Florida All Risk Insurance, we’ve streamlined this process to provide quick, accurate quotes from multiple carriers, saving you time and ensuring you get the most competitive rates.
Tips for evaluating agents and carriers
Not all insurance providers are created equal. Consider these factors when making your selection:
-
Financial strength ratings: Check A.M. Best, Demotech, or S&P ratings to ensure the carrier is financially sound. This is particularly important in Florida, where smaller carriers may face solvency challenges after major storms.
-
Local expertise: Choose an agent with specific knowledge of Okeechobee’s unique risks and insurance market. As one local professional notes, “We certainly know how to protect it.”
-
Customer service reputation: Read reviews and ask for references to gauge responsiveness and claims handling.
-
Policy servicing options: Verify whether you can make policy changes, access documents, and file claims online.
-
Carrier longevity in Florida: Some carriers have been leaving the Florida market. Choose one with a stable presence in the state.
-
Multi-policy options: If you need multiple insurance types (auto, boat, etc.), a carrier offering all these lines may provide better service and discounts.
For more business resources for small homeowners, visit Nationwide’s Business Solutions Center.
Frequently Asked Questions about Okeechobee Home Insurance
Do I need a separate flood policy if I live near Lake Okeechobee?
Absolutely, yes. This is one of the most important things to understand about living in Okeechobee: your standard homeowners policy provides zero protection against flooding, no matter how close you are to the lake.
“I can’t tell you how many homeowners I’ve met who assumed their regular policy would cover lake overflow or heavy rainfall,” says Jason Miller of Florida All Risk Insurance. “Unfortunately, they’re often devastated to learn the truth after water is already in their living room.”
If your home sits in a high-risk flood zone (typically zones starting with A or V), and you have a mortgage through a federally-backed lender, flood insurance isn’t optional—it’s required. But here’s the thing: even if you’re in a supposedly “safer” X zone, flood insurance makes tremendous sense in Okeechobee. Our area’s flat topography and vulnerability to heavy tropical rainfall means flooding can happen almost anywhere.
You have two main options for flood protection: the government-backed National Flood Insurance Program (NFIP) or increasingly popular private flood insurance carriers that often offer higher coverage limits and sometimes better rates. At Florida All Risk Insurance, we can quickly determine your flood zone and provide quotes from multiple sources to find the right protection for your property.
Can I bundle farm or ranch coverage with my homeowners policy?
This question hits home for many Okeechobee residents who have both a residence and agricultural activities on their property. The simple truth is that your standard homeowners policy leaves huge gaps in protection for anything farm-related.
Your regular home insurance Okeechobee FL policy typically won’t cover your tractor, livestock, crops, barns used for farming, or any liability connected to your agricultural operations. That’s a lot of exposure for local farmers and ranchers!
The good news? Many carriers offer specialized farm and ranch policies that can be bundled with your home coverage, often with a nice multi-policy discount. These specialized policies are built specifically for properties like yours, where life and livelihood share the same land.
“One of the things I love about serving Okeechobee is finding the right protection for our unique mix of residential and agricultural properties,” says Melissa Johnson, a local agent. “When a client can sleep well knowing both their home and their livelihood are properly protected, that’s when I know I’ve done my job right.”
At Florida All Risk Insurance, we partner with carriers who understand the unique needs of agricultural properties, ensuring your entire property—both the place you live and the place you work—has the right protection.
How does my home’s age affect windstorm deductibles?
Your home’s age plays a surprisingly significant role in your windstorm coverage options and costs. This is especially true in Okeechobee, where hurricane protection is so crucial.
Homes built after Florida’s major building code updates (particularly 2002 and 2007) often qualify for substantially better windstorm terms. These newer homes were built to stricter wind-resistance standards, and insurance companies reward that with lower premiums and more favorable deductible options.
For older homes, the roof age becomes particularly critical. Many carriers now offer only “actual cash value” coverage (which factors in depreciation) rather than “replacement cost” for wind damage to older roofs. This effectively increases your out-of-pocket costs well beyond your stated deductible when damage occurs.
“The difference in out-of-pocket costs between a 20-year-old roof and a 5-year-old roof after a hurricane can be shocking,” explains Robert Thomas, a claims specialist. “I’ve seen differences of $15,000 or more just because of roof age and the resulting coverage limitations.”
Older homes also require more thorough documentation of any wind-resistant features to qualify for premium discounts. While newer construction might automatically qualify for certain wind mitigation credits, older homes need formal inspections to prove they have comparable protection.
The most dramatic age-related difference might be in deductible options. Newer homes often qualify for fixed-dollar hurricane deductibles ($500 or $1,000), while older homes might be limited to percentage-based deductibles (2-5% of your dwelling coverage), which can mean much higher out-of-pocket costs during a claim.
At Florida All Risk Insurance, we specialize in finding the best options for homes of all ages in Okeechobee. We can help you understand exactly how your home’s age affects your coverage and identify smart improvements that might qualify you for better protection and lower costs.
Conclusion
Finding the right home insurance Okeechobee FL coverage doesn’t have to feel like navigating a maze. In our unique corner of Florida, where hurricanes sweep through and Lake Okeechobee presents its own set of challenges, having the right protection isn’t just smart—it’s essential for your peace of mind.
I’ve seen how the right policy can make all the difference when disaster strikes. At Florida All Risk Insurance, we don’t just sell policies—we build relationships with our Okeechobee neighbors, taking the time to understand your specific home, your concerns, and your budget.
As your independent agency, we do something the big direct writers can’t: shop multiple carriers to find you the best combination of coverage and value. We’ll explain everything in plain English—no insurance jargon or confusing fine print—so you know exactly what you’re getting.
Remember what matters most for Okeechobee homeowners:
Your standard policy is just the foundation. That home insurance Okeechobee FL policy won’t cover flooding, which is why we always recommend separate flood coverage—especially if you’re anywhere near the lake or in a designated flood zone.
Those wind mitigation features we discussed aren’t just about saving money (though the 15-40% premium reduction certainly helps!). They’re about keeping your home intact when those hurricane-force winds come calling.
Smart homeowners know that bundling policies, maintaining good credit, and investing in security features can substantially lower your premium while strengthening your protection. Sometimes saving $50 by cutting coverage limits isn’t worth it when you’re facing a $20,000 repair bill that exceeds your policy limits.
Whether you’re buying your first Okeechobee home or you’ve been here for generations, we’d love to review your coverage and make sure you’re properly protected without overpaying. Our personalized approach means we’ll find discounts and savings opportunities others might miss.
For more information about how we can help with your Florida homeowners insurance needs, visit our Florida homeowners insurance solutions page.
Let’s make sure your Okeechobee home is protected the right way. After all, it’s not just a house—it’s where your memories are made and your future is built. And that deserves the very best protection.

