

General liability insurance for home care agency: Essential 2025 Guide
The Essential Shield: Understanding Your Agency’s Risks
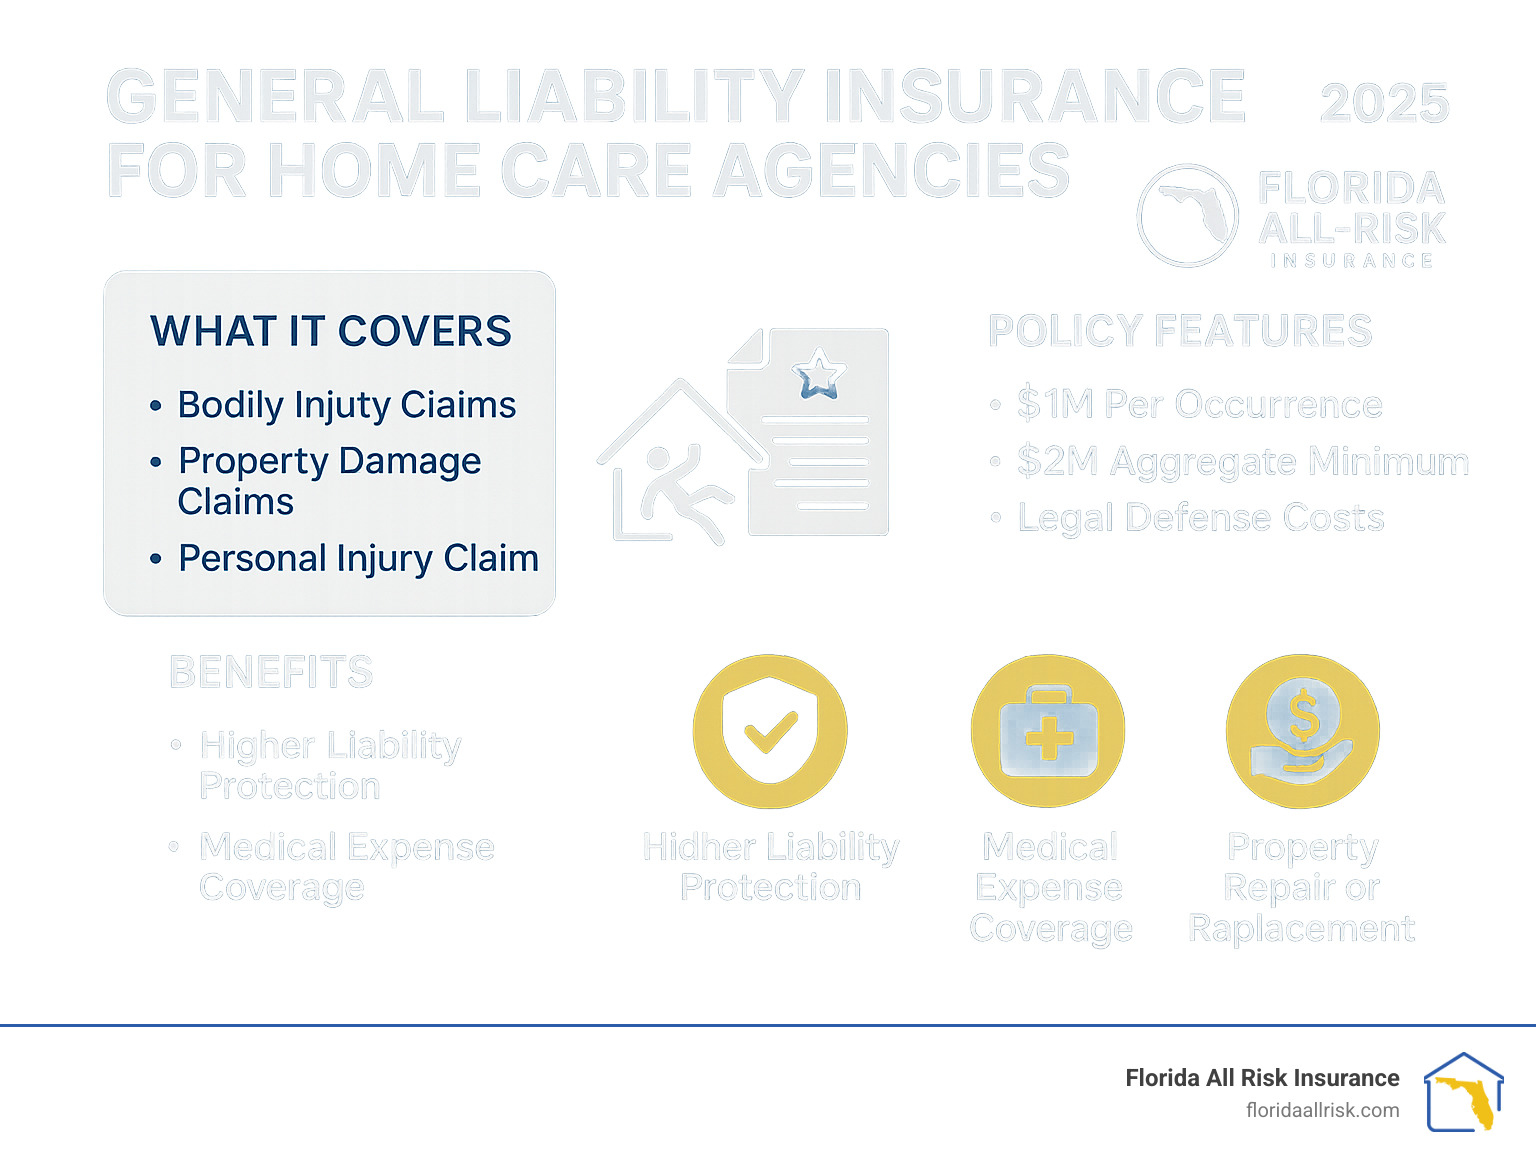
General liability insurance for home care agency provides critical protection against third-party claims for bodily injury, property damage, and personal injury. Because home care workers operate in clients’ private homes, the risk of accidents like slip-and-falls, property damage, or visitor injuries is significantly higher than in controlled healthcare settings. These everyday scenarios can lead to costly lawsuits, making this coverage essential for your agency’s survival.
Quick Answer for Home Care Agencies:
- What it covers: Third-party bodily injury, property damage, personal injury claims
- Average cost: $30-51 per month ($365-620 annually)
- Key protection: Legal defense costs, medical expenses, property repair/replacement
- Essential because: Caregivers work in clients’ homes with higher liability exposure
- Coverage limits: Typically $1M per occurrence, $2M aggregate minimum
The home care industry is built on trust, but it operates in an environment filled with unique risks. A client could slip and fall, a caregiver might accidentally damage a family heirloom, or a misunderstanding could lead to a claim of slander. Unlike traditional facilities, your agency faces the unpredictable nature of diverse residential settings. General liability insurance acts as a financial shield against these risks.
I’m Jason Miller, and with over 20 years of experience providing general liability insurance for home care agency owners in Florida, I’ve seen how the right coverage prevents devastating financial losses. My expertise helps agencies steer Florida’s unique insurance landscape to secure comprehensive protection at competitive rates.
General liability insurance for home care agency terms you need:
- commercial general liability insurance for small business
- how much general liability insurance do i need
- general liability errors and omissions insurance
What is General Liability Insurance for a Home Care Agency?
General liability insurance for home care agency operations, also known as Commercial General Liability (CGL), is your business’s first line of defense against claims of bodily injury or property damage. It’s designed to handle the common, non-medical accidents that can occur as your caregivers work in clients’ homes—uncontrolled environments where anything from a slippery floor to misplaced equipment can lead to a lawsuit. While your team focuses on providing compassionate care, this insurance handles the unexpected mishaps that could otherwise devastate your business financially.
Unlike professional liability, which covers errors in your caregiving services, general liability covers everyday incidents that happen simply because you’re conducting business in someone else’s space.
Defining Third-Party Claims
A “third-party” is anyone outside of your company who might file a claim against your business. For a home care agency, this includes:
- Clients: The most obvious category. If a client is injured in an accident related to your operations (e.g., slipping on a wet floor your caregiver just cleaned), they can file a claim.
- Visitors: This protection extends to anyone else in the home, such as a family member who trips over medical supplies or a delivery person who falls on an icy step your caregiver should have cleared.
Even if a lawsuit is groundless, general liability insurance for home care agency operations covers your legal defense costs, which can be substantial. This ensures that false accusations don’t become financial disasters. For more information, you can explore our Business Liability Insurance coverage options.
Core Protections of a CGL Policy
A CGL policy provides five essential protections to shield your agency:
Bodily injury coverage pays for medical expenses, rehabilitation costs, and other related expenses if a third party is physically harmed during your operations. This could be a client who falls and breaks a hip or a visitor who is accidentally injured.
Property damage coverage handles the repair or replacement costs when your caregiver accidentally damages a client’s belongings. This includes everything from a broken family heirloom to a spilled drink that ruins a laptop.
Personal and advertising injury covers non-physical damages, such as claims of libel, slander, copyright infringement in your marketing materials, or invasion of privacy.
Legal defense costs are one of the most valuable parts of the policy. It pays for attorneys, court fees, and other legal expenses to defend your agency, regardless of whether you win or lose the case.
Medical payments coverage offers a way to resolve minor injuries quickly and amicably. It pays for immediate, small medical expenses for an injured third party without requiring a formal admission of fault.
What Your Policy Covers: Common Scenarios and Protections
General liability insurance for home care agency operations responds to a wide range of non-professional incidents. Your caregivers are dedicated professionals, but they are also human beings working in uncontrolled environments. When an everyday accident occurs, this insurance protects your financial assets by covering legal fees, settlements, and medical costs.
Bodily Injury Claims
These are the most frequent claims, involving physical harm to a third party during your business operations.
- Client Slip and Fall: A client trips over a caregiver’s bag left in a hallway or slips on a small spill during meal prep. These incidents are common and can lead to serious injuries, especially with elderly clients.
- Visitor Injuries: A visiting family member trips over a portable oxygen cord, or a delivery person stumbles on a misplaced piece of equipment. Your policy covers injuries to non-clients as well.
- Accidental Injury: A caregiver might inadvertently cause an injury that is not related to medical malpractice, such as bumping into a client and causing them to lose their balance.
Your policy’s medical expense coverage is vital, as it handles the costs of treatment and prevents a minor incident from escalating into a major financial liability. For more details, see our guide on What Does General Liability Insurance Cover?
Property Damage Claims
Accidents can also involve damage to a client’s personal property. Your agency works within their personal space, surrounded by valuables and necessities.
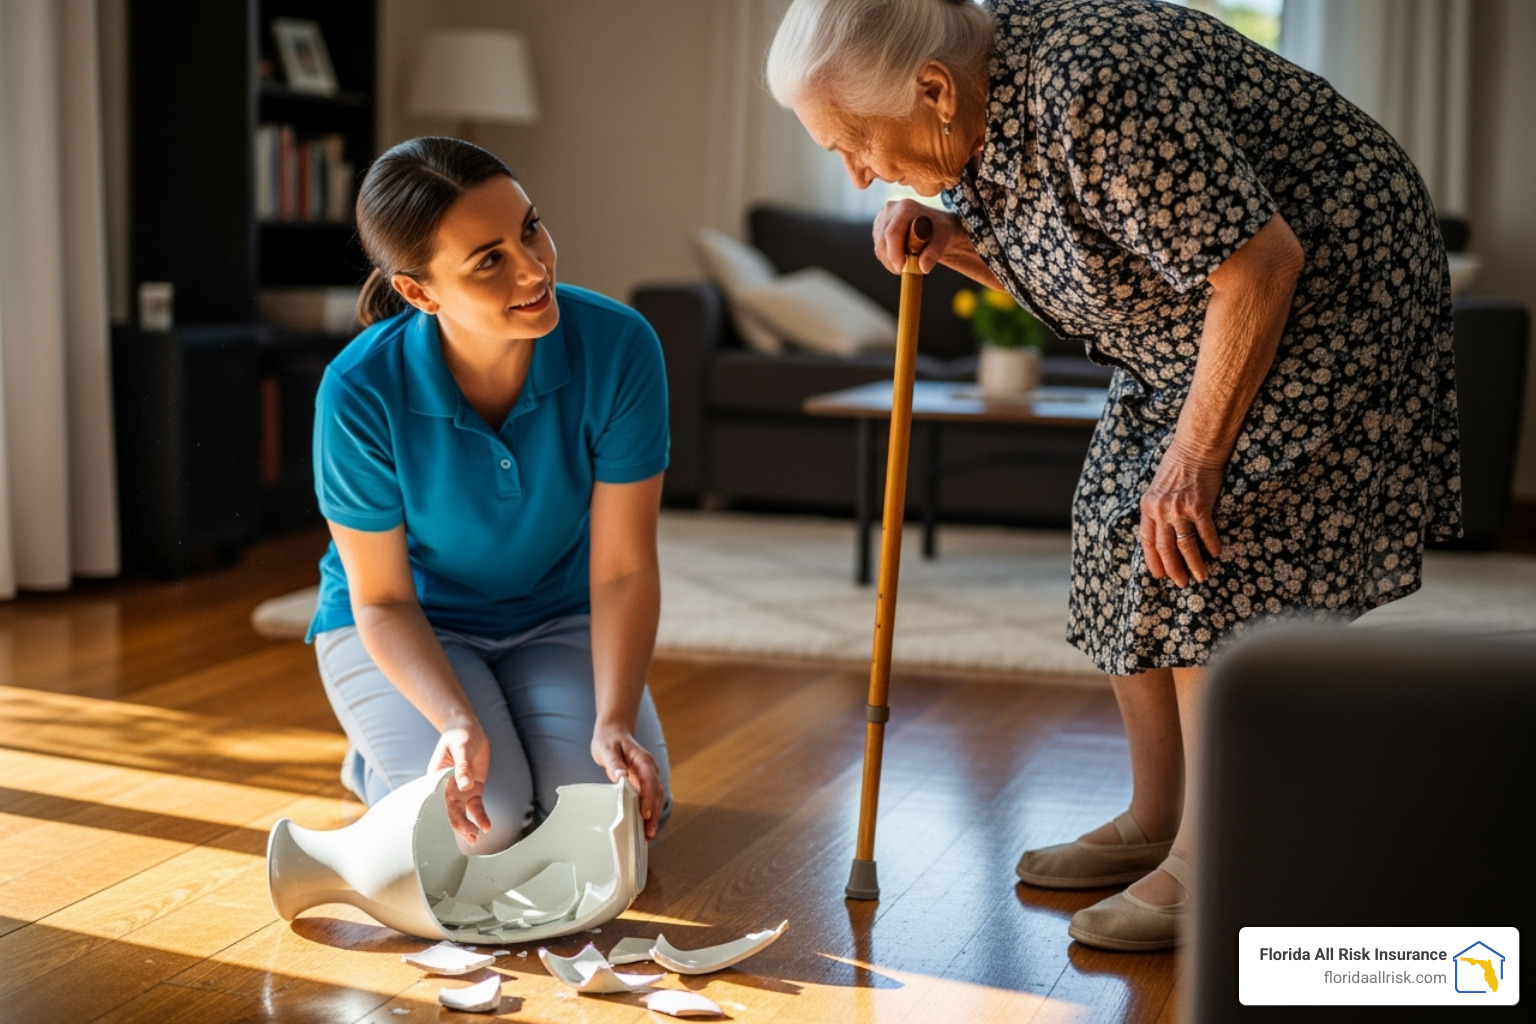
- Breaking Valuables: A caregiver accidentally knocks over an antique vase while dusting or bumps into a display cabinet.
- Furniture and Fixture Damage: A wheelchair scratches a hardwood floor, or a cleaning solution damages a dining room table.
- Spills and Liquid Damage: A spilled glass of juice ruins an expensive rug, or an overflowing sink causes water damage to cabinets and flooring.
Your policy covers both repair and replacement costs, allowing you to resolve the situation with your client without bearing the full financial burden.
Personal and Advertising Injury
These claims are less common but can be very damaging to your agency’s reputation and finances.
- Libel or Slander: An employee makes a statement that damages someone’s reputation.
- Copyright Infringement: Using stock photos, website text, or music in your marketing materials without proper licensing.
- Invasion of Privacy: Accidentally sharing confidential client information or taking photos in a client’s home without permission.
This coverage provides peace of mind, protecting you from legal issues arising from miscommunications or mistakes.
General Liability vs. Other Essential Home Care Insurance
While crucial, general liability insurance for home care agency is just one piece of a complete insurance portfolio. It is often confused with professional liability, but they cover distinctly different risks. Think of your insurance plan as a set of specialized shields, each protecting against a specific threat.
Why general liability insurance for a home care agency is not enough
The key difference is what each policy covers: general liability handles general business risks (like slip-and-falls), while professional liability handles risks related to your professional services (like errors in care).
For example, if a caregiver knocks over an expensive vase, general liability would cover it. However, if a caregiver administers the wrong medication, causing harm, you would need professional liability insurance. A CGL policy will not cover claims of malpractice or negligence in care delivery.
| Feature | General Liability Insurance | Professional Liability (E&O) Insurance |
|---|---|---|
| Primary Focus | Non-professional accidents and injuries | Negligence in professional services |
| Example Claim | A client trips over a caregiver’s bag and breaks their arm. | A caregiver administers the wrong medication, causing harm. |
| Covers | Third-party bodily injury, property damage, advertising injury. | Errors, omissions, malpractice, undelivered services. |
| Also Known As | CGL, “Slip and Fall” Insurance | Errors & Omissions (E&O), Malpractice Insurance |
Other Key Policies to Consider
To truly safeguard your agency, you need a combination of coverages:
- Workers’ Compensation: Required by law in most states, this covers medical expenses and lost wages for employees injured on the job. It also protects your business from employee injury lawsuits.
- Commercial Auto Insurance: If your agency owns vehicles for transporting clients or supplies, this is essential. A personal auto policy will not cover business-related accidents.
- Hired and Non-Owned Auto (HNOA): This vital coverage protects your agency if a caregiver has an accident while using their personal vehicle for work and their own insurance is insufficient.
- Cyber Liability Insurance: Protects against data breaches and cyberattacks, covering costs like client notification, credit monitoring, and legal fees related to the loss of sensitive electronic data.
- Fidelity Bonds: Protects your clients (and your agency’s reputation) from theft or dishonest acts committed by your employees.
Building a complete insurance package is essential for long-term stability. For more insights, explore our guide on Comprehensive Business Insurance for Small Businesses.
Cost and Acquisition of General Liability Insurance
For the critical protection it provides, general liability insurance for home care agency is surprisingly affordable. Understanding the factors that influence your premium helps you find the best value for your agency’s specific needs.
Factors Influencing Your Premium
Insurers assess your agency’s risk based on several key factors:
- Agency Size and Revenue: Larger agencies with more employees and higher annual revenue generally have greater exposure and may see higher premiums.
- Number of Employees: Each caregiver represents an additional point of interaction with clients and their property, increasing the chance of a claim.
- Services Offered: Agencies providing skilled nursing or complex medical care may face slightly higher general liability risks than those offering only non-medical companion care.
- Claims History: A clean record with no prior claims can qualify you for lower rates, while a history of claims may increase your premium.
- Policy Limits and Deductibles: Higher coverage limits increase your premium but offer more protection. A higher deductible can lower your premium but means you pay more out-of-pocket per claim.
- Location: Rates can vary based on your geographic location. Operating in a densely populated area like Miami-Dade may have different costs than in rural North Florida.
For a deeper dive, check out our guide on General Liability Insurance Cost.
Understanding the cost of general liability insurance for a home care agency
Most home care agencies can expect to pay between $30 to $51 per month ($365 to $620 annually) for general liability coverage. These are median costs, so smaller agencies may pay less, while larger operations could pay more depending on the risk factors above. Most insurers offer both monthly and annual payment options, with a small discount often available for paying annually.
The Small Business Administration offers authoritative guidance on business insurance, emphasizing the need to match coverage to your specific risks rather than just shopping for the lowest price.
How to Obtain a Policy
Getting coverage is a straightforward process, especially with an experienced agent.
- Gather Business Information: Have your legal business name, address, years in business, annual revenue, and employee count ready.
- Consult an Independent Agent: An independent agent like Florida All Risk Insurance shops multiple carriers to find you the best rates and coverage custom to home care agencies.
- Compare Quotes: Your agent will present you with options, explaining the differences in coverage, limits, and pricing.
- Review and Bind Coverage: Once you select a policy, your agent will review the details with you. Coverage can often be bound within 24 hours, and you’ll receive a certificate of insurance as proof of your policy.
Frequently Asked Questions about General Liability Insurance for Home Care Agencies
Navigating insurance can bring up many questions. Here are answers to some of the most common queries from home care agency owners.
What are common exclusions in a general liability policy?
While broad, a general liability policy does not cover everything. Key exclusions include:
- Professional Services (Malpractice): Errors in your actual caregiving duties, like medication errors, are excluded. This risk requires a separate Professional Liability policy.
- Employee Injuries: Injuries to your own staff are covered by Workers’ Compensation insurance, not general liability.
- Auto Accidents: Incidents involving vehicles, whether company-owned or personal cars used for work, must be covered by a Commercial Auto or Hired and Non-Owned Auto policy.
- Intentional Acts: The policy will not cover harm that is caused deliberately.
- Electronic Data Loss: Data breaches and cyberattacks require a separate Cyber Liability policy.
Understanding these exclusions is key to building a complete insurance portfolio.
How much general liability insurance do I need?
The right amount of coverage depends on your agency’s specific risk exposure. Many contracts with clients, healthcare networks, or government agencies will mandate minimum coverage levels. The industry standard is typically $1 million per occurrence and $2 million aggregate.
- $1M Per Occurrence: The maximum amount the policy will pay for a single incident.
- $2M Aggregate: The total amount the policy will pay for all claims during the policy year.
Agencies with higher risk exposure or valuable contracts should consider an umbrella policy, which adds an extra layer of liability protection (typically starting at $1 million) on top of your primary policy. Legal fees alone can be costly, so it’s wise not to settle for the bare minimum. For more guidance, see our resource on How Much General Liability Insurance Do I Need?
Are independent contractors covered by my agency’s policy?
Generally, no. Your agency’s general liability policy is designed to cover your business and your direct employees, not independent contractors, who are considered separate business entities.
To protect your agency, you should implement a clear policy for subcontractors:
- Require Them to Have Insurance: Your contract should mandate that all independent contractors carry their own general liability and professional liability insurance, with limits at least as high as your own.
- Verify Coverage: Always obtain a current certificate of insurance from each contractor before they begin work. This is non-negotiable.
While adding a contractor as an “additional insured” on your policy is sometimes possible, it is often more complex and costly than requiring them to have their own coverage. For state-specific rules, you can consult resources like Florida’s Agency for Health Care Administration.
Secure Your Agency’s Future Today
Protecting your home care agency with the right General Liability Insurance is a fundamental business strategy. It provides the financial security to shield you from unforeseen accidents, improves your credibility with clients, and gives you the peace of mind to focus on what you do best: providing exceptional care to those who need it.
An unexpected claim can threaten everything you’ve built. Don’t leave your hard-earned business, your employees’ livelihoods, and your community reputation exposed to risk. An experienced independent agency like Florida All Risk Insurance understands the unique challenges of the home care industry and can find a policy custom to your specific needs.
Take the proactive step to ensure your agency is protected for years to come.
Ready to Protect Your Practice?
Contact us today for a comprehensive review of your insurance needs and a no-obligation quote. Let our experts build the shield your agency deserves.
Get Your Free General Liability Quote Today!
Contact Us:
Florida All Risk Insurance
- Address: Saint Petersburg, FL
- Phone: (727) 545-5566
- Email: [email protected]

