

Why Hialeah Homeowners Need Comprehensive Insurance Protection
Hialeah Home Insurance: Don’t Get Flooded Out, Get Covered!
Hialeah home insurance is essential for protecting your home, one of your largest investments. As a Hialeah homeowner in Miami-Dade County, you face unique risks like hurricanes and floods, along with a challenging insurance market that demands careful navigation.
Quick Answer for Hialeah Home Insurance Seekers:
- Average Cost: $3,405 annually for typical coverage
- Key Coverage Areas: Dwelling, personal property, liability, and additional living expenses
- Special Considerations: Separate flood insurance required, hurricane deductibles apply
- Cost Factors: Home age, size, and location
- Top Discounts: Wind mitigation, hurricane shutters, security systems, bundling policies
With over 221,300 residents and an average home value of $450,409, making the right coverage choices in Hialeah can save you hundreds annually. The city’s coastal proximity and Florida’s volatile weather make comprehensive protection a necessity for any responsible homeowner.
I’m Jason Miller, an insurance professional with over 20 years of experience at Florida All Risk Insurance. I specialize in helping Florida homeowners steer the complex Hialeah home insurance market, finding comprehensive coverage that protects their homes and budgets in this challenging environment.
Terms related to hialeah home insurance:
- best homeowners insurance in florida 2025
- top 10 homeowners insurance companies in florida
- another home insurance company leaving florida
Why Home Insurance is Non-Negotiable in Hialeah
Living in South Florida means enjoying year-round sunshine, but it also means facing unique challenges that make comprehensive Hialeah home insurance absolutely essential. Your home is one of your biggest investments, and in Hialeah, it faces risks that homeowners in other parts of the country rarely encounter.
Beyond financial protection, there’s a practical reality: if you have a mortgage, your lender will require you to have homeowners insurance. But the real peace of mind comes from knowing your family has a safe place to call home, no matter what storms may come. Without proper coverage, rebuilding costs and temporary living expenses can quickly drain a lifetime of savings. Similar challenges face homeowners throughout the region, which is why we also provide guidance on Homeowners Insurance Homestead, FL.
Understanding Hialeah’s Unique Climate Risks
Living in Hialeah means embracing a tropical climate with serious weather patterns. Hurricane season, from June through November, brings the threat of destructive high winds that can tear off roofs and cause catastrophic structural damage. These powerful storms can also produce dangerous storm surge, pushing coastal waters far inland.
Even when a hurricane isn’t a direct threat, heavy rainfall from tropical systems can overwhelm local drainage and cause significant flooding. The year-round high humidity creates a perfect environment for mold and mildew, which can cause property damage and health issues after any water intrusion. These are documented realities of living in South Florida, as shown by Florida’s severe weather risks.
The Role of Home Insurance in Protecting Your Investment
Your home is more than just a building; it’s your family’s foundation and likely your largest financial asset. Home insurance serves as a multi-faceted shield:
- Asset Protection: Covers the cost to repair or rebuild your home after a covered event
- Rebuilding Cost Coverage: Provides funds to rebuild from the ground up in case of total loss
- Liability Coverage: Protects against lawsuits if someone is injured on your property
- Mortgage Compliance: Keeps you in good standing with your lender
- Financial Safety Net: Covers personal belongings and additional living expenses
Decoding Your Hialeah Home Insurance Policy: What’s Covered?
Your Hialeah home insurance policy can seem complex, but understanding its core components is key. Most homeowners have an HO-3 policy, which provides broad protection. It covers your home’s structure on an “open perils” basis, meaning it’s protected against all events except those specifically excluded. Your personal belongings are covered on a “named perils” basis, protected against specific events listed in the policy.
Understanding your policy limits and deductibles is crucial. For more insights, our Homeowners Insurance Florida guide is a great resource.
Core Property Coverages
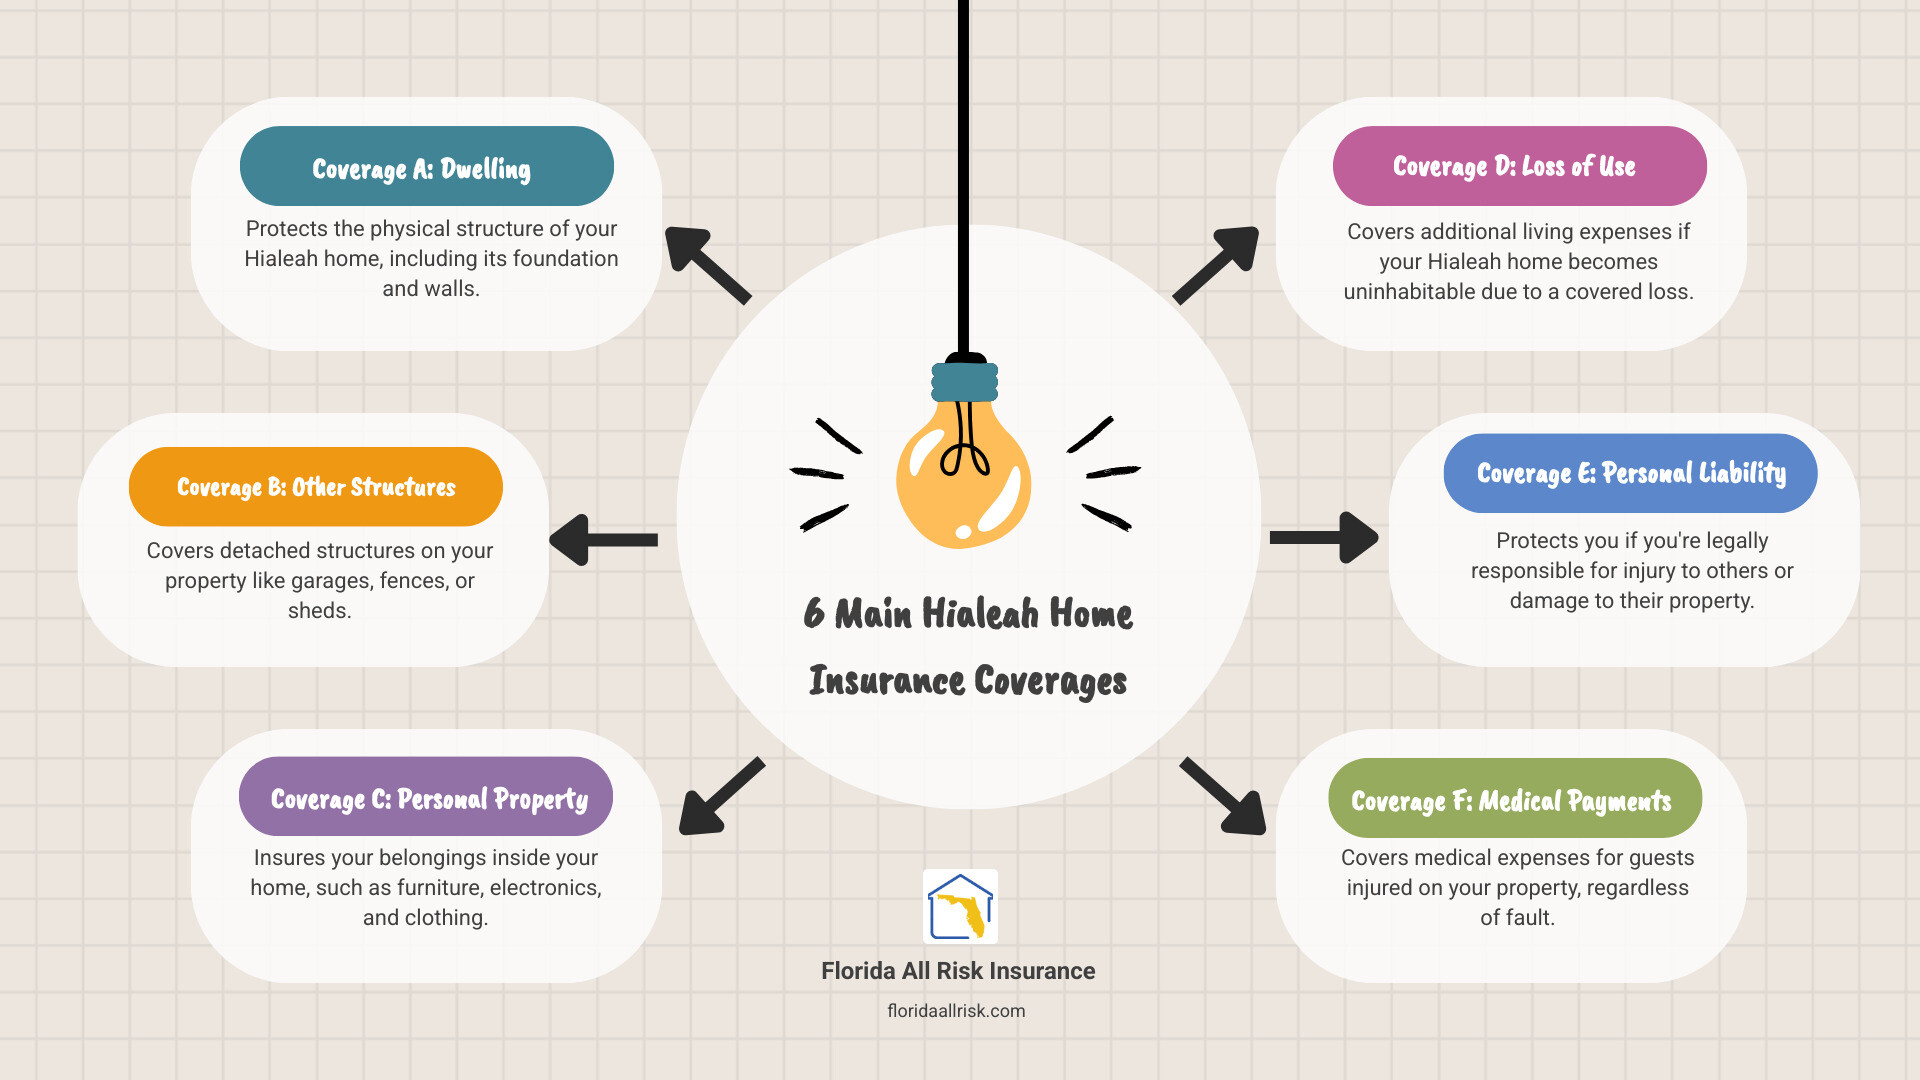
- Coverage A – Dwelling: Covers your home’s structure, including walls, roof, foundation, and built-in appliances. The coverage amount should be high enough to completely rebuild your home at current construction costs.
- Coverage B – Other Structures: Protects detached structures like garages, fences, sheds, or gazebos, typically set as a percentage of dwelling coverage.
- Coverage C – Personal Property: Covers belongings from furniture to clothing. Replacement Cost Value (RCV) is recommended as it pays to replace items with new ones, while Actual Cash Value (ACV) only pays depreciated value.
Liability and Additional Living Expense Protections
- Coverage D – Loss of Use: Pays for hotel stays, meals, and other reasonable expenses if your home becomes unlivable after a covered loss.
- Coverage E – Personal Liability: Your financial shield against lawsuits, handling legal defense costs and settlements up to your policy limit.
- Coverage F – Medical Payments to Others: Provides immediate coverage for medical expenses if a guest is injured on your property.
Special Considerations for Hialeah Home Insurance: Floods and Windstorms
Standard homeowners insurance policies do NOT cover flood damage. You need a separate flood insurance policy through the National Flood Insurance Program (NFIP) or a private insurer. With about 25% of flood claims coming from outside high-risk zones, this is critical for all Hialeah homeowners.
Another Florida-specific feature is the hurricane deductible—a percentage of your dwelling coverage that applies only to damage from named hurricanes. While windstorm coverage is generally included in Hialeah policies, the state’s challenging market, with news of Another Home Insurance Company Leaving Florida, makes it essential to review your policy’s specifics with an expert.
The Cost of Hialeah Home Insurance: Factors and Averages
Understanding what you’ll pay for Hialeah home insurance is crucial for budgeting. Premiums in our area can vary dramatically based on a home’s specific risk profile. Our typical clients in Hialeah pay around $3,405 annually, but this is just an average.

Working with an independent agency is valuable in this volatile market, as we can shop multiple carriers to find competitive rates. For more context, see our analysis of the Best Homeowners Insurance in Florida 2025.
Key Factors That Influence Your Premium
Insurers use sophisticated models to assess risk. Key factors include:
- Home Age & Construction: Newer homes built to modern codes receive lower rates
- Roof Characteristics: Age, material, and shape significantly impact pricing
- Home Size & Value: Larger homes cost more to insure
- Location: Zip code 33015 tends to be more expensive than 33018
- Protective Devices: Security systems and wind mitigation features earn discounts
- Claims History & Credit Score: Both affect your premium
Average Home Insurance Costs in Hialeah
While our typical Hialeah client pays around $3,405 annually, your actual cost will vary:
- By Home Age: Homes under 25 years old average $2,267, while homes over 25 years old average $3,897
- By Home Size: Homes under 2,500 sq. ft. average $3,199, while homes over 2,500 sq. ft. average $4,534
How to Lower Your Hialeah Home Insurance Costs
Steps to reduce your premiums without sacrificing coverage:
- Wind Mitigation Credits: The biggest money-saver in Florida through certified inspection
- Hurricane Protection: Installing approved shutters or impact-resistant windows
- Raise Your Deductible: Higher deductibles lower annual premiums
- Bundle Policies: Combining home and auto insurance typically saves 5-25%
- Install Safety Devices: Monitored security and fire alarm systems qualify for discounts
For more strategies, the Insurance Information Institute provides excellent guidance on how to save money on your homeowners insurance. We help homeowners in communities like Homeowners Insurance Weston, FL find these savings.
Finding and Filing: Your Guide to Managing Your Policy
Getting the right Hialeah home insurance policy is just the first step. Knowing how to manage your coverage and what to do if you need to file a claim is where the real value lies. At Florida All Risk Insurance, we partner with you for the long haul, from policy selection to claims assistance.

As your insurance advocates, we provide the personal touch and expert guidance that sets an independent agency apart.
How to Find the Best Policy for Your Hialeah Home
Finding the perfect policy shouldn’t be a guessing game. Our proven approach ensures you get coverage that truly fits your needs.
- Assess Your Needs: Start by creating a home inventory to determine how much personal property coverage you need. Then, we’ll help you calculate your home’s replacement cost—what it would cost to rebuild today—which is often higher than its market value.
- Shop the Market: As an independent agency, we do the shopping for you. We compare quotes from multiple top-rated carriers to find competitive options custom to your home.
- Compare More Than Price: We’ll walk you through the policy details, explaining what’s covered, what’s excluded, and how your deductibles work so you can make an informed choice.
- Verify Carrier Strength: We only work with financially stable insurers who have a proven track record of paying claims fairly and efficiently.
- Choose the Right Deductibles: We can show you how different deductible levels affect your premium, helping you find the right balance between annual savings and potential out-of-pocket costs.
- Plan for Flood: If your home has any exposure to surface water, we’ll also review NFIP and private flood options so you’re not surprised by what standard home insurance excludes.
We bring this same personalized service to homeowners in other communities, including those seeking Homeowners Insurance Pembroke Pines, FL.
Steps to Take When Filing a Claim
If you need to file a claim, a calm, organized approach can make a stressful situation more manageable.
- Contact Us Immediately: Call your agent as soon as it’s safe to do so. The sooner you report the loss, the sooner the process can begin. We’re here to guide you.
- Prioritize Safety: If there’s any danger from structural damage or downed power lines, leave the house and call for emergency help. Your safety is paramount.
- Prevent Further Damage: Make temporary repairs to protect your property from more harm, like placing a tarp over a damaged roof. Keep all receipts, as these costs are typically reimbursable.
- Document Everything: This is crucial. Take extensive photos and videos of all damage from multiple angles before you clean up or make repairs. Create a list of damaged belongings.
- Keep Detailed Records: Maintain a log of everyone you speak with at the insurance company, noting the date and what was discussed. Keep copies of all paperwork.
- Track Additional Living Expenses: If you must leave your home temporarily, keep receipts for lodging, meals, laundry, and transportation. Only the incremental amounts above your normal spending are reimbursable.
- Review Your Settlement Offer: Go over any settlement offer carefully. If it seems insufficient, contact us. As your advocate, we can help you understand the offer and negotiate if necessary.
It’s also wise to understand Florida’s updated rules on claim assignments and contractor agreements. Be cautious with any document titled “Assignment of Benefits” or “Direction to Pay,” which can transfer claim rights. Florida’s Department of Financial Services provides consumer guidance and resources at MyFloridaCFO Consumer Services. When in doubt, run documents by your agent before signing.
Annual Policy Checkup: What to Review
- Is your Coverage A (Dwelling) limit still adequate given material and labor inflation?
- Have you made any updates (roof, plumbing, electrical) that could lower premiums?
- Do you need higher liability or a personal umbrella?
- Have your valuables changed, requiring scheduled property updates?
- Is your hurricane deductible still the right fit for your emergency fund?
A quick annual review before hurricane season reduces surprises and keeps your protection aligned with your real-world risks.
Frequently Asked Questions about Hialeah Home Insurance
Navigating Hialeah home insurance can be confusing. Here are clear, honest answers to the questions we hear most often from our clients.
Do I need flood insurance in Hialeah even if I’m not in a high-risk zone?
Yes, you should strongly consider it. Standard home insurance policies explicitly exclude all forms of flood damage. According to FEMA, about 25% of all flood claims occur in low-to-moderate risk areas. Hialeah’s low-lying geography makes it susceptible to flooding from heavy summer rains, not just hurricane storm surge.
A separate policy from the National Flood Insurance Program (NFIP) or a private carrier is the only way to cover this risk. For homes in low-risk zones, the cost is often surprisingly affordable and provides essential peace of mind. There’s typically a 30-day waiting period, so it’s best to secure coverage before storm season begins.
What is a hurricane deductible and how does it work?
A hurricane deductible is separate from your standard policy deductible and applies only to damage from a named hurricane. Instead of a flat dollar amount, it is calculated as a percentage of your dwelling coverage (Coverage A). Common percentages are 2%, 5%, or 10%.
For example, if your home is insured for $400,000 and you have a 2% hurricane deductible, you would be responsible for the first $8,000 of damage from a named storm. Your insurance would cover the rest, up to your policy limit. Most policies apply only one hurricane deductible per calendar year, regardless of how many storms hit.
Why are my Hialeah insurance rates so high?
This is a tough reality for all Florida homeowners. The state’s insurance market is facing a crisis, leading to higher rates for everyone. The primary reasons include:
- Increased Hurricane Frequency & Severity: Major storms in recent years have resulted in billions of dollars in insured losses.
- Excessive Litigation & Fraud: For years, Florida has struggled with a disproportionate number of lawsuits and fraudulent claims, which drives up costs for all policyholders.
- Soaring Reinsurance Costs: Reinsurance is insurance for insurance companies. Its cost has skyrocketed globally, and insurers pass that cost on to consumers.
- Rising Construction Costs: The price of labor and materials to rebuild homes has surged, increasing the potential cost of any claim.
- Insurers Leaving the State: Several companies have left Florida or stopped writing new policies, reducing competition and giving homeowners fewer, more expensive options.
As an independent agency, we can’t control these market forces, but we can help you steer them by shopping multiple carriers and identifying every available discount.
Will my policy cover a new roof at replacement cost?
It depends on your policy. Some carriers offer replacement cost on roofs, while others use actual cash value (ACV) or a roof schedule that reduces payouts based on age and material. Review your roof coverage carefully, especially for wind or hail losses, and consider the impact on your out-of-pocket cost.
Are solar panels and screened enclosures covered?
Solar panels are typically covered as part of the dwelling if permanently attached, but insurers may require specific documentation or endorsements. Screened enclosures, lanais, and carports often have limited or excluded wind coverage without an endorsement. If you’ve invested in these features, confirm you have the right add-ons.
Do I need a wind mitigation or four-point inspection?
In Hialeah, these inspections are often required and can save you money. A wind mitigation inspection documents features like roof shape, nail patterns, and opening protection that qualify for credits. A four-point inspection (roof, plumbing, electrical, HVAC) is commonly required for homes about 25+ years old to verify system condition.
How much liability insurance should I carry?
It depends on your assets and risk tolerance, but many homeowners choose at least $300,000 to $500,000 in personal liability. Households with higher assets or exposures (e.g., a pool or trampoline) often add a personal umbrella policy providing $1 million or more of additional liability protection.
Are certain dog breeds, pools, or trampolines an issue?
Some insurers have breed restrictions or underwriting rules for pools and trampolines. Requirements may include specific fencing, locked gates, and pool enclosures. Disclose these features to your agent so we can match you with a carrier that fits your situation.
What about home-sharing or short-term rentals?
Standard homeowners policies usually exclude or limit coverage for short-term rental activities. If you rent out your home or a portion of it on platforms like Airbnb or Vrbo, ask about a home-sharing endorsement or a landlord policy to close those gaps.
How should I estimate my dwelling coverage amount?
Insure to reconstruction cost, not market value. We use current local labor and material pricing and details about your finishes and features to estimate what it would cost to rebuild your home today. Periodic updates are important because building costs change over time.
What’s the difference between flood insurance and water backup coverage?
Flood insurance covers rising water from outside your home (storm surge, heavy rain accumulation). Water backup covers damage from backups through sewers or drains inside the home. They address different risks and are purchased separately.
Can I change coverage during hurricane season?
Yes, but be aware that insurers may pause new business or changes when a storm is projected to affect Florida. Review and adjust your policy early in the year so you’re not caught by a binding moratorium when a storm approaches.
Conclusion: Secure Your Hialeah Home with the Right Protection
Protecting your Hialeah home is about safeguarding your family, your investment, and your peace of mind. In a region facing annual hurricane threats and significant flood risks, having the right insurance isn’t a luxury—it’s a necessity. We’ve covered the key components of a policy, from dwelling and liability coverage to the critical need for separate flood insurance and an understanding of hurricane deductibles.
Proactive steps like wind mitigation and installing protective devices can lower your costs and improve your safety. However, navigating Florida’s turbulent insurance market alone can be daunting. As an independent agency, Florida All Risk Insurance works for you, not a single carrier. We leverage our expertise and market access to find you comprehensive, competitively priced coverage custom to your unique needs.
Don’t wait for a storm to find out you have gaps in your coverage. Let us help you secure the protection your Hialeah home deserves.
Ready to secure your Hialeah home with comprehensive coverage that actually protects what matters most? Get a comprehensive Florida homeowners insurance policy and experience the confidence that comes with knowing you’re truly protected.
If you prefer a local, human conversation about your options, reach out to our St. Petersburg–based team at Florida All Risk Insurance—we’re here to help year-round.

