

General liability insurance Tampa: Secure Your 2025
Why Every Tampa Business Owner Needs General Liability Protection
General liability insurance Tampa is an absolutely critical financial safeguard for any enterprise operating in the vibrant but competitive landscape of Hillsborough County. It serves as your primary defense, protecting your business from the potentially devastating costs of third-party claims alleging bodily injury, property damage, and personal or advertising injury. In today’s litigious environment, a single slip-and-fall accident, a damaged piece of client property, or an ill-advised marketing campaign can trigger a lawsuit that threatens your company’s very existence.
Quick Answer for Tampa Business Owners:
- Average Cost: Approximately $49 per month for a typical small business in Tampa, though this varies widely by industry.
- Required Coverage: While not mandated by state law for all businesses, it is a standard requirement for most commercial leases, client contracts, and professional licensing in the Tampa Bay area.
- What It Covers: Key protections include third-party bodily injury, property damage, personal and advertising injury (like libel or copyright infringement), and the associated legal defense costs.
- Who Needs It: Essentially all Tampa businesses that interact with the public, including contractors, retailers, restaurants, consultants, and home-based businesses.
- How to Get It: The most effective method is to contact a licensed, independent Florida insurance agent who can source multiple quotes to find the best fit for your specific needs.
Tampa is a dynamic hub for commerce, from the busy Port of Tampa to the thriving tech scene and the ever-present tourism and construction sectors. This economic vitality, however, brings with it a proportional increase in liability risks. Whether you run a construction firm in the Westshore Business District, a boutique in Hyde Park Village, or a consulting service operating remotely, one unforeseen mishap can jeopardize everything you’ve built. Commercial leases and client contracts throughout Tampa almost universally mandate this coverage, making general liability insurance Tampa an indispensable tool for survival and growth.
With over 60 years of combined family experience in Florida’s complex insurance market, we at Florida All Risk Insurance possess a deep, nuanced understanding of the unique risks Tampa businesses face. We’ve guided thousands of local entrepreneurs in securing the robust general liability protection they need to operate with confidence and peace of mind.
Key terms for general liability insurance Tampa:
- what does general liability insurance cover
- general liability insurance cost
- general liability insurance for small business
What is General Liability Insurance and What Does It Cover?

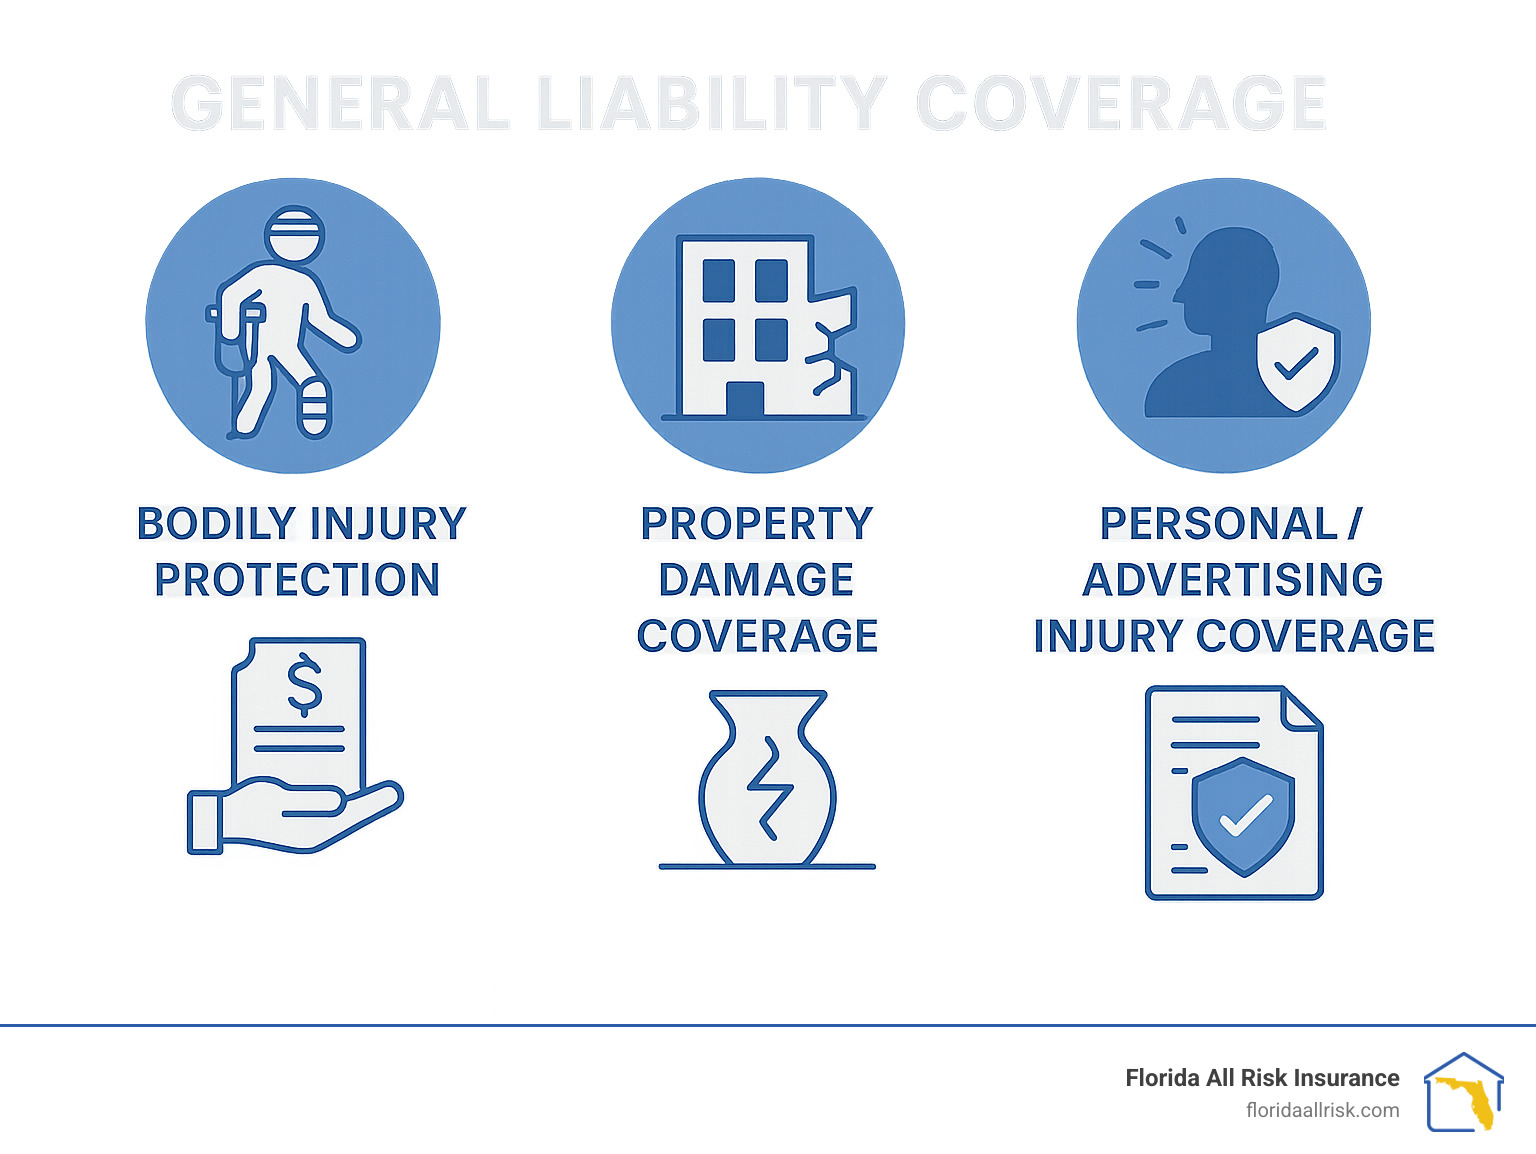
Commercial General Liability (CGL), the formal name for general liability insurance Tampa, is the foundational policy designed to shield your business from the everyday risks of interacting with the public. It protects your financial assets when your business is alleged to be legally responsible for causing injury to a non-employee or damaging their property. Think of it as the bedrock of your company’s risk management strategy.
Key coverages include:
-
Bodily Injury: This is one of the most common claims. It covers another person’s medical expenses, loss of income, and your legal fees if they are injured as a result of your business operations. For example, a customer in your Tampa coffee shop could slip on a freshly mopped floor and break their wrist. Or, a pedestrian walking past your construction site could be injured by a falling piece of debris. This coverage would respond to the subsequent medical bills and potential lawsuit.
-
Property Damage: This protection is for claims that your business caused damage to someone else’s property. It covers the cost of repair or replacement. Imagine your landscaping crew accidentally shatters a client’s large window with a rock thrown from a lawnmower, or your IT consultant knocks over and destroys a valuable server at a client’s office. These “oops” moments can be incredibly expensive, and this coverage is designed to handle those costs.
-
Personal and Advertising Injury: This vital coverage protects against non-physical damages. It defends your business against accusations of slander (damaging spoken statements), libel (damaging written statements), copyright infringement, misappropriation of advertising ideas, or invasion of privacy. A common example is using a photograph in your marketing materials without proper licensing, leading to a lawsuit from the photographer.
-
Medical Payments: This component of your policy can cover minor, immediate medical expenses for someone injured on your business premises, regardless of who was at fault. For instance, if a customer cuts their hand on a sharp corner of a display in your retail store, this coverage can pay for their stitches right away. It’s a goodwill gesture that can help prevent small incidents from escalating into major liability claims.
-
Legal Defense Costs: A significant benefit of a CGL policy is that it typically covers the costs of defending your business against a covered lawsuit. This includes hiring attorneys, court fees, and settlement costs, up to your policy limit. Crucially, this coverage often applies even if the lawsuit is ultimately found to be baseless. Legal defense alone can cost tens of thousands of dollars, making this protection invaluable.
-
Products-Completed Operations Coverage: This is a critical extension of GL coverage, especially for contractors, manufacturers, and restaurants. It protects your business from liability claims for bodily injury or property damage that occurs after you have completed a job or sold a product and left the premises. For example, if an improperly installed electrical outlet you fitted causes a fire a month later, this coverage would apply.
For a more comprehensive look, see our guide on What Does General Liability Insurance Cover?. You can also explore broader protection options on our Business Liability Insurance page.
What General Liability Does NOT Cover
Understanding the exclusions of a CGL policy is just as important as knowing what it covers. This knowledge helps you identify gaps in your risk management plan and secure the other types of insurance you need. According to the Insurance Information Institute (III), key exclusions include:
- Employee Injuries: Injuries sustained by your own employees on the job are explicitly excluded. These are covered by a separate, and often legally required, Workers’ Compensation insurance policy.
- Professional Mistakes: If your business provides professional advice or services (e.g., as an architect, lawyer, or consultant), general liability won’t cover financial losses a client suffers due to an error or omission in your work. For this, you need Professional Liability insurance, also known as Errors & Omissions (E&O) insurance.
- Commercial Auto Accidents: Any accident involving a vehicle used for business purposes—whether it’s a fleet of construction trucks or a single car used for deliveries—must be covered by a dedicated Commercial Auto Insurance policy.
- Intentional Acts: The policy will not cover bodily injury or property damage that you or your employees cause intentionally. Insurance is designed for accidents and negligence, not deliberate harm.
- Damage to Your Own Property: General liability covers damage to third-party property. Damage to your own business property, such as your building, equipment, or inventory, is covered by Commercial Property insurance.
- Punitive Damages: While CGL covers compensatory damages, it often limits or excludes punitive damages, which are awarded by courts to punish a defendant for particularly reckless or egregious behavior. Florida law has specific statutes governing the awarding of punitive damages.
Is General Liability Insurance Required for Tampa Businesses?
While the state of Florida does not have a universal law mandating that every business carry general liability insurance, it is a practical necessity for operating a successful and sustainable business in Tampa. The modern business ecosystem, driven by risk management best practices, has effectively made it a mandatory requirement.
Attempting to operate without general liability insurance Tampa coverage is not only risky but also nearly impossible for several key reasons:
-
Contractual Obligations: This is the most common driver. Before signing a contract for your services, most clients, especially larger corporations or government entities, will require you to provide a Certificate of Insurance (COI) as proof of coverage. This is a non-negotiable part of their vendor qualification process, designed to protect them from liability arising from your work.
-
Commercial Leases: If you plan to rent any commercial space in Tampa—be it an office, a warehouse, or a retail storefront—your lease agreement will almost certainly contain a clause mandating that you carry general liability insurance. Landlords need to protect their significant property investment from potential liability claims that could originate from their tenants’ business operations. They will typically ask to be named as an “additional insured” on your policy.
-
Client and Vendor Requirements: It has become a standard part of due diligence for businesses to work only with insured partners. Lacking coverage signals that you are not a serious or professional operator, and it can lead to you losing out on valuable projects, partnerships, and clients who are not willing to take on the risk of working with an uninsured vendor.
-
Licensing and Permitting: For many professions, particularly in the construction and skilled trades, proof of general liability insurance is a prerequisite for obtaining or maintaining a professional license in Florida and Hillsborough County. For contractors, this coverage is absolutely critical. You can learn more on our dedicated Contractors General Liability Insurance Tampa page. For local requirements, it’s wise to check with the Hillsborough County business resources.
The bottom line is that while a state trooper won’t pull you over for not having a CGL policy, the practical demands of the marketplace make it an essential asset. For official information on Florida’s insurance regulations, you can always consult the Florida Department of Financial Services.
Florida Laws and Tampa-Specific Requirements
Florida’s legal framework, particularly statutes found in Chapter 624 (Insurance Code: Administration and General Provisions) and Chapter 627 (Insurance Rates and Contracts), establishes the core principle that businesses are financially responsible for the damages they cause to others. This inherent liability makes insurance not just a contractual requirement, but a prudent financial decision to protect your business from solvency-threatening lawsuits.
In Tampa specifically, the competitive commercial real estate market means landlord insurance requirements are particularly stringent. Furthermore, while the city’s business resources are designed to be supportive of entrepreneurs, they are built on a foundation of smart risk management. Proper insurance is the cornerstone of that strategy. The practical realities of running a business in Tampa—from client demands and vendor partnerships to lease agreements and licensing—make general liability insurance Tampa coverage a non-negotiable part of your business’s foundation.
The Cost of General Liability Insurance Tampa: A Detailed Breakdown
One of the first and most pressing questions Tampa business owners ask is, “How much will this cost?” The encouraging news is that for the immense protection it provides, general liability insurance Tampa is often more affordable than many entrepreneurs anticipate. While every policy is unique, most small businesses in Tampa can expect to pay around $49 per month, which translates to about $588 annually. For businesses in higher-risk sectors like construction, the range is typically between $50 to $100 per month.
These figures are averages and should be used as a starting point for budgeting. Your final premium will be custom to your business’s specific risk profile. Insurance pricing is a highly customized process based on a careful assessment of numerous risk factors. For more details on how these costs are calculated, our General Liability Insurance Cost page offers a deeper analysis, and you can review general information on understanding small business insurance costs from reputable financial sources.
Key Factors That Influence Your Tampa Premium
Your premium is not an arbitrary number; it’s calculated based on a combination of factors that help insurers quantify your business’s level of risk:
-
Industry and Business Type: This is the single most significant factor. An office-based IT consultant faces far fewer physical liability risks than a roofing contractor working at heights, and their premiums will reflect that difference. Insurers use industry codes to classify businesses based on historical claims data.
-
Business Location: A retail storefront in a high-foot-traffic area like Ybor City or International Plaza carries different risks (like slip-and-falls) than a business operating out of a quiet office park in the suburbs. The specific risks associated with your physical location in Tampa are factored into your rate.
-
Claims History: Your business’s track record is crucial. A clean history with no prior liability claims demonstrates effective risk management and can lead to lower rates, often called a claims-free discount. Conversely, a history of frequent claims will signal higher risk to insurers and likely increase your premium.
-
Coverage Limits: The amount of protection you choose to purchase directly impacts the cost. A standard policy might offer limits of $1 million per occurrence (the maximum paid for a single incident) and $2 million in aggregate (the total maximum paid during the policy term). Higher limits will increase the premium but provide greater protection.
-
Deductible Amount: The deductible is the amount you agree to pay out-of-pocket on a claim before the insurance coverage kicks in. Choosing a higher deductible (e.g., $2,500 instead of $500) shows you are willing to share more of the risk, which will lower your premium. However, you must be sure you can comfortably afford the deductible if a claim occurs.
-
Business Size (Employees & Revenue): The scale of your operation matters. A business with more employees and higher annual revenue generally has greater exposure to potential claims simply due to a higher volume of activity, customer interactions, and work performed. This increased exposure can influence the final cost.
Average Monthly Premiums in Tampa by Industry
This table provides estimated monthly premiums for general liability insurance Tampa based on general industry risk levels. Use these as a guide for planning purposes.
| Industry Type | Risk Level | Estimated Monthly Premium (Tampa) |
|---|---|---|
| Consulting/IT Services | Low-Risk | $25 – $40 |
| Retail Store | Medium-Risk | $40 – $60 |
| Restaurant/Cafe | Medium-Risk | $60 – $85 |
| Landscaping/Cleaning | Medium-High Risk | $70 – $100 |
| Construction/Contractor | High-Risk | $80 – $120+ |
These are estimates for planning purposes. Your actual quote will depend on your specific business details, claims history, and chosen coverage limits.
Who Needs General Liability Insurance in Tampa and How to Get It
If you operate a business in the Tampa Bay area that interacts with the public in any capacity, you need general liability insurance Tampa. This applies whether clients visit your physical location, you visit clients at their properties, or your interactions are primarily digital. Even seemingly “low-risk” home-based businesses face potential claims, from a delivery person tripping on your porch to an accidental case of libel in a marketing email.
A crucial document you’ll become familiar with is the Certificate of Insurance (COI). Clients, landlords, and event organizers will frequently request a COI as proof that you have active coverage before they will agree to work with you. Our resource on Tampa General Liability Insurance for Small Business provides more detail on these common requirements.
Common Tampa Businesses That Need Coverage
Virtually every industry benefits from this fundamental protection. Some of the most common businesses in Tampa that require it include:
- Contractors: General contractors, electricians, plumbers, and roofers are constantly exposed to high-stakes risks of property damage at job sites and potential injuries to clients or the public.
- Restaurants and Bars: The combination of high foot traffic, food service, and (often) alcohol creates a high-risk environment for slip-and-falls, foodborne illness claims, and other incidents common in Tampa’s vibrant dining scene.
- Retail Stores: Any business with customers on its premises, from a boutique in SoHo to a large furniture store, needs protection against accidents like slips, trips, or injuries caused by falling merchandise.
- Landscapers and Janitorial Services: Working on client properties with heavy equipment, tools, and chemicals creates numerous scenarios for property damage or third-party injury.
- Consultants and Real Estate Agents: Professionals who meet with clients in an office or at various properties need coverage for potential accidents during those visits, as well as for advertising injury claims related to their marketing efforts.
- Event Planners and Vendors: Coordinating vendors, venues, and large crowds for events at locations like the Tampa Convention Center or local parks introduces a wide array of liability risks that must be properly insured.
- Health and Wellness Professionals: Personal trainers, massage therapists, and yoga instructors need coverage in case a client is injured during a session.
How to Get a General Liability Insurance Tampa Quote
Securing a quote for your Tampa business is a straightforward process. We have streamlined it to be as efficient and transparent as possible.
- Gather Your Business Information: To provide an accurate quote, you’ll need some basic details on hand. This includes your official business name and address, your industry and specific services, your estimated annual revenue, and your total payroll (if you have employees).
- Contact Our Independent Agency: As an independent insurance agency, we are not tied to a single carrier. We work for you. We take your information and submit it to multiple top-rated insurance carriers that specialize in your industry. This creates competition for your business.
- Review Your Customized Options: We will present you with the best quotes we receive. We’ll walk you through the options, clearly explaining the coverage limits, deductibles, any endorsements or exclusions, and the final premium. Our goal is to ensure you understand exactly what you are buying.
- Bind Coverage and Get Your COI: Once you select the policy that best fits your needs and budget, we handle all the necessary paperwork to “bind” the coverage, which means putting the policy into effect. We can then immediately issue your policy documents and any Certificates of Insurance (COIs) you need for your clients or landlord.
Our team has over 60 years of combined experience in the Florida market and is ready to help you secure the right protection for your unique Tampa business.
Smart Strategies to Reduce Your Insurance Premiums
While insurance is a non-negotiable expense for a responsible business, the premium amount is not set in stone. There are several effective, proactive strategies you can implement to lower your general liability insurance Tampa premiums without compromising on essential protection.
Here are some of the smartest strategies we recommend to our Tampa clients:
-
Implement and Document Strong Safety Protocols: Insurers reward businesses that are proactive about preventing accidents. Create a formal, written safety plan. This could include documented procedures for daily floor inspections to prevent slips, regular training on equipment safety for employees, and maintaining a clean, organized workplace. A documented safety culture is a powerful tool for premium reduction.
-
Maintain a Clean Claims History: Your claims history is a direct reflection of your risk level. The best way to keep premiums low is to prevent claims from happening in the first place. A history free of claims demonstrates that you are a low-risk client, which can qualify you for significant claims-free discounts over time.
-
Bundle Your Policies into a BOP: Insurers often provide a discount for purchasing multiple policies from them. For many small to medium-sized Tampa businesses, a Business Owner’s Policy (BOP) is an excellent option. A BOP conveniently bundles general liability and commercial property insurance into a single, more affordable package. It can often include business interruption insurance as well.
-
Choose a Higher Deductible: If your business has a healthy cash flow and can comfortably cover a larger one-time expense, opting for a higher deductible can significantly reduce your monthly premium. By agreeing to pay more out-of-pocket in the event of a claim (e.g., $2,000 vs. $500), you are sharing more of the risk with the insurer, who in turn will lower your rate.
-
Conduct Annual Policy Reviews: Your business is not static; it evolves. An annual policy review with your insurance agent is crucial. Perhaps your revenue has changed, you’ve added or removed services, or you’ve implemented new safety measures. A review ensures your coverage still aligns with your current operations and that you’re taking advantage of any new discounts for which you may now qualify.
-
Work with an Independent Insurance Agent: Unlike a captive agent who only represents one company, an independent agent works for you. We have access to a wide range of insurance carriers. This allows us to shop your policy across the market to find the most competitive pricing and coverage options available, ensuring you don’t overpay.
These strategies not only save you money on your general liability insurance Tampa policy but also contribute to making your business safer, more resilient, and more attractive to partners and clients. To help determine your specific coverage needs, see our guide on How Much General Liability Insurance Do I Need?.
Frequently Asked Questions about General Liability Insurance in Tampa
Over our decades of service, we’ve answered thousands of questions about general liability insurance Tampa. Here are clear, straightforward answers to the most common inquiries we receive from local business owners.
How much is a $1 million general liability policy in Tampa?
A standard policy with a $1 million per occurrence limit and a $2 million aggregate limit—the most common structure for small businesses—costs an average of $69 per month or $824 annually in Tampa. However, this price is highly dependent on your industry. A low-risk home-based consultant might pay as little as $25 per month, while a high-risk roofing contractor could see premiums of $80 to $120+ per month. The final cost is a direct reflection of your business’s specific operations and risk exposure.
Does general liability insurance cover my employees if they get hurt on the job?
No. This is a critical and common point of confusion. General liability insurance is designed to cover third-party claims—that is, injuries to non-employees like customers, clients, vendors, or passersby. Injuries to your own employees that occur in the course of their work are covered by a completely separate policy: Workers’ Compensation insurance. In Florida, workers’ comp is legally required for most businesses with four or more employees (and for any business in the construction industry with even one employee).
What is the difference between general liability and professional liability insurance?
The simplest way to distinguish them is to think physical harm vs. financial harm.
- General Liability Insurance primarily covers claims of physical events: bodily injury to a person or damage to someone else’s property. It also includes coverage for “personal and advertising injury” like slander, libel, or copyright infringement.
- Professional Liability Insurance, often called Errors & Omissions (E&O), covers claims of financial loss a client suffers because of your professional negligence, errors in your service, or failure to deliver on promised outcomes. If your advice as a consultant or a mistake in your design as an architect causes a client to lose money, this is the policy that would respond. Many Tampa businesses, especially in service-based industries, need both policies for comprehensive protection.
What is a Certificate of Insurance (COI) and why do I need one?
A Certificate of Insurance (COI) is a one-page document that serves as proof of your insurance coverage. It summarizes your policy, including the type of coverage, the policy limits, and the effective dates. In Tampa, you will constantly be asked for a COI by landlords before signing a lease, by clients before starting a project, and by municipalities before issuing certain permits. It’s an essential tool for doing business.
Does my home-based business in Tampa still need general liability insurance?
Yes, in most cases. A standard homeowner’s insurance policy typically provides very limited or no coverage for business-related activities. If a client comes to your home for a meeting and trips on your steps, or if a delivery person is injured while dropping off a business package, your homeowner’s policy will likely deny the claim. A general liability policy is necessary to cover these business-specific risks.
What is the difference between an ‘occurrence’ and a ‘claims-made’ policy?
This determines when a claim is covered. Most general liability policies are occurrence policies. This means they cover incidents that happen during the policy period, regardless of when the claim is actually filed. A claims-made policy, more common for professional liability, only covers claims that are filed during the policy period. Occurrence policies provide broader, longer-term protection.
Conclusion
For any business operating in Tampa, from the smallest startup to an established enterprise, general liability insurance Tampa is not merely an expense—it is a foundational asset for financial survival and responsible growth. It is the shield that protects the business you have worked so hard to build from the ever-present risks of claims related to bodily injury, property damage, and personal injury that can arise from your daily operations.
From the restaurants in Ybor City and the retail shops in Hyde Park to the vast network of construction crews and consultants across Tampa Bay, the risks are real and varied. For an average cost that can be as low as $49 per month, you can secure protection that may save you from hundreds of thousands of dollars in legal fees and settlements. With this coverage being a standard requirement for leases, contracts, and licenses, it is an essential key to open uping business opportunities.
At Florida All Risk Insurance, our family brings over 60 years of combined experience to the table, helping businesses in St. Petersburg, Tampa, and across Florida steer these complex risks. We don’t just sell policies; we act as your dedicated partners in risk management, taking the time to find the right protection so you can focus on what you do best: running your business with confidence and peace of mind.
Don’t leave your business’s future to chance. Let our experienced, independent team shop the market to find a policy that fits your specific needs and budget.
Get your custom general liability insurance quote today and take the most important step toward securing your business’s financial future.
Contact Us:
Florida All Risk Insurance
Saint Petersburg, FL
Phone: (727) 240-2148
Email: [email protected]
Website: joea233.sg-host.com/

