

Excess public liability is an extra layer of protection for your business when large claims go beyond the limits of your primary insurance. Here’s a quick look at what this means:
- Primary Insurance: The first line of defense, covering financial liabilities up to a certain limit.
- Excess Public Liability: Provides additional coverage once your primary insurance is exhausted.
Excess public liability is particularly crucial for those facing unexpected, large-scale incidents like injury claims, offering financial protection when it’s needed most.
Florida homeowners may not think they need excess public liability, but in a world where lawsuits are common, this coverage can prevent a financial disaster. For business owners, it’s a safeguard against potential bankruptcy caused by large claims.
I’m Jason Miller, a second-generation insurance professional with over 20 years of expertise in excess public liability. My experience in Florida’s dynamic insurance market enables me to guide you in maximizing your coverage. Let’s dig into the nuances of excess public liability to better protect what matters most to you.

Must-know excess public liability terms:
– public liability risk
– general liability insurance
– high risk general liability insurance
Understanding Excess Public Liability
Excess public liability is an essential part of a comprehensive insurance strategy, especially for businesses facing high-stakes risks. It acts as a financial safety net, stepping in when your primary liability insurance reaches its coverage limits. Here’s how it works:
Coverage Limits and Underlying Policy
Every insurance policy has a coverage limit—the maximum amount your insurer will pay for a claim. Once this limit is exhausted, you could be left covering the rest out of pocket. This is where excess public liability comes into play.
- Underlying Policy: This refers to your initial insurance policy, such as general liability or auto insurance, which covers risks up to a specified limit.
- Excess Public Liability: Kicks in after your primary policy’s limit is reached, providing additional coverage for large claims.
For example, imagine a scenario where a customer slips on a wet floor in your business premises and sustains severe injuries. Your general liability insurance might cover up to $1 million, but the total claim could exceed that amount. Excess public liability would cover the additional costs, protecting your business from financial strain.
Why It’s Important
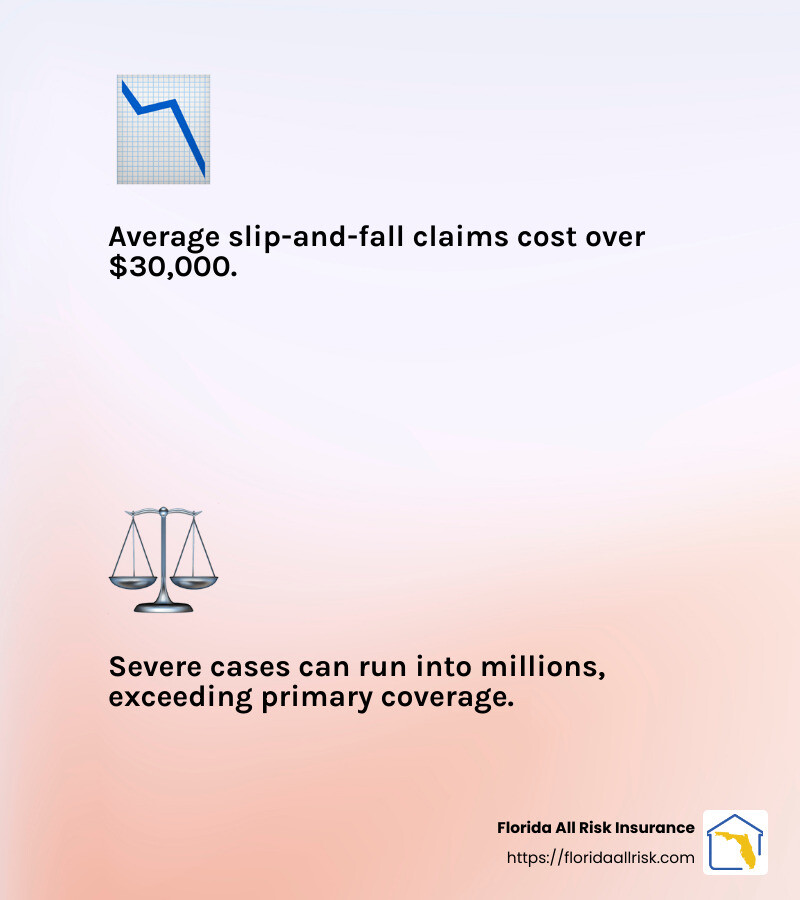
In today’s litigious society, even small businesses can face lawsuits resulting in claims that exceed their primary insurance coverage. According to industry data, the average cost of a slip-and-fall injury claim can easily surpass $30,000, and severe cases can run into millions.
Excess public liability is not just for large corporations. Even small businesses in Florida, from cafes to retail stores, can benefit from this additional layer of protection. It ensures that a single incident doesn’t threaten your financial stability or business continuity.
Real-World Example
Consider a case where a heating and cooling technician fell through an attic floor, resulting in multiple injuries. The claim, settled under the homeowner’s excess liability insurance, totaled $8.9 million. Without excess coverage, the homeowner could have faced severe financial consequences.
In summary, excess public liability fills the gap when primary insurance falls short. It offers peace of mind, knowing that you have extra protection against unexpected, costly claims. Next, we’ll explore how excess liability differs from umbrella insurance and what each can offer your business.
Key Differences: Excess Liability vs. Umbrella Insurance
When it comes to protecting your business, choosing the right insurance can be tricky. Two options often discussed are excess liability and umbrella insurance. Let’s break down the key differences.
Umbrella Insurance: Broader Coverage Across Multiple Policies
Umbrella insurance is like a big, protective shield. It extends the coverage of multiple primary policies at once. Think of it as a safety net that covers a wide range of risks, often including things like general liability, auto insurance, and even workers’ compensation.
-
Broader Coverage: Umbrella policies can sometimes cover situations that your primary policies don’t. For example, they might include protection against claims like slander or libel, which aren’t typically covered by standard liability policies.
-
Multiple Policies: With umbrella insurance, you can extend the limits of several policies simultaneously. This means you don’t need to buy separate excess coverage for each policy. It’s a convenient option for businesses with diverse insurance needs.
Excess Liability: Focused on One Underlying Policy
Excess liability insurance, on the other hand, is more straightforward. It provides additional coverage for just one primary policy. If you have a general liability policy and want extra coverage, excess liability can boost that policy alone.
-
Single Policy Focus: Unlike umbrella insurance, excess liability is tied to one specific policy. If you need extra coverage for multiple policies, you’ll need to buy separate excess policies for each.
-
No Broader Coverage: Excess liability strictly extends the limits of the policy it’s attached to. It doesn’t offer additional protections beyond what’s covered in the primary policy.
When to Choose Which?
-
Umbrella Insurance is ideal if you want comprehensive protection across multiple areas of your business. It’s particularly useful for businesses with varied operations or those exposed to diverse risks.
-
Excess Liability is a good choice if you need to boost the coverage of just one policy. It’s often more cost-effective if you only need extra coverage for a specific risk.
In summary, both umbrella insurance and excess liability offer valuable protection. The right choice depends on your business’s unique needs and the types of risks you face. Understanding these differences can help you maximize your coverage and ensure financial peace of mind.
Next, we’ll discuss when it might be a smart move to consider excess public liability insurance for your business.
When to Consider Excess Public Liability Insurance
Knowing when to invest in excess public liability insurance can make a big difference in your business’s financial safety net. Here are some scenarios where it might be a smart move:
1. Frequent Liability Risks
If your business involves high foot traffic or frequent customer interactions, you face more liability risks. Imagine a busy café or retail store where accidents like slips or falls could happen. In such environments, having extra coverage beyond your basic liability policy can be crucial.
2. Significant Risks
Businesses involved in high-risk activities should consider excess public liability. For example, if you manufacture flammable products or operate heavy machinery, the potential for significant claims is higher. In these cases, your primary insurance might not be enough to cover all possible damages. Excess coverage acts as an added layer of financial protection.
3. Industry-Specific Coverage Needs
Certain industries have unique risks that may require specialized insurance. For instance, if you’re in the tech industry, cybersecurity threats could pose a major liability. Or, if you’re in construction, accidents on-site could lead to costly claims. In these situations, excess public liability can provide the additional coverage needed to handle industry-specific risks.
Real-Life Example
Consider a hazardous materials hauler. They might have general liability and commercial auto policies but still need extra coverage for pollution-related incidents. An excess policy custom to their industry ensures they are protected from all angles.
In summary, businesses with frequent, significant, or industry-specific risks should weigh the benefits of excess public liability insurance. It provides peace of mind by covering potential gaps in your primary policies, ensuring you’re prepared for any unexpected events.
Next, we’ll tackle some frequently asked questions about excess public liability to help clarify any lingering doubts.
How Excess Public Liability Works
Understanding how excess public liability functions is key to maximizing your coverage and ensuring your business is well-protected.
Per-Claim Limit
Every insurance policy comes with a per-claim limit. This is the maximum amount your insurer will pay for a single claim. For instance, if your primary liability policy has a per-claim limit of $1 million and a claim arises for $1.5 million, your primary insurance will cover the first $1 million. This is where excess public liability steps in to cover the remaining $500,000, ensuring you aren’t left to pay out of pocket.
Aggregate Limit
In addition to per-claim limits, there’s also an aggregate limit. This is the total amount your policy will cover over a policy period, usually a year. If your primary policy’s aggregate limit is reached, any further claims within that period would initially go unpaid. However, with excess public liability, you have an additional layer of protection. This excess coverage kicks in once the aggregate limit of your primary policy is exhausted, providing continued financial security.
Financial Protection
The primary goal of excess public liability is financial protection. It safeguards your business from large claims that could otherwise lead to significant financial strain. By covering costs that exceed the limits of your primary policy, it helps prevent a legal suit from turning into a financial disaster. This extra layer of security ensures that your business can withstand unexpected and costly claims without jeopardizing its financial health.
Excess public liability acts as a financial safety net. It provides peace of mind, knowing that your business is protected from claims that exceed your primary policy limits. This coverage is crucial for businesses that face high risks or operate in industries with unique liability challenges.
Next, we’ll dive into some frequently asked questions about excess public liability to further clarify its benefits and applications.
Frequently Asked Questions about Excess Public Liability
What’s the Difference Between Umbrella and Excess?
Umbrella policies and excess policies both provide extra liability coverage, but they aren’t quite the same. An umbrella policy offers broader protection. It can cover multiple underlying policies, like auto, home, or watercraft insurance. This means if you have various insurance policies, an umbrella policy can extend the coverage limits on all of them.
On the other hand, an excess policy is more focused. It boosts the coverage of a single underlying policy, typically a general liability policy. So, if you have a specific area of risk that needs extra attention, an excess policy might be the right choice.
Is Personal Excess Liability Coverage Worth It?
Deciding if personal excess liability coverage is worth it depends on your situation. It provides extra protection for unexpected costs that exceed your primary policy’s limits. Consider those rare but costly scenarios, like a severe car accident or a major lawsuit. Without this extra coverage, you might have to pay out of pocket, which can be financially devastating.
If you own valuable assets, engage in high-risk activities, or simply want peace of mind, personal excess liability coverage can be a wise investment. It acts as a financial buffer, protecting you from potentially crushing expenses.
How to Explain Excess Insurance?
Excess insurance is like a safety net for your primary insurance policies. When your main policy hits its limit, excess insurance steps in to cover the rest. It’s particularly useful for unique risks or high-risk activities that might lead to expensive claims.
Imagine you’re running a business that involves heavy machinery. The chance of accidents might be higher, and a single claim could easily exceed your primary coverage. This is where excess insurance becomes crucial. It ensures you’re not left financially vulnerable when your primary policy’s limits are maxed out.
In short, excess insurance provides an extra layer of financial protection. It’s designed to cover those unexpected, high-cost claims that your regular policy can’t fully handle. This way, you can focus on running your business or living your life without worrying about what might happen if things go wrong.
Conclusion
When it comes to protecting your business or personal assets, having the right insurance coverage is essential. At Florida All Risk Insurance, we understand that each client has unique needs and risks. That’s why we offer comprehensive solutions custom to fit your specific situation.
Excess public liability insurance is an important piece of the puzzle. It provides that crucial extra layer of protection above your primary insurance limits, safeguarding you from financial setbacks due to large claims. Whether it’s for your business or personal assets, this coverage helps ensure peace of mind.
Our team in Saint Petersburg, Florida, is dedicated to providing custom coverage options that work best for you. We leverage our access to a variety of carriers to offer competitive rates and personalized service. This means you get the coverage you need without paying for extras you don’t.
If you’re considering excess public liability insurance or want to learn more about how it can benefit you, we’re here to help. Our experts are ready to guide you through the options and find the best fit for your needs.
Explore our general liability insurance solutions to see how we can help protect what matters most to you.

