

business insurance panama city fl: Don’t Risk It 2026
Why Your Panama City Business Can’t Afford to Be Uninsured
Business insurance Panama City FL is essential protection for any company operating in this dynamic coastal market. Whether you run a restaurant on the beach, a construction company, or a professional services firm, the right insurance safeguards your livelihood from lawsuits, natural disasters, cyberattacks, and employee injuries.
Quick Answer: Essential Business Insurance in Panama City, FL
- General Liability Insurance – Protects against customer injury claims and property damage lawsuits
- Commercial Property Insurance – Covers your building, inventory, and equipment from fire, theft, and hurricanes
- Workers’ Compensation – Required by Florida law if you have employees; covers work injuries
- Commercial Auto Insurance – Mandatory for company vehicles; covers accidents and vehicle damage
- Business Owner’s Policy (BOP) – Cost-effective bundle combining liability and property coverage for small businesses
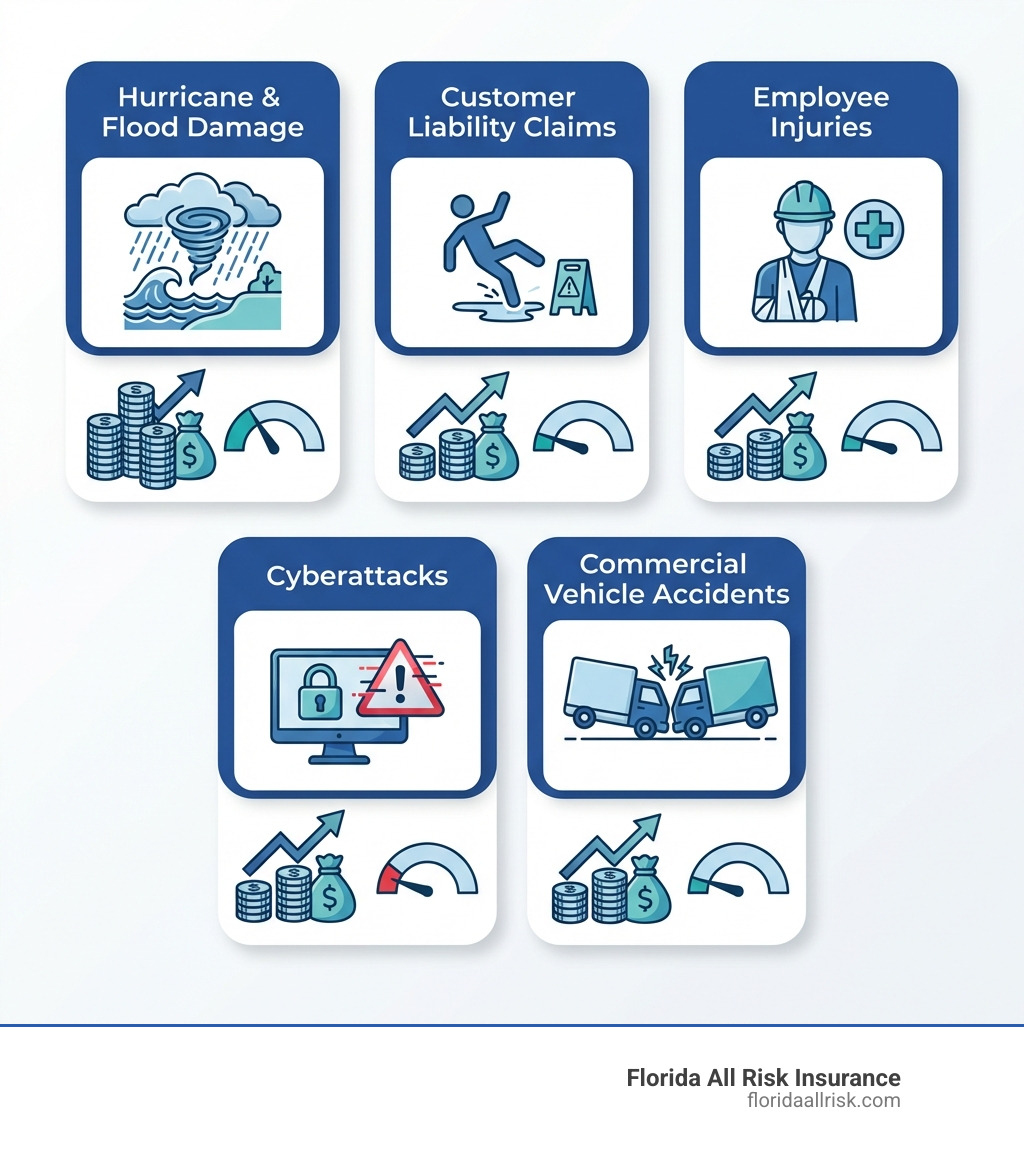
Running a business in Panama City comes with unique challenges. Your coastal location means hurricane risk is real and constant. Your tourism-driven economy creates heavy foot traffic and increased liability exposure. And like businesses everywhere, you face growing threats from cyberattacks and employment-related lawsuits.
The numbers tell a sobering story. Small businesses across the country face a 20% increase in liability lawsuits. Natural disasters caused over $110 billion in damages nationwide in 2023. And cyberattacks have jumped 23% among small businesses in just the last year.
Without proper insurance, a single lawsuit or hurricane could wipe out everything you’ve built. One slip-and-fall accident, one kitchen fire, one data breach – any of these can result in costs that far exceed what most small businesses can afford to pay out of pocket.
The good news? The right insurance portfolio transforms these risks from business-ending threats into manageable, covered events. You get back to work while your insurance handles the financial fallout.
I’m Jason Miller, and I’ve spent over 20 years helping Florida businesses protect themselves with comprehensive business insurance in Panama City, FL and throughout the state. From my family’s 60+ years of combined insurance experience, I’ve guided thousands of business owners through the process of building smart, affordable protection plans that actually work when disaster strikes.
Glossary for business insurance panama city fl:
A Guide to Essential Business Insurance Policies in Panama City
This section covers the foundational insurance types that most businesses in Panama City need to operate safely and legally. We’ll explore each type, detailing what it covers and why it’s a non-negotiable part of your business’s defense strategy.
General Liability Insurance: Your First Line of Defense
Imagine a customer slips on a wet floor in your Panama City restaurant, or one of your employees accidentally damages a client’s property during a service call. These “uh-oh moments,” as we like to call them, are precisely what General Liability (GL) insurance is designed to protect against.
General liability insurance is often considered the bedrock of any business insurance Panama City FL policy. It shields your business from claims of bodily injury, property damage, and even personal and advertising injury (like libel or slander) that can arise during your day-to-day operations. When such an incident occurs, GL insurance can cover the associated legal defense costs, settlements, and judgments, potentially saving your business from financial ruin.
Consider this: small businesses face an alarming 20% increase in liability lawsuits. This statistic alone highlights the critical importance of having robust general liability coverage. Without it, a single lawsuit could drain your business’s resources and jeopardize its future. It’s not just about protecting against major disasters; it’s about safeguarding your business from the everyday risks that can escalate quickly.
Commercial Property Insurance: Protecting Your Physical Assets
For businesses in Panama City, your physical location, inventory, and equipment are the lifeblood of your operation. Commercial property insurance is specifically designed to protect these vital assets. It covers your building and structures, inventory and stock, furniture and equipment, and even your business signage from a range of perils.
Given Panama City’s coastal location, this type of insurance is particularly crucial. Hurricanes, tropical storms, and their associated wind and water damage are significant threats. While standard commercial property policies may cover wind damage, understand flood coverage, which often requires a separate policy or endorsement. We work with you to ensure your policy is custom to Florida’s unique exposures, providing comprehensive protection against natural disasters.
When considering commercial property insurance, you’ll often encounter two valuation methods: Actual Cash Value (ACV) and Replacement Cost. Understanding the difference is vital:
- Actual Cash Value (ACV): This method pays for the cost to replace damaged property minus depreciation. Essentially, it considers the age and wear and tear of your property.
- Replacement Cost: This method pays for the cost to replace damaged property with new property of similar kind and quality, without any deduction for depreciation. This is generally the preferred option, as it allows you to fully restore your business without being out-of-pocket for depreciation.
For a deeper dive into these valuation methods, you can read more about Actual Cash Value (ACV) and Replacement Cost on Investopedia.
| Valuation Method | Description | Payout for $50,000 Equipment Loss (5 years old, 10% annual depreciation) |
|---|---|---|
| Actual Cash Value | Replaces property at its current market value, accounting for depreciation. | $25,000 (after 50% depreciation) |
| Replacement Cost | Replaces property with new items of similar kind and quality, no depreciation. | $50,000 |
Another important concept to grasp is the coinsurance penalty. This is a clause in commercial property policies that requires you to insure your property for a certain percentage of its total value (e.g., 80%, 90%, or 100%). If you fail to insure your property to this required limit, you may face a penalty, meaning your insurer will only pay a portion of your covered loss, even if it’s less than your policy limit. For example, if your building is worth $100,000 and has an 80% coinsurance clause, but you only insure it for $60,000, your insurer might only pay 75% of your loss (60,000/80,000) minus your deductible. We always help our clients understand these clauses to avoid unpleasant surprises.
With natural disasters causing over $110 billion in damages nationwide in 2023, having the right commercial property insurance is not just smart business; it’s a necessity for survival in a region prone to severe weather.
Workers’ Compensation Insurance: A Florida Requirement
If your Panama City business has employees, then workers’ compensation insurance isn’t just a good idea – it’s generally a legal requirement in Florida. This crucial coverage provides financial benefits to employees who suffer work-related injuries or illnesses.
Workers’ compensation covers an injured employee’s medical expenses, a portion of their lost wages while they recover, and rehabilitation benefits. This helps ensure your employees receive the care they need without facing undue financial burden. From an employer’s perspective, workers’ comp protects your business from direct lawsuits by injured employees, as it typically provides exclusive remedy, meaning the employee cannot sue you for the injury if they accept workers’ comp benefits.
Florida law mandates workers’ compensation for most businesses with employees. The specific requirements can vary based on your industry and the number of employees you have. For example, most non-construction businesses need coverage if they have four or more employees, while construction businesses often need it with just one employee. Understanding these nuances is where our expertise comes in. We can help you steer Florida’s specific regulations and ensure your business remains compliant. For more information on Florida’s workers’ compensation landscape, you can explore our resources on 2026 florida workers compensation rates and workers comp rate florida.
Commercial Auto Insurance: Coverage for Business on the Move
Does your Panama City business use vehicles for operations? Perhaps you have delivery vans, service trucks, or even just a car for client meetings. If so, commercial auto insurance is not just recommended, it’s mandatory for company-owned vehicles in Florida.
This policy provides essential protection for vehicles used for business purposes. It covers liability for accidents that cause injury to others or damage to their property. Beyond liability, it can also provide physical damage coverage for your business vehicles, including collision and comprehensive coverage, protecting your investment in your fleet.
It’s important to note that a personal auto insurance policy is typically insufficient for vehicles used for business operations. Personal policies usually have exclusions for commercial use, which means if an accident occurs while you’re conducting business, your personal policy might deny the claim. Commercial auto insurance can also extend to “hired and non-owned auto coverage,” which protects your business if an employee uses their personal vehicle for work-related tasks or if you rent a vehicle for business use. This ensures that your business is protected regardless of who owns the vehicle being used for work.
Business Interruption Insurance: Staying Afloat When Disaster Strikes
Panama City businesses know the devastating impact unexpected events can have, especially natural disasters. While commercial property insurance helps you rebuild, what about the income you lose while your business is temporarily shut down? That’s where business interruption insurance, also known as business income insurance, steps in.
This vital coverage helps your business recover from unexpected events by covering lost income during temporary shutdowns caused by a covered property loss (like a fire or hurricane damage). It doesn’t just replace lost profits; it also helps pay for ongoing operating expenses, such as rent, utilities, and payroll, that continue even when your doors are closed. This means you can keep your key employees, maintain your lease, and be ready to reopen as quickly as possible.
For Panama City businesses, business interruption insurance is particularly critical for hurricane recovery. After a major storm, cleanup and rebuilding can take weeks or months. Without business interruption coverage, the financial strain during this period could be impossible. It’s the safety net that allows you to focus on getting back on your feet without the added stress of immediate financial collapse.
Advanced & Specialized Insurance for Modern Panama City Businesses
As your business grows or if you operate in a specific niche, you may need more than just the basic policies. Modern businesses face a complex array of risks that demand specialized protection. We’ll dig into the advanced insurance solutions that can provide a comprehensive shield for your unique operations.
The Business Owner’s Policy (BOP): A Smart Bundle for Small Businesses
For many small to medium-sized, low-risk businesses in Panama City, a Business Owner’s Policy (BOP) is an excellent, cost-effective solution. Think of it as a convenient, all-in-one package that bundles essential coverages into a single policy.
A typical BOP combines General Liability and Commercial Property insurance, providing a robust foundation of protection. Critically, it often includes Business Interruption insurance as well, giving you that crucial safety net for lost income and ongoing expenses after a covered event. By combining these coverages, a BOP can simplify your insurance management and often result in premium savings compared to purchasing each policy separately. It’s designed to provide comprehensive protection without the complexity, making it an ideal choice for businesses looking for efficiency and value.
Professional Liability (E&O) Insurance: Protecting Your Expertise
If your Panama City business provides professional advice or services, then Professional Liability insurance, also known as Errors & Omissions (E&O) insurance, is indispensable. This coverage protects your business against claims of negligence, misrepresentation, or inaccurate advice that could lead to financial harm for your clients.
Consider professionals like consultants, accountants, real estate agents, architects, IT specialists, or even marketing agencies. In these service-based roles, your expertise directly impacts your clients’ decisions and outcomes. A simple oversight, a perceived error, or a misunderstanding can lead to a lawsuit, even if you’ve done nothing wrong. E&O insurance covers the legal defense costs and any settlements or judgments that may arise from such claims, safeguarding your professional reputation and financial stability. It’s about protecting your specialized knowledge and the trust your clients place in you.
Cyber Liability Insurance: Your Shield in the Digital Age
In today’s interconnected world, almost every business handles some form of digital data, whether it’s customer information, payment details, or proprietary business secrets. This makes cyber liability insurance a crucial component of any modern business insurance Panama City FL portfolio.
The threat is real and growing: cyberattacks have increased by a staggering 23% in small businesses over the last year. A data breach, ransomware attack, or other cybercrime can be devastating, leading to financial losses, reputational damage, and legal repercussions.
Cyber liability insurance covers the significant costs associated with such incidents. This can include expenses for notifying affected customers, providing credit monitoring services, forensic investigations to determine the cause and scope of the breach, public relations to manage reputational damage, and legal fees and fines. It’s a vital safeguard for any business that collects, stores, or transmits sensitive digital information, ensuring you can respond effectively and recover quickly from a cyber incident. For resources on cybersecurity best practices, we encourage you to consult reputable organizations like the U.S. Small Business Administration (SBA).
Employment Practices Liability Insurance (EPLI)
Running a business with employees, even just a few, opens you up to a different set of risks related to employment practices. Employment Practices Liability Insurance (EPLI) protects your business against claims from employees regarding various employment-related issues.
These claims can include allegations of discrimination (based on age, race, gender, religion, etc.), sexual harassment, wrongful termination, retaliation, failure to promote, and other employment-related disputes. Even if the claims are unfounded, the legal costs to defend against them can be substantial. EPLI covers these legal defense costs, as well as any settlements or judgments awarded. This coverage is important for businesses of any size with one or more employees, as employment laws are complex and frequently changing, making it easy for even well-intentioned employers to face accusations.
How to Find the Right Business Insurance in Panama City, FL
Finding the right coverage is a critical business decision. This section provides a step-by-step guide to navigating the process, ensuring you secure the protection your Panama City business truly needs.
Understanding the Cost of business insurance in panama city fl
The cost of business insurance Panama City FL is not a one-size-fits-all figure; it’s influenced by a variety of factors unique to your operation. Understanding these elements can help you prepare for the quoting process and make informed decisions:
- Industry and Associated Risks: High-risk industries (e.g., construction, manufacturing) typically pay more than lower-risk ones (e.g., professional services).
- Business Size and Number of Employees: Larger businesses with more employees generally have higher premiums due to increased exposure to liability and workers’ compensation claims.
- Annual Revenue and Payroll: These metrics help insurers assess your business’s scale and potential for claims.
- Physical Location and Building Construction: Proximity to coastal areas (like Panama City) can impact property insurance costs due to hurricane risk. The type of construction (e.g., concrete vs. wood frame) also plays a role.
- Claims History: A history of frequent or severe claims will likely lead to higher premiums.
- Selected Coverage Limits and Deductibles: Opting for higher coverage limits will increase your premium, while choosing a higher deductible can lower it (but means more out-of-pocket expense in case of a claim).
We work diligently to find you the most competitive rates without compromising on the quality of your coverage, ensuring you get the best value for your investment.
Choosing the Right Partner: Independent Agent vs. Direct Carrier
When seeking business insurance Panama City FL, you generally have two main avenues: working with a direct carrier or partnering with an independent insurance agent. We firmly believe that for comprehensive and personalized protection, an independent agent is your best ally.
- Independent Agents: Like us at Florida All Risk Insurance, independent agents work with multiple insurance carriers. This allows us to shop around on your behalf, compare policies from various providers, and find the best coverage and rates custom to your specific needs. We offer personalized advice, act as your advocate during the claims process, and provide ongoing support. Our local expertise means we understand Panama City’s unique market, risks, and regulations.
- Direct Carriers: These are companies that sell their own insurance products directly to consumers. While they can be convenient, they only offer their own policies, limiting your options and potentially missing out on better deals or more suitable coverage from other providers.
The value of local expertise in understanding Panama City’s unique market cannot be overstated. We understand the specific challenges and opportunities that businesses in the area face, from hurricane season preparedness to the nuances of a tourism-driven economy. For finding qualified, ethical agents in Florida, the Florida Association of Insurance Agents (FAIA) is an excellent resource.
Preparing for the Quote Process for your business insurance in panama city fl
To ensure a smooth and accurate quoting process for your business insurance Panama City FL, it’s helpful to have certain information ready. The more details you provide, the better we can tailor a policy that perfectly fits your needs:
- Business Legal Name and Structure: (e.g., LLC, S-Corp, Sole Proprietor)
- Federal Tax ID Number (EIN): Or Social Security Number if you’re a sole proprietor without an EIN.
- Details on Business Operations: A clear description of what your business does, including services provided, products sold, and operational procedures.
- Annual Revenue and Payroll Estimates: These figures are crucial for calculating liability and workers’ compensation premiums.
- List of Physical Assets and Their Value: This includes your building (if owned), inventory, equipment, furniture, and any other significant business property.
- Vehicle Information for Commercial Auto: Details on all vehicles used for business, including make, model, year, VIN, and primary drivers.
Having this information at hand allows us to quickly and accurately assess your risks and obtain competitive quotes from our network of top-rated carriers.
Frequently Asked Questions About Business Insurance in Panama City, FL
We often hear similar questions from business owners navigating commercial insurance. Here are some of the most common inquiries and our straightforward answers.
I’m a sole proprietor with no employees. Do I still need business insurance?
Yes, absolutely! This is a common misconception, but even if you’re a sole proprietor working alone without employees, you still need business insurance Panama City FL. Why?
- Liability Exposure: You still have liability exposure from interacting with clients, vendors, and the public. If a client slips and falls in your home office, or if your work causes damage to a client’s property, you could be held personally responsible. General Liability is crucial to protect your personal assets from business-related lawsuits.
- Property Protection: Your business property – tools, computer equipment, inventory – is generally not covered by your homeowners or renters insurance policy for business use. A commercial property policy or a Business Owner’s Policy (BOP) can protect these vital assets.
- Contractual Requirements: Many clients or landlords will require you to carry specific insurance coverage before they’ll work with you or rent space to you.
Don’t let the “no employees” factor lull you into a false sense of security. Your business, no matter how small, has risks that need professional protection.
What’s the minimum amount of coverage I can purchase?
The minimum amount of coverage you can purchase varies significantly by policy type, your business’s industry, and the specific insurer. For general liability, for instance, limits can start as low as $100,000 or $300,000 per occurrence. However, a $1,000,000 limit is often considered standard and is widely recommended for most businesses due to the high cost of lawsuits today.
The cost to increase your liability limits is often minimal for significantly more protection. For example, increasing your general liability limit from $300,000 to $1,000,000 might only add a small percentage to your overall premium, but it provides a much greater buffer against catastrophic claims. We always advise our clients to consider the potential worst-case scenarios and secure limits that truly protect their assets. An experienced agent can help you determine adequate limits for your specific risk profile and industry.
Where can I find resources for disaster preparedness?
For businesses in Panama City, proactive planning for disasters is not just a best practice; it’s a necessity. Being prepared can significantly reduce the impact of hurricanes and other emergencies on your operations. Authoritative sources provide excellent guidance and tools to help you develop a robust disaster preparedness plan.
The U.S. Small Business Administration (SBA) offers comprehensive checklists, guides, and plans specifically designed for businesses to prepare for various emergencies, including hurricanes. Their resources can help you create an emergency action plan, protect your employees, secure your property, and plan for business continuity. Taking the time to develop a solid preparedness strategy now can save your business immense time and money when disaster strikes.
Conclusion: Secure Your Panama City Business Today
Protecting your Panama City business is an investment in its future. The right insurance portfolio shields you from devastating financial loss due to accidents, lawsuits, cyber incidents, and natural disasters. From general liability to specialized coverage like cyber and professional liability, a custom plan is essential for success in Florida’s dynamic, hurricane-prone market.
Partnering with an experienced independent agency like Florida All Risk Insurance gives you access to multiple carriers, local insight, and guidance custom to your specific industry and risk profile. You stay focused on running your business while your coverage helps safeguard your assets, employees, and long-term plans.
Do not leave your hard work and financial future to chance. Take the first step toward comprehensive protection today.
Get a Free, No-Obligation Quote: Contact us online to review your current coverage, identify gaps, and see how affordable comprehensive protection can be.
Protect Your Business Before the Next Storm or Lawsuit Hits: Schedule a consultation today through our business insurance page and let a local expert help you build a coverage plan that fits your Panama City operations.
Contact Us
Florida All Risk Insurance
Email: [email protected]

