

Florida Uninsured Motorist Coverage: Your 1 Essential Guide
Why Florida Uninsured Motorist Coverage is Critical for Your Financial Safety
Florida uninsured motorist coverage is optional insurance that protects you when you’re hit by a driver who has no insurance or not enough insurance to cover your damages. Unlike Florida’s required Personal Injury Protection (PIP), which only covers $10,000 in medical expenses, UM coverage helps pay for medical bills, lost wages, pain and suffering, and other costs that PIP doesn’t cover—and you’ll need it because one in five Florida drivers has little to no insurance.
Quick Answer: What You Need to Know About Florida UM Coverage
- What it is: Insurance that pays when an uninsured driver causes your injuries
- What it covers: Medical expenses beyond PIP, lost wages, pain and suffering, permanent injuries
- Cost: Typically only $50-$75 per year for significant protection
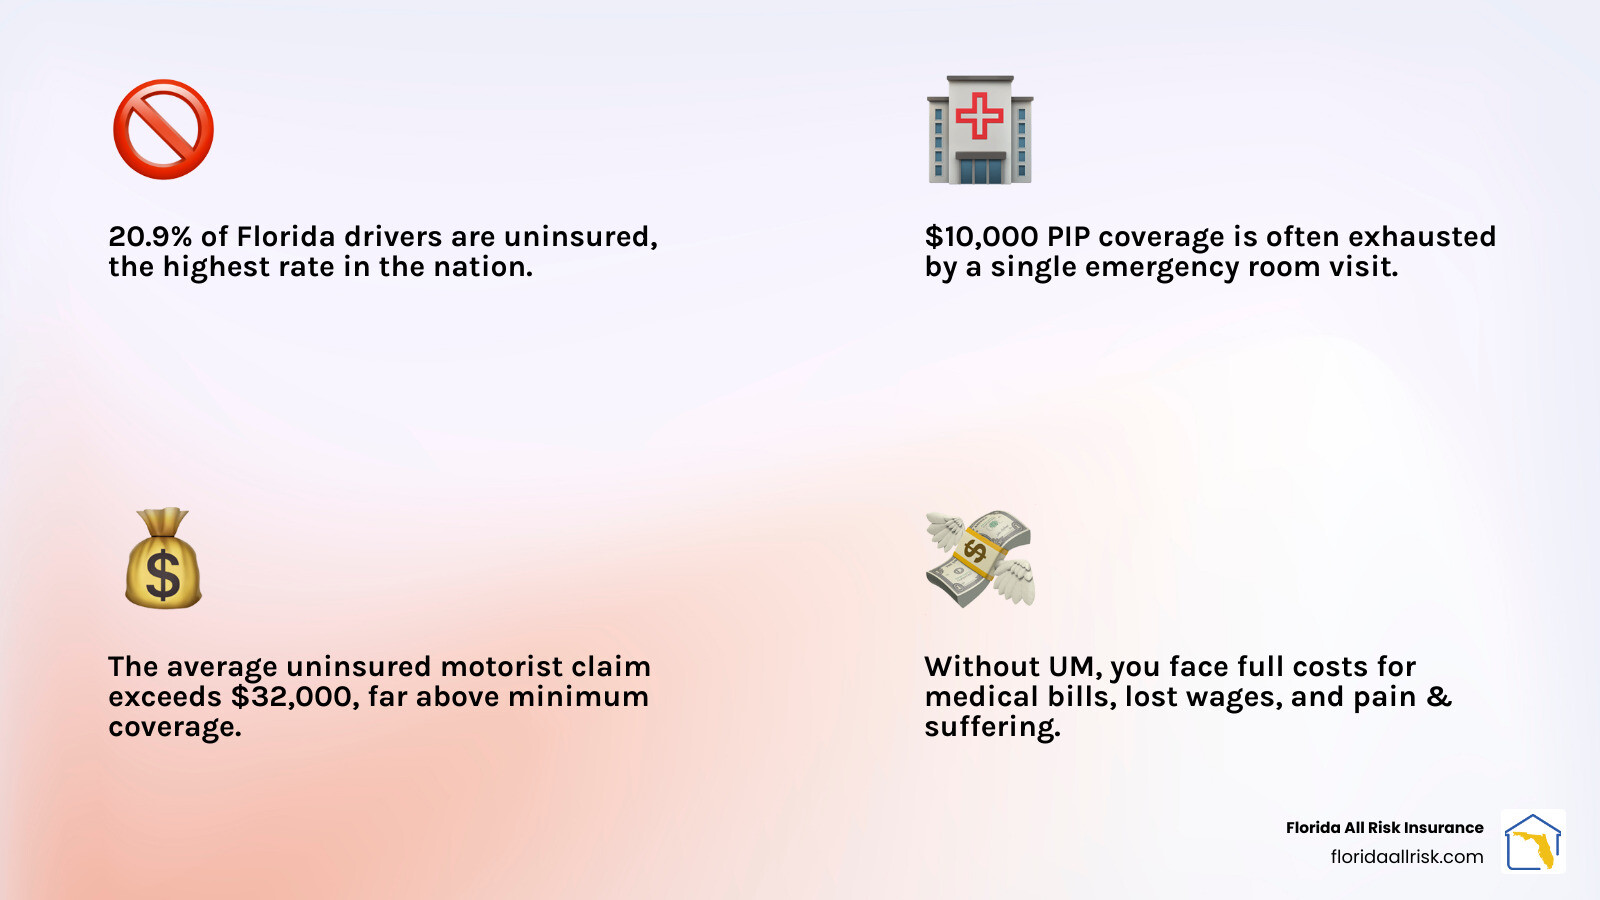
- Florida’s problem: 20.9% of drivers are uninsured (highest in the nation)
- Required?: No, but you must reject it in writing if you don’t want it
- Average claim: Over $32,000—far exceeding Florida’s $10,000 minimum coverage
- When it applies: Hit by uninsured driver, hit-and-run, or struck as a pedestrian
Here’s the reality: Florida only requires drivers to carry $10,000 in Personal Injury Protection and $10,000 in Property Damage Liability. There’s no requirement for Bodily Injury Liability coverage unless you’ve caused an accident or received certain citations. This means the driver who hits you might have zero coverage for your injuries beyond that initial $10,000 PIP limit.
With over 401,000 traffic crashes in Florida in 2021 alone—resulting in 3,735 deaths and 252,860 injuries—the chances of being involved in an accident are real. When that accident involves one of the estimated 20.9% of uninsured drivers on Florida roads, you could face tens of thousands of dollars in uncovered medical bills, lost income, and other damages.
As Jason Miller, I’ve spent over 20 years helping Florida families steer insurance protection, and I’ve seen how Florida uninsured motorist coverage has saved clients from financial devastation after accidents with uninsured drivers. This guide will walk you through everything you need to know to make an informed decision about protecting yourself and your family.
Florida uninsured motorist coverage vocab to learn:
What is Uninsured Motorist (UM) Coverage and Why is it Essential in Florida?
Uninsured motorist (UM) coverage is a crucial component of an auto insurance policy designed to protect you, the policyholder, when you are involved in an accident with someone who does not have insurance or sufficient insurance. Essentially, your own insurance company steps in to cover the damages that the at-fault driver’s non-existent or inadequate policy would have covered. This protection extends to you, your resident spouse, and resident family members, regardless of whether they are in your car, someone else’s car (with permission), or even if they are struck as a pedestrian.
Every state provides UM coverage, generally based on specific statutes. In Florida, this coverage is particularly essential because of our state’s unique insurance landscape. Florida has consistently ranked among the states with the highest number of uninsured drivers in the country. Recent estimates suggest that over 20.9% of drivers in Florida are on the road without proper insurance. To put that into perspective, that’s more than one in five drivers you might encounter every day.
The minimum insurance requirements in Florida are notably low. Our state’s No-Fault Law mandates that drivers carry only:
- $10,000 in Personal Injury Protection (PIP)
- $10,000 in Property Damage Liability (PDL)
You can find more details on these requirements at the official Florida Insurance Requirements page.
What’s missing from this mandatory list? Bodily Injury Liability (BIL) coverage. Florida does not require drivers to carry BIL coverage unless they’ve previously caused an accident involving injury or death, or received certain citations. This creates a significant “coverage gap.” If an uninsured driver (or one with only the minimum PIP/PDL) causes an accident that results in serious injuries to you, their minimal insurance will quickly be exhausted. For instance, even a single emergency room visit can easily deplete the $10,000 PIP benefit.
Consider these startling statistics:
- Florida has the highest number of uninsured motorists in the country.
- One in five drivers in Florida are on the road with little to no insurance at all.
- In 2019, the estimate for Florida was 20.9% uninsured.
- The average UM bodily injury claim was over $32,000 in recent years.
When you compare the state’s minimum $10,000 PIP coverage to an average UM bodily injury claim of over $32,000, the potential for financial devastation without adequate protection becomes alarmingly clear. This is precisely why Florida uninsured motorist coverage isn’t just an option; for many, it’s a necessity to safeguard their financial future on our busy roads. We at Florida All Risk Insurance understand these risks and want to ensure our clients in St. Petersburg and across Florida are well-prepared.
A Deep Dive into Your Florida Uninsured Motorist Coverage Options
Navigating the nuances of auto insurance can feel like deciphering a secret code, but understanding your options for Florida uninsured motorist coverage is crucial. Let’s break down the different types and how they can offer you maximum protection.
Uninsured (UM) vs. Underinsured (UIM) Motorist Coverage
While often discussed together, it’s important to differentiate between uninsured and underinsured motorist coverage, as they address slightly different scenarios:
-
Uninsured Motorist (UM) Coverage: This is designed to protect you when the at-fault driver has no auto insurance whatsoever. It also applies in situations where the at-fault driver cannot be identified, such as in hit-and-run accidents or incidents involving “phantom vehicles” (where a vehicle causes an accident but doesn’t make contact and flees the scene). In these cases, your UM coverage acts as a substitute for the missing liability insurance of the at-fault party, covering your medical expenses, lost wages, and other damages. For a general understanding, Investopedia provides a helpful overview of Uninsured motorist (UM) coverage.
-
Underinsured Motorist (UIM) Coverage: This comes into play when the at-fault driver does have liability insurance, but their policy limits are insufficient to cover the full extent of your damages. For example, if your medical bills and lost wages total $50,000, but the at-fault driver only carries the Florida minimum of $10,000 in bodily injury liability (if they have it at all), UIM coverage steps in to cover the remaining $40,000 (up to your policy limits). This effectively bridges the gap between what the at-fault driver’s insurance pays and your total damages. You can learn more about Underinsured motorist (UIM) coverage on Investopedia.
In Florida, UM and UIM coverage are typically offered together as a single coverage, often referred to simply as UM coverage, that protects you against both uninsured and underinsured drivers.
Stacked vs. Unstacked: Maximizing Your Protection
When purchasing Florida uninsured motorist coverage, you’ll likely be asked to choose between “stacked” and “unstacked” options. This choice significantly impacts the amount of coverage available to you in an accident.
-
Unstacked Coverage: With unstacked UM coverage, the limits of your policy apply to a single vehicle, regardless of how many vehicles you own or insure. If you have $100,000 in unstacked UM coverage, that’s the maximum you can collect per accident, even if you own multiple vehicles. This option is typically less expensive and is often chosen by individuals who own only one vehicle or who prefer lower premiums.
-
Stacked Coverage: Stacked UM coverage allows you to combine the UM/UIM coverage limits from multiple vehicles on a single policy, or even from multiple policies if you have them. For example, if you have two cars, each insured with $100,000 in stacked UM coverage, and you’re involved in an accident, your total available UM coverage would be $200,000. If you have three cars, it would stack to $300,000. This provides a much higher level of protection, which can be invaluable given the high costs of medical care and lost wages after a serious accident. While it comes with a slightly higher premium, the increased protection often outweighs the additional cost, especially for families with multiple vehicles. Learn more about Stacked auto insurance.
Florida law actually requires UM coverage to be “stacked” by default unless you explicitly reject it in writing. We generally recommend stacked coverage to our clients in St. Petersburg and across Florida because it offers superior protection. The cost difference is often surprisingly small, sometimes less than what you might spend on a daily cup of coffee!
Here’s a quick comparison:
| Feature | Unstacked UM Coverage | Stacked UM Coverage |
|---|---|---|
| Key Feature | Fixed limit per policy/vehicle | Combines limits from multiple vehicles/policies |
| Cost | Generally lower premium | Slightly higher premium |
| Coverage Limit Example | 1 car @ $100k UM = $100k max coverage | 2 cars @ $100k UM each = $200k max coverage; 3 cars @ $100k UM each = $300k max coverage |
| Best For | Single vehicle owners, those seeking lowest premiums | Multiple vehicle owners, families, those seeking maximum protection |
What Damages Can Florida Uninsured Motorist Coverage Pay For?
One of the greatest benefits of Florida uninsured motorist coverage is its comprehensive nature in covering a wide range of damages that often exceed the limits of other insurance types. When an uninsured or underinsured driver causes an accident, your UM policy can help cover:
- Medical Bills Beyond PIP: While PIP covers the first $10,000 in medical expenses (under specific conditions), serious injuries can quickly lead to bills far exceeding this. UM coverage can pay for these additional medical costs, including hospital stays, doctor visits, surgeries, and rehabilitation.
- Lost Wages and Earning Capacity: If your injuries prevent you from working, UM coverage can compensate you for lost income, both immediately after the accident and for any future diminished earning capacity due due to permanent injuries.
- Pain and Suffering: Unlike PIP, UM coverage can provide compensation for the non-economic damages you experience, such as physical pain, emotional distress, and mental anguish resulting from the accident.
- Permanent Impairment or Disfigurement: If your injuries lead to a permanent disability, scarring, or disfigurement, UM coverage can provide financial relief for these long-term impacts.
- Future Medical Care: For injuries requiring ongoing treatment, therapy, or future surgeries, UM coverage can help ensure you receive the necessary care without incurring massive out-of-pocket expenses.
- Funeral Expenses: In the tragic event of a fatality caused by an uninsured or underinsured driver, UM coverage can help cover funeral and burial costs.
UM coverage typically focuses on bodily injury. For damage to your vehicle, you would generally rely on your collision coverage or a specific Uninsured Motorist Property Damage (UMPD) coverage, if available and purchased.
The Legal & Practical Guide to UM Coverage in Florida
Understanding the legal landscape and practical implications of Florida uninsured motorist coverage is key to making an informed decision about your policy.
The Pros, Cons, and Cost of UM Coverage
Let’s weigh the benefits against the considerations for purchasing UM coverage in Florida:
Pros:
- Financial Safety Net: This is the primary advantage. It acts as a critical buffer, protecting you from potentially ruinous out-of-pocket expenses for medical bills and lost income when an at-fault driver has no or insufficient insurance.
- Peace of Mind: Knowing you’re protected against the significant risk posed by uninsured drivers allows you to drive with greater confidence.
- Covers Hit-and-Runs: If you’re involved in a hit-and-run accident and the at-fault driver cannot be identified, your UM coverage can step in to cover your injuries.
- Protects You as a Pedestrian or Cyclist: UM coverage isn’t just for when you’re in your car. If you or a covered family member are struck by an uninsured driver while walking or biking, your UM policy can still provide protection.
Cons & Cost:
- Additional Premium: The main “con” is that purchasing UM coverage adds to your overall insurance premium. However, when you consider the potential financial exposure without it, this additional cost is often minimal.
- Relatively Low Cost for High Value: Despite being an additional cost, UM coverage is often described as one of the most cost-effective additions to your policy. The average cost for UM coverage can be as low as an extra $50-$75 annually. When you compare this to the average UM bodily injury claim of over $32,000, it’s a small price to pay for such significant protection.
We consistently advise our clients that the value of Florida uninsured motorist coverage far outweighs its cost, especially given the prevalence of uninsured drivers in our state.
Rejecting Coverage: The Risks and Legal Requirements
While Florida uninsured motorist coverage is incredibly valuable, it is not mandatory. Drivers have the option to reject it, but this decision comes with significant risks and specific legal requirements.
Consequences of Rejection:
- Personal Liability for All Costs: If you reject UM coverage and are seriously injured by an uninsured driver, you could be personally responsible for all medical bills, lost wages, and other damages that exceed your PIP benefits.
- Relying on Health Insurance: While your health insurance might cover some medical costs, it typically won’t cover lost wages, pain and suffering, or other non-economic damages. You’ll also likely face deductibles and co-pays.
- No Compensation for Pain and Suffering: Without UM coverage, if the at-fault driver is uninsured, you have no recourse to recover compensation for your pain, suffering, and emotional distress, which can be substantial after a serious accident.
- Potential for Financial Ruin: A severe accident with an uninsured driver could lead to tens or even hundreds of thousands of dollars in expenses, potentially leading to bankruptcy without UM coverage.
Legal Process for Rejection:
- Insurers Must Offer It: In Florida, insurance companies are legally required to offer UM coverage with limits equal to your Bodily Injury Liability (BIL) coverage (if you purchase it), or lower limits if you select them.
- Written Rejection on a Specific, State-Approved Form: If you choose to reject UM coverage or select lower limits, you must do so in writing on a form approved by the state. This form is designed to clearly advise you of the nature of the coverage and the implications of your decision. Signing this form is conclusively presumed to be an informed, knowing rejection. This legal requirement is outlined in F.S. 627.727.
We strongly advise against rejecting UM coverage. The potential savings on your premium are usually minimal compared to the massive financial risk you undertake by foregoing this vital protection.
When Does UM Apply and How Does it Interact with PIP?
Understanding when your Florida uninsured motorist coverage kicks in and how it works alongside your Personal Injury Protection (PIP) is crucial for navigating a claim.
UM coverage typically applies in a variety of scenarios:
- Car accident with an uninsured driver: This is the most straightforward application. If an at-fault driver has no insurance, your UM coverage steps in.
- Hit-and-run accident: If you’re involved in an accident and the at-fault driver flees the scene and cannot be identified, your UM coverage can provide recourse for your injuries.
- Struck as a pedestrian or cyclist by an uninsured driver: Your UM coverage extends beyond just when you’re in your car, protecting you and resident family members if hit by an uninsured vehicle while walking or biking.
- Passenger in another person’s car hit by an uninsured driver: If you’re a passenger and the driver of the vehicle you’re in is hit by an uninsured motorist, your own UM coverage can protect you, even if you’re not in your insured vehicle.
Interaction with PIP:
In Florida, our no-fault system means that Personal Injury Protection (PIP) is generally your primary source of medical coverage after an accident, regardless of who was at fault.
- PIP is primary coverage: Your PIP policy will cover 80% of your initial medical expenses up to $10,000 (with specific conditions for emergency vs. non-emergency medical conditions) and 60% of lost wages.
- UM is excess coverage: Florida uninsured motorist coverage acts as excess coverage. This means it typically comes into play after your PIP benefits have been exhausted. Once your PIP limits are reached, your UM coverage can then cover additional medical expenses, lost wages, and pain and suffering, up to your policy limits. This interaction is vital because PIP’s $10,000 limit is often quickly depleted by even moderate injuries.
Frequently Asked Questions (FAQ) About Florida UM Coverage
Navigating insurance can bring up many questions. Here are answers to some common ones about UM coverage.
1. If I have good health insurance, do I still need UM coverage?
Yes. Health insurance is crucial, but it won’t cover everything. You’ll still face deductibles and co-pays. Most importantly, health insurance provides zero compensation for lost wages, future lost earning capacity, or the pain and suffering caused by the accident. UM coverage is designed to cover these exact economic and non-economic damages that health insurance and PIP won’t touch.
2. Will filing a UM claim make my insurance rates go up?
Florida law offers protection here. An insurer cannot raise your rates or refuse to renew your policy solely because you filed a not-at-fault claim, which includes UM claims (Florida Statute 626.9541). While rates can change for other reasons (like a general rate increase in your area), you won’t be penalized simply for using the UM benefits you paid for when an uninsured driver was at fault.
3. What if my own insurance company gives me a low settlement offer for my UM claim?
When you file a UM claim, your insurer’s role shifts. They now represent the at-fault driver’s interests, which means their goal is to minimize the payout. You must prove the other driver’s fault and the full value of your damages. If they make an unreasonable offer, it’s a first-party dispute. You have the right to negotiate and, if necessary, take legal action to enforce your policy contract and get the fair compensation you deserve.
4. Does UM coverage apply if I’m in an accident outside of Florida?
Yes, in most cases. Your auto policy, including UM, typically provides coverage throughout the United States and Canada. If you’re on vacation in another state and are hit by a local uninsured driver, your Florida UM coverage should apply. It protects you and resident family members not just in your car, but as passengers or pedestrians, offering a wide blanket of security wherever you travel within the policy territory.
Steps to Take After an Accident with an Uninsured Driver
Being involved in any car accident is stressful, but finding the other driver is uninsured adds another layer of complexity. Knowing what to do can significantly impact your ability to recover damages.
At the Scene: Protect Your Health and Your Claim
Your actions immediately after an accident are crucial for both your well-being and the success of any potential claim.
- Call 911: Report the accident to the police immediately, even if it seems minor. A police report is vital documentation, especially when dealing with an uninsured driver.
- Seek Immediate Medical Attention: Your health is paramount. Even if you don’t feel injured, adrenaline can mask pain. Get checked by paramedics at the scene or go to an urgent care facility or emergency room promptly. This also creates an official record of your injuries. For PIP benefits, initial treatment must be received within 14 days of the accident.
- Do Not Admit Fault: Never admit fault or make statements that could be interpreted as admitting fault, even if you think you might be partially to blame. Stick to the facts.
- Gather Driver and Witness Information:
- Get the uninsured driver’s name, address, phone number, and vehicle information (make, model, license plate number).
- Ask if they have any insurance, and if so, get that information too (though they likely won’t have the necessary liability coverage).
- Collect contact information from any witnesses.
- Take Photos and Videos: Use your phone to document everything:
- Damage to all vehicles involved from multiple angles.
- The accident scene, including road conditions, traffic signs, and any skid marks.
- Your injuries.
- The other driver’s license plate and any visible identifying features of their vehicle.
Filing Your Florida Uninsured Motorist Coverage Claim
Once you’ve ensured your immediate safety and gathered initial information, the next steps involve working with your own insurance company.
- Notify Your Insurance Company Immediately: Report the accident to your own insurance company as soon as possible. Delaying notification could complicate your claim. Tell them you believe the other driver is uninsured.
- Provide All Documentation: Share everything you’ve collected: the police report number, photos, videos, witness contacts, and any medical records from your initial treatment.
- Understand the Claims Process: Your insurance company will investigate the accident, just as they would if the other driver was insured. They will confirm the other driver’s uninsured status.
- Proving the Other Driver’s Fault: Even though your own insurance is paying, you still need to prove that the uninsured driver was at fault for the accident. The evidence you collected at the scene (police report, photos, witness statements) will be critical here.
- Documenting Your Damages and Injuries: Keep meticulous records of all medical appointments, treatments, prescriptions, and any out-of-pocket expenses related to your injuries. Track all lost wages. This documentation is essential for substantiating your claim for medical bills, lost wages, and pain and suffering under your Florida uninsured motorist coverage.
- Cooperating with Your Adjuster: Work openly with your insurance adjuster, providing them with requested information promptly. However, remember you don’t have to give a recorded statement without consulting legal counsel if you feel uncomfortable.
Filing a UM claim can be complex, especially when dealing with injuries and potentially significant damages. We are here to guide you through this process and help ensure you receive the full benefits you’re entitled to under your policy.
Secure Your Financial Future on Florida’s Roads
We’ve covered a lot about Florida uninsured motorist coverage, and we hope it’s clear why we consider it an indispensable part of your auto insurance policy. With Florida having the highest number of uninsured motorists in the country, and minimum liability requirements that often fall far short of covering serious accident costs, UM coverage is not just a luxury; it’s a necessity for your financial well-being.
The risk of encountering an uninsured or underinsured driver on Florida roads is simply too high to ignore. While adding UM coverage does mean a slightly higher premium, it’s a small price to pay for the significant protection it offers against potentially devastating medical bills, lost income, and the pain and suffering that can result from an accident. We believe in making informed decisions, and we’re here to help you understand all your options.
At Florida All Risk Insurance, based right here in St. Petersburg, Florida, we pride ourselves on being an independent agency. This means we work for you, not for a single insurance company. We have access to a wide range of carriers, allowing us to tailor coverage and find competitive rates that best suit your unique needs. Our personalized advice ensures that our clients in St. Petersburg and across Florida are fully protected, even from the unexpected.
Don’t gamble with your financial security. Get a personalized car insurance quote today to see how affordable peace of mind can be.
Have questions about your current policy? Our expert team is ready to review your coverage and ensure you’re fully protected from uninsured drivers. We’re always happy to help.
Contact Us
Address: 7751 4th St N, St. Petersburg, FL 33702
Phone: (727) 522-7777
Email: [email protected]

