

Dog liability insurance quotes: Smart 2026 Savings
Why Dog Liability Insurance Quotes Matter More Than Ever
Dog liability insurance quotes are your first step toward protecting yourself from the potentially devastating financial consequences of a dog-related incident. In an instant, a seemingly minor accident can spiral into a legal and financial nightmare involving staggering medical bills, costly legal fees, and lawsuit settlements that can reach tens or even hundreds of thousands of dollars. The statistics are sobering: in 2023, the Insurance Information Institute reported over 19,000 dog bite claims nationwide, costing more than $1.12 billion. Even more alarming is the 82.5% increase in the average cost per claim over the last decade. A single incident can be financially ruinous if you’re not properly insured.
For Florida residents, the risk is amplified by the state’s “strict liability” statute. This means that as a dog owner, you are liable for any injuries your dog causes, regardless of whether you knew the dog was dangerous or had a history of aggression. This legal standard makes comprehensive liability coverage not just a good idea, but an absolute necessity for financial survival.
Quick Answer: How to Get Dog Liability Insurance Quotes
- Review your current homeowners or renters insurance: Scrutinize your policy for specific language on animal liability, paying close attention to coverage limits and potential exclusions.
- Identify any coverage gaps: Look for breed blacklists, bite history restrictions, or dangerously low sub-limits that could leave you exposed.
- Gather your dog’s information: Compile essential details like breed, age, weight, bite history, training certifications, and your property address.
- Compare standalone policies: These specialized policies, with costs ranging from $10-$100+ per month, are often the best solution for restricted breeds or those with a past incident.
- Consider an umbrella policy: This can provide an extra layer of liability protection, but you must verify it doesn’t also exclude dog-related incidents.
- Work with an independent agent: An expert agent can access multiple carriers, including specialty providers, to find the best coverage for your unique situation.
Many Florida dog owners face a significant challenge: standard homeowners policies are increasingly limiting or excluding coverage for certain breeds or dogs with bite histories. You might discover your policy has a low sub-limit (e.g., $25,000) for dog incidents or that your beloved pet’s breed is on an exclusion list you never knew existed. This discovery often comes after an incident occurs—the worst possible time.
At Florida All Risk Insurance, we have over 20 years of experience helping Florida residents navigate complex insurance needs. We’ve helped countless dog owners secure affordable dog liability insurance quotes that provide real protection—even for breeds other companies won’t touch. Our goal is to help you find coverage that lets you enjoy your four-legged family member without financial worry.
Understanding Dog Liability Insurance: Your Financial Shield
Dog liability insurance is a specific type of coverage designed to protect you financially if your dog causes bodily injury to another person or damages their property. It is crucial to distinguish this from pet health insurance, which covers your dog’s veterinary bills for illness or injury. Think of dog liability coverage as General Liability Insurance for your canine companion; it shields your personal assets from third-party claims stemming from your dog’s actions.
Why Every Dog Owner Should Consider It
As dog owners, we see our pets as beloved family members. However, even the most well-behaved, gentle dog can have an accident. A playful nip during a game of fetch, an unintentional scratch from an excited jump, or a dog simply getting underfoot and causing someone to fall can lead to serious injuries and devastating financial consequences. The statistics from the Dog bite liability statistics from the III paint a clear picture: dog-related claims are frequent and increasingly expensive. In Florida, responsible pet ownership extends beyond providing food and love; it includes protecting yourself and your community from unforeseen incidents. Without adequate dog liability insurance, you could be held personally liable for thousands, or even hundreds of thousands, of dollars in medical bills, lost wages, property damage, and legal fees. The modest cost of a policy is a small price to pay for the immense peace of mind and financial protection it provides.
What’s Covered? Beyond Just the Bite
Dog liability insurance is comprehensive, covering a wide range of incidents beyond just bites. It is designed to protect you from financial loss resulting from third-party bodily injury and property damage your dog might cause to someone outside your immediate household.
Typical coverage includes:
- Medical Expenses: This covers the medical bills for a person injured by your dog. This can include everything from emergency room visits and stitches to surgery, physical therapy, and psychological counseling.
- Legal Defense Costs: This is a critical component. The policy pays for your legal fees if you are sued, including attorney costs, court filing fees, and expert witness expenses, regardless of whether you are ultimately found at fault.
- Lawsuit Settlements and Judgments: If a court orders you to pay damages or you agree to a settlement, this coverage pays out up to your policy limit, protecting your personal assets like your home, savings, and future earnings.
- Property Damage: This pays for the repair or replacement of property your dog damages. Examples include a neighbor’s destroyed garden, a chewed-up antique rug in a friend’s home, or a broken fence.
- Incidents Off-Property: Many policies provide coverage for incidents that happen away from your home, such as at a dog park, on a walk in your neighborhood, or while visiting another person’s property.
- Other Injuries: Coverage isn’t limited to bites. It can extend to scratches that become infected or, more commonly, injuries from a fall caused by your dog jumping on someone or running in front of them.
Essentially, this insurance protects your financial well-being from the consequences of damage or injuries caused by your pet to a third party. To understand the general scope of such protections, you can explore What Does General Liability Insurance Cover.
What’s Typically Not Covered
It’s also crucial to understand the limitations of a dog liability policy. This coverage is for third-party incidents only and does not cover damages to your own family or property.
- Damage to Your Own Property: If your dog chews your furniture, digs up your yard, or otherwise damages your home or belongings, this is not covered.
- Injuries to You or Household Members: Medical expenses for you, your spouse, your children, or anyone else living in your home are not covered by the liability policy. These would fall under your personal health insurance.
- Business-Related Incidents: If your dog is part of a business (e.g., a therapy dog used in a practice, a guard dog, or a dog at a grooming salon), you need specialized Business Liability Insurance.
- Intentional or Malicious Acts: Harm caused by a dog that was intentionally provoked or trained to be aggressive is generally excluded. Insurers expect you to be a responsible owner.
- Contractual Liability: If you sign a contract assuming liability beyond what is legally required of you, that assumed liability may not be covered.
- Punitive Damages: In some cases, punitive damages, which are intended to punish the defendant rather than compensate the victim, may be excluded from coverage.
Homeowners Insurance and Your Dog: Are You Really Covered?
Many dog owners mistakenly assume their homeowners or renters insurance provides sufficient coverage for any dog-related incident. While a standard Homeowners Insurance Florida policy does include a personal liability protection component, there are often significant limitations, sub-limits, and outright exclusions that can leave you dangerously exposed financially.
We often hear from clients in Saint Petersburg and across Florida who are shocked to learn their policy isn’t as comprehensive as they believed. The personal liability portion of a typical homeowners policy is designed to cover accidental bodily injury and property damage caused by members of your household—including your pets—to others. However, for dog owners, the devil is in the details, and these details can have six-figure consequences.
The “Dangerous” Breed Blacklist
A major challenge for Florida dog owners is the prevalence of breed restrictions. Many insurance companies maintain a “blacklist” of breeds they consider “high-risk” based on internal data and industry trends. Owning a dog on this list can lead to an outright denial of coverage, significantly higher premiums, or, most deceptively, an endorsement that excludes your dog from any and all liability protection.
Commonly blacklisted breeds include:
- Pit Bulls & Staffordshire Terriers
- Doberman Pinschers
- Rottweilers
- Chow Chows
- Great Danes
- Presa Canarios
- Akitas
- Alaskan Malamutes
- German Shepherds
- Siberian Huskies
- Wolf-hybrids
- Cane Corsos
- Mastiffs
If you own one of these breeds, your insurer might cancel your policy upon discovery or non-renew it at the end of the term. At Florida All Risk Insurance, we believe a dog’s breed alone does not determine its behavior; responsible ownership is the key factor. Navigating the insurance market with a restricted breed requires a proactive approach, as detailed in our guide Paws Policies: Navigating Homeowners Insurance with Dogs.
Coverage Sub-Limits and Exclusions
Even if your dog’s breed isn’t on a blacklist, your policy might contain other traps. Many policies impose a specific, lower limit for dog-related claims, known as a sub-limit. For example, your policy might have a general personal liability limit of $300,000, but a sub-limit of only $25,000 for any claims arising from an animal incident. If a dog bite claim results in a $100,000 settlement, your insurance would only pay $25,000, leaving you personally responsible for the remaining $75,000.
Worse yet, some policies may exclude dog bites entirely or all forms of animal liability. A prior bite history, even a minor one that didn’t break the skin, can also lead to a denial of coverage or non-renewal.
The Critical Importance of Disclosure
It is absolutely crucial to inform your homeowners insurance company that you have a dog, including its breed. Failing to disclose this information is considered “material misrepresentation.” If you file a claim and the insurer discovers you have an undisclosed dog (especially a restricted breed), they have the right to deny the claim and even void your entire policy from its inception. This would leave you completely uninsured for the incident and could force you to scramble for new coverage. It is always better to address these issues upfront than to face catastrophic out-of-pocket expenses and a policy cancellation later.
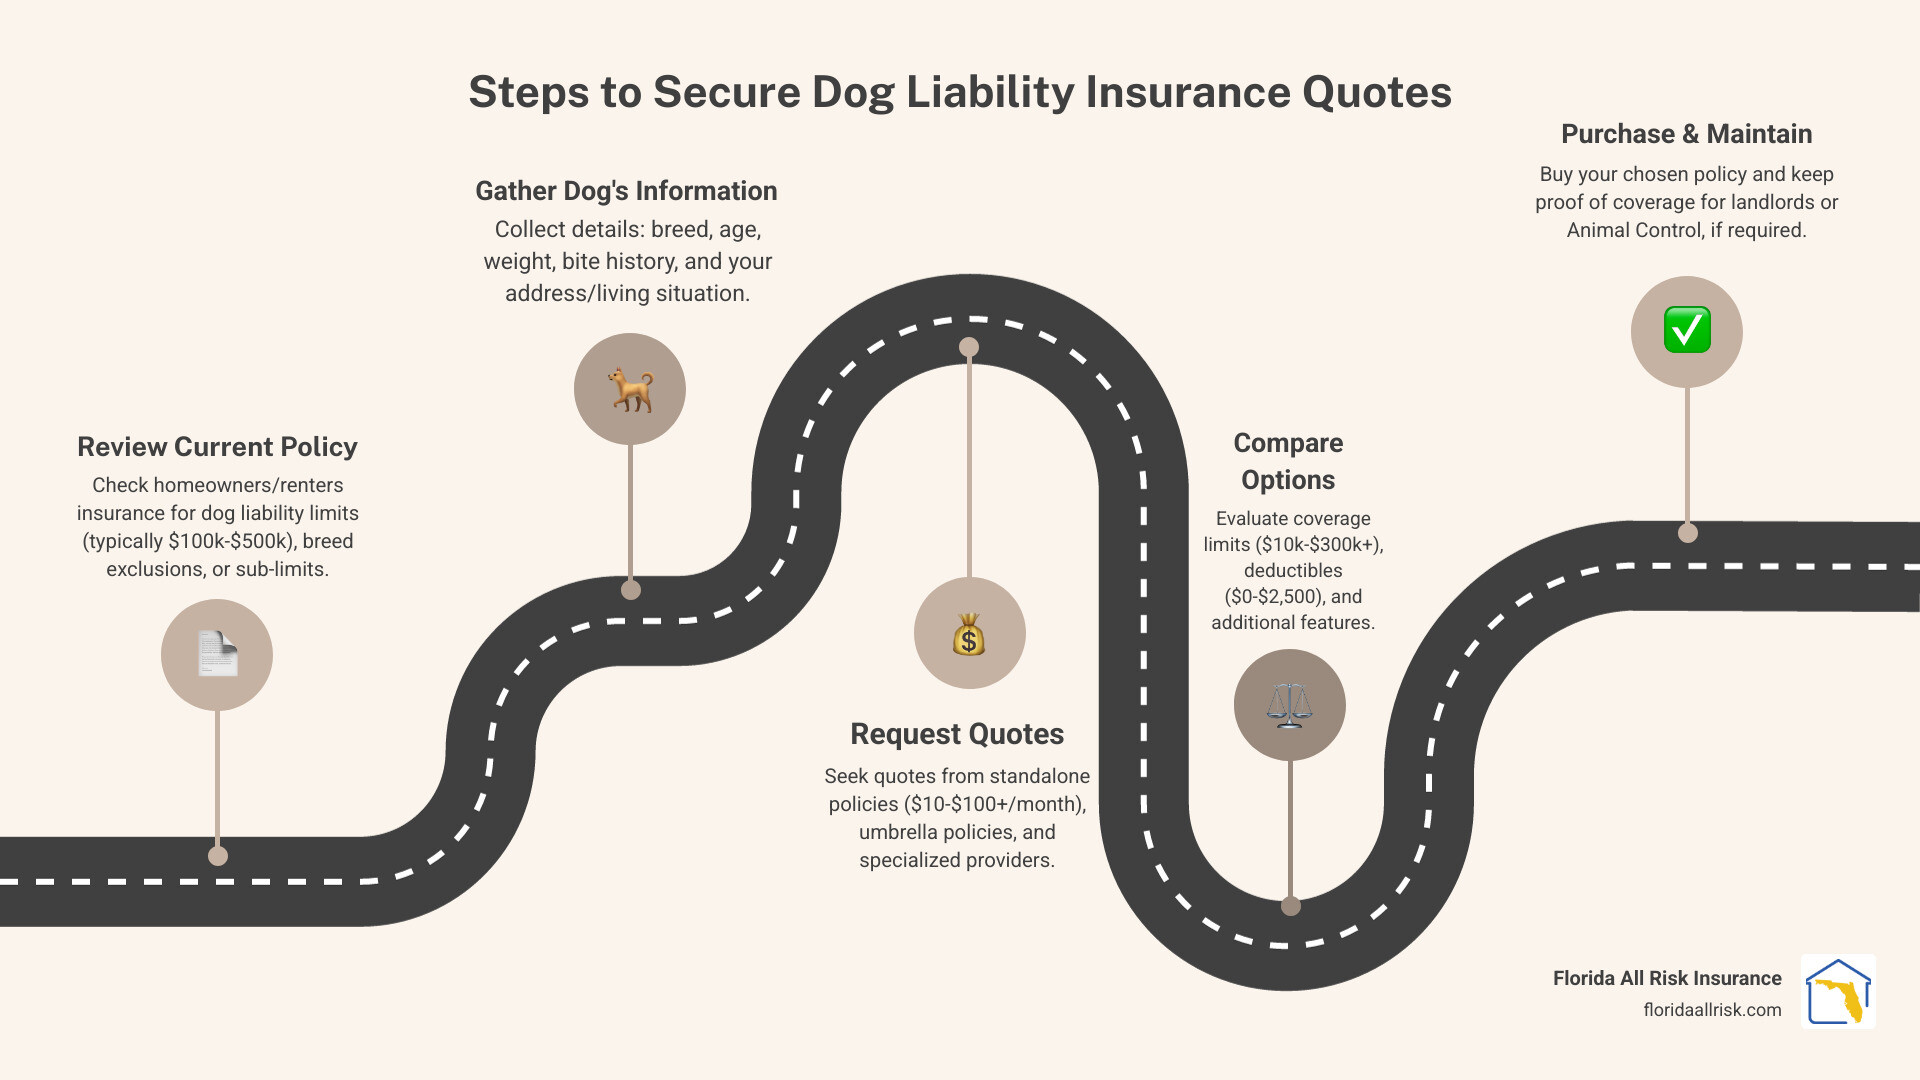
How to Get Dog Liability Insurance Quotes: A Step-by-Step Guide
Finding the right dog liability coverage at an affordable price requires a clear, methodical process. Rushing into a policy without due diligence can lead to inadequate protection or overpaying for coverage you don’t need. Following these steps will help you efficiently navigate the market and secure a policy that meets your specific needs and budget.
Step 1: Assess Your Current Coverage and Needs
Before seeking new dog liability insurance quotes, you must perform a thorough audit of your existing policies.
- Review Your Homeowners/Renters Policy: Don’t just skim it. Locate the personal liability section and your policy’s declaration page. Search the document for keywords like “animal,” “dog,” “bite,” “exclusion,” and “sub-limit.” Note the exact language used.
- Identify Liability Limits: A typical policy might offer $100,000 to $500,000 in personal liability. Given that the average dog bite claim is over $58,000 and severe claims can easily top six figures, aiming for at least $300,000 in liability coverage is a wise target for most dog owners.
- Check for Exclusions: Does your policy specifically exclude your dog’s breed? Is there a blanket exclusion for all animal liability or just for bites? Is there an exclusion for dogs with any prior history of aggression?
- Determine Required Coverage: Your need for insurance may be mandated by a third party. Many landlords now require tenants to carry a specific amount of dog liability insurance (e.g., $100,000) and to list the landlord as an “additional insured.” Similarly, a court or Animal Control might mandate coverage after an incident, often with high limit requirements.
Step 2: Gather Your Dog’s Information
Having a complete file on your dog will streamline the quote process and demonstrate that you are a responsible owner. Insurers appreciate thoroughness.
- Dog’s Breed(s): Be precise. If you have a mixed breed, provide as much information as you know. A DNA test can be helpful.
- Age and Weight: These are standard factors in risk assessment.
- Bite or Aggression History: You must disclose all incidents, no matter how minor. Honesty is critical to obtaining a valid policy.
- Training Certifications: Proof of completing obedience training or earning a Canine Good Citizen (CGC) certificate can significantly help your case and may lead to discounts.
- Spay/Neuter Status: Spayed or neutered dogs are often seen as lower risk by insurers.
- Your Address and Living Situation: Your location (ZIP code) and whether you own or rent are important rating factors.
- Containment Measures: Have photos of your securely fenced yard, including the height of the fence and proof of locking gates.
Step 3: Compare Your Options
With your information in hand, it’s time to explore the market. There are three primary avenues for securing dog liability coverage.
- Standalone Canine Liability Policies: These are policies designed specifically for dog-related liability, purchased separately from your homeowners insurance. They are often the best—and sometimes only—solution for owners of restricted breeds, dogs with a bite history, or renters whose landlord requires coverage.
- Umbrella Insurance Policies: An umbrella policy provides an extra layer of liability coverage (typically $1 million or more) on top of your existing homeowners and auto policies. However, you must confirm that the umbrella policy itself doesn’t have a dog-related exclusion, as many do.
- Working with an Independent Insurance Agent: This is our strongest recommendation. Unlike a captive agent who works for a single company, an independent agent works for you. We at Florida All Risk Insurance can compare dog liability insurance quotes from a wide range of providers, including specialty carriers that don’t sell directly to the public, to find the best fit for your needs and budget.
Step 4: Evaluate the Quotes and the Insurer
When reviewing quotes, look beyond the price. Compare the deductible (your out-of-pocket cost per claim) and the coverage limits. A higher deductible usually means a lower premium, but make sure it’s an amount you can comfortably afford. Furthermore, investigate the insurer’s reputation for claims handling and their financial stability rating (e.g., from AM Best). A cheap policy is worthless if the company can’t or won’t pay a claim.
Ready to explore your options? You can start the process by visiting our Get a Quote page.
Decoding the Cost of Canine Liability Coverage
The price of a dog liability policy can vary significantly, from as little as $10 a month for a basic policy on a low-risk dog to over $1,000 a year for a high-risk scenario. Insurers are in the business of risk assessment, and they calculate premiums based on a variety of factors. Understanding what drives the cost will help you interpret the dog liability insurance quotes you receive and identify opportunities to save.
Key Factors That Influence Your Dog Liability Insurance Quotes
When you request quotes, insurers feed several variables into their underwriting algorithm to assess the level of risk and determine your premium:
- Dog’s Breed: While controversial, certain breeds are statistically linked to more frequent or severe claims in actuarial data, leading to higher premiums from most carriers.
- Bite History: This is the single most significant factor. A dog with a prior bite incident, especially one that broke skin or required medical attention, will always command a higher premium. The severity and circumstances of the bite are key.
- Dog’s Weight and Size: Larger, stronger dogs are often perceived as a higher risk for causing significant injury, which can influence the rate.
- Your Location: Rates vary by state and even by ZIP code. This is based on local and state laws (e.g., strict liability vs. one-bite rule), claim frequency in your area, and even population density.
- Desired Coverage Limit: The higher the shield, the higher the cost. A policy with a $300,000 limit will cost more than one with a $100,000 limit.
- Deductible Amount: The deductible is the amount you pay out-of-pocket before the insurance kicks in. Choosing a higher deductible (e.g., $1,000 vs. $250) demonstrates you are sharing more risk and typically lowers your premium.
Understanding these factors is key to navigating the costs associated with Liability Insurance Cost for your dog.
How to Potentially Lower Your Premiums
While some factors like breed are fixed, you can take several proactive steps to potentially lower your insurance costs:
- Obedience Training: Completing a certified obedience course or earning an AKC Canine Good Citizen (CGC) title is a powerful signal to insurers that you are a responsible owner.
- Spaying/Neutering: Many studies suggest that spayed or neutered dogs may be less prone to aggression, and many insurers offer a small discount.
- Secure Containment: A securely fenced yard with locking gates can sometimes result in a better rate.
- Increase Your Deductible: As mentioned, a higher deductible can lead to a lower monthly or annual premium.
Average Costs and Coverage Tiers
While exact figures require a specific quote tailored to your situation, this table provides a general idea of what to expect for dog liability insurance quotes.
| Scenario | Typical Monthly Cost | Typical Annual Cost | Coverage Limits (Example) | Deductible (Example) |
|---|---|---|---|---|
| Low-Risk Dog (e.g., small breed, no bite history) | $10 – $30 | $120 – $360 | $100,000 | $250 – $500 |
| High-Risk Breed (no bite history) | $40 – $80 | $480 – $960 | $100,000 – $300,000 | $500 – $1,000 |
| Dog with Prior Bite Incident | $75+ | $900+ | $100,000 – $300,000 | $1,000 – $2,500 |
| Improved Coverage (higher limits, lower deductible) | Varies, can be $100+ | Varies, can be $1200+ | $300,000+ | $0 – $500 |
These are estimates. Your actual quotes will depend on your specific circumstances. Some specialty policies offer rates under $10 a month for basic coverage required by a landlord, while more complex cases involving a severe bite history will cost more but provide indispensable protection.
Navigating Insurance with “Restricted” Breeds or Bite Histories
If you own a breed on an insurer’s “blacklist” or if your dog has a past incident, you may have already faced the frustrating experience of rejection from standard carriers. This is a stressful and disheartening situation, but it is crucial to know that it does not mean you are out of options. Specialized insurance markets exist specifically to provide coverage for responsible owners in these exact situations.
We frequently help clients in Florida who own breeds like Pit Bulls, Rottweilers, or German Shepherds and have been denied coverage by their homeowners insurance company. The good news is that there are clear pathways to securing the protection you need, allowing you to keep your beloved pet and fulfill any legal or landlord requirements.
Why Breed Isn’t the Whole Story
At Florida All Risk Insurance, we believe that judging a dog solely by its breed is an inaccurate and unfair assessment of risk. A dog’s individual behavior is far more influenced by its upbringing, training, socialization, and the responsibility of its owner than by its genetics. Many dogs on so-called “dangerous breed” lists are loving, stable family companions with no history of aggression. As the American Veterinary Medical Association (AVMA) notes, breed is a poor sole predictor of bite risk. Responsible insurers understand this and focus on assessing each dog and owner individually rather than applying broad, discriminatory restrictions.
Finding Coverage for High-Risk Scenarios
Even if your dog has a bite history or belongs to a commonly excluded breed, specialized providers can offer the protection you need. Here’s how we help clients navigate these challenging situations:
- Specialty Insurance Providers: We partner with companies that cater specifically to owners of “restricted” breeds or dogs with bite histories. They offer standalone canine liability policies and use a more nuanced underwriting process that considers factors like training and containment, not just breed.
- Excess and Surplus (E&S) Lines: When standard, “admitted” markets won’t provide coverage, the E&S market acts as a crucial safety net. E&S carriers are regulated differently, allowing them to offer flexible solutions for unique and high-risk situations that standard insurers avoid. As independent agents, we have access to these specialized markets that are not available directly to the public.
- Working with an Independent Agent: This is where our expertise becomes invaluable. We leverage our extensive network of insurers, including these specialty and E&S markets, to find and compare dog liability insurance quotes for even the most challenging cases. We know which carriers are best for which scenarios.
Meeting Court or Landlord Requirements
Be prepared for higher premiums if your dog falls into a “high-risk” category. However, this increased cost is minimal compared to the financial devastation of an uninsured incident. Furthermore, these specialty policies are often the only way to meet mandates from a court, landlord, or Animal Control. For instance, if a Florida court declares a dog “dangerous,” the owner is often required by law to obtain and maintain a minimum of $500,000 in liability insurance. A specialty canine liability policy is designed to meet exactly this type of requirement, often with the ability to name the court or landlord as an additional insured.
For businesses involving dogs, such as groomers, trainers, or boarders, specialized animal bailee or professional liability coverage is also crucial, similar to other complex needs like Business Insurance for Small Businesses.
Protecting Your Family and Your Furry Friend
The potential for a dog-related incident, with its severe financial and emotional fallout, is a reality all owners must responsibly face. Being proactive is the only effective strategy. By thoroughly understanding the limitations of your current insurance, gathering the necessary information about your pet, and seeking expert guidance, you can secure affordable dog liability insurance quotes that provide robust financial protection. This crucial step is not just about buying a policy; it’s about safeguarding your assets, protecting your family’s future, and ensuring your dog can remain a happy and secure member of your family.
For Florida residents, navigating the unique and often difficult insurance landscape can be complex. The team at Florida All Risk Insurance specializes in finding custom solutions for hard-to-place risks, including for owners of restricted breeds and dogs with prior bite histories. As an independent agency based in Saint Petersburg, we provide personalized service and leverage our access to a wide range of carriers. This allows us to find custom coverage and competitive rates for clients across the state, from Miami to Jacksonville.
Don’t wait for a lawsuit to discover you’re underinsured. The peace of mind that comes from knowing you are properly protected is invaluable. Contact us today for a comprehensive review of your insurance needs and let our experts help you find the right coverage at the right price.
Ready to ensure your home is fully protected? Explore our comprehensive Florida Homeowners Insurance options and see how we can help you build a complete shield for your family and assets.
Contact Us
Florida All Risk Insurance
777 Central Ave, Saint Petersburg, FL 33701
Email: [email protected]

