

Does homeowners insurance cover watercrafts: Beware 2025
What Every Florida Boat Owner Needs to Know About Coverage
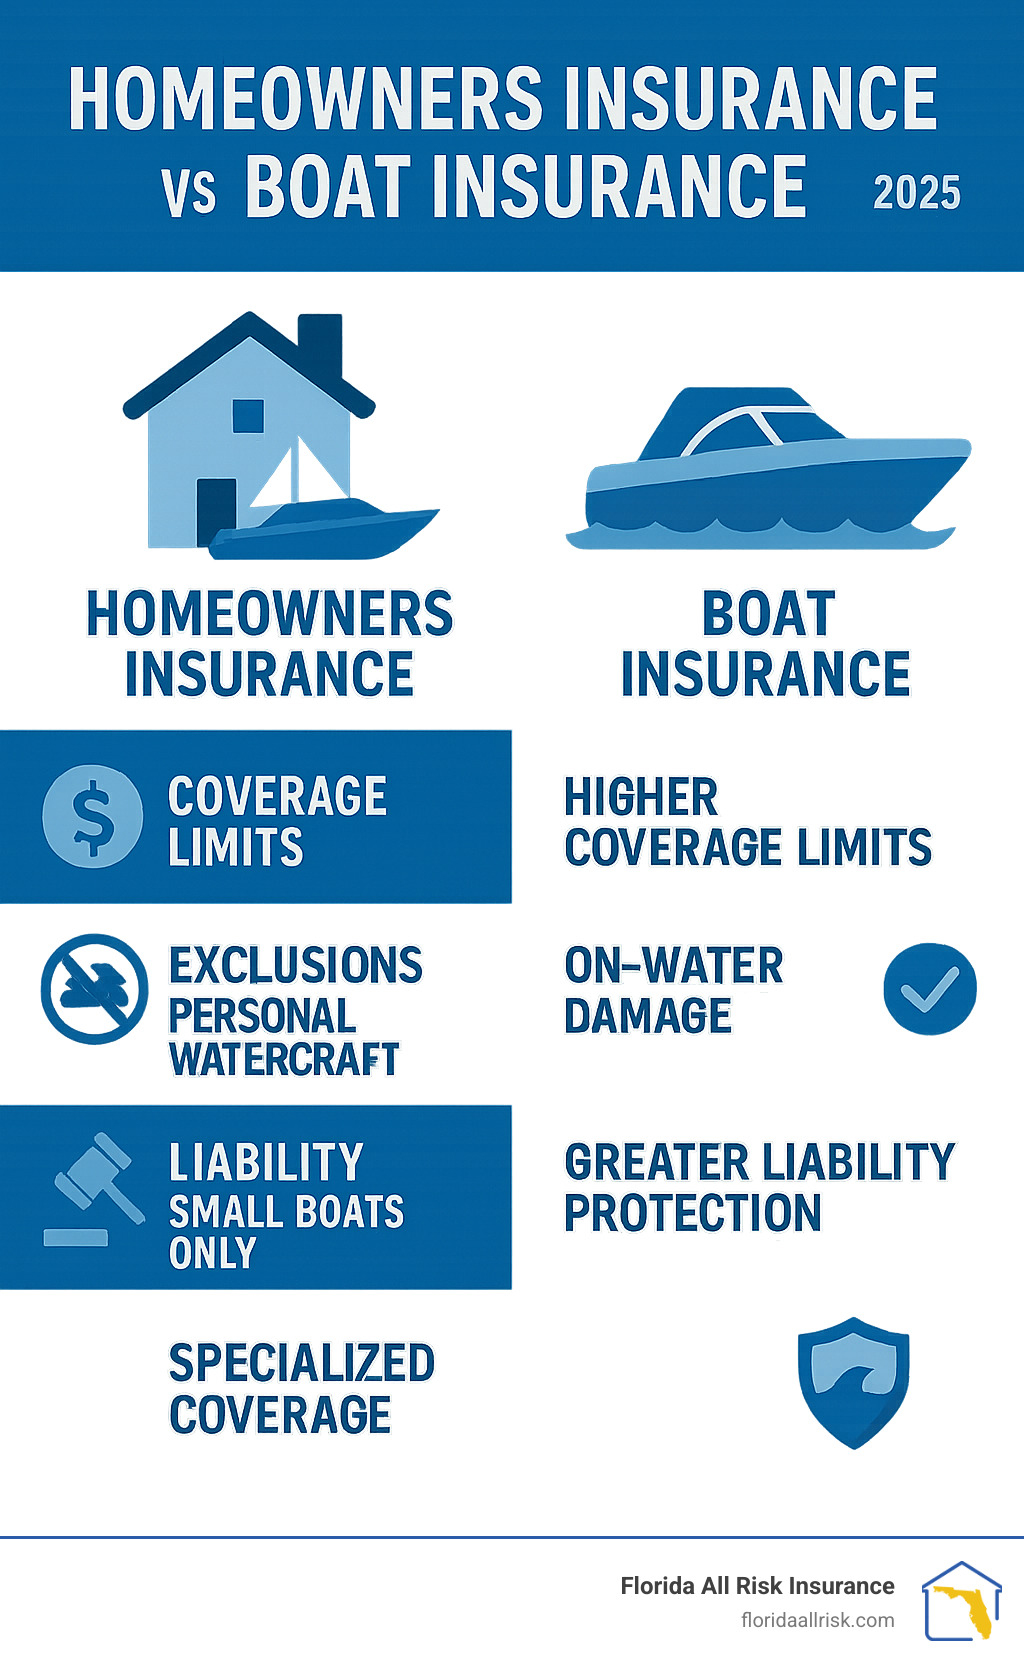
Does homeowners insurance cover watercrafts? The short answer is yes, but with severe limitations that could leave you financially exposed. Most policies only cover small boats for $1,000-$1,500 in damage, and only boats under 26 feet with engines under 25-50 horsepower qualify for any liability protection.
Quick Coverage Facts:
- Physical Damage: Limited to $1,000-$1,500 maximum
- Liability: Only for small boats (under 26 feet, low horsepower)
- Personal Watercraft: Jet Skis and similar craft are excluded
- On-Water Incidents: Most collision and sinking damage not covered
- Recommended Solution: Dedicated boat insurance for boats over $1,500
Living in Florida means enjoying some of the country’s most beautiful waterways. But many boat owners find too late that their homeowners policy offers a false sense of security. Homeowners insurance is designed for small craft like canoes, not the pontoons, fishing boats, and personal watercraft most Floridians own. The coverage gaps are significant, and the financial risks of being underinsured are enormous.
Jason Miller, owner of Florida All Risk Insurance, notes, “The right question isn’t if homeowners insurance covers watercraft, but whether that limited coverage is adequate. My team specializes in helping Florida families find the right protection for their needs on the water.”
What Your Standard Homeowners Policy Actually Covers for Watercraft
Does homeowners insurance cover watercrafts? Yes, but calling it “coverage” is generous. Your homeowners policy is designed to protect your house, not handle the unique challenges of Florida’s waterways. The boat coverage it offers is minimal and comes with strict limitations.
How Does Homeowners Insurance Cover Watercrafts for Physical Damage?
When people ask does homeowners insurance cover watercrafts for physical damage, the answer comes with a major reality check. While some coverage exists, it’s extremely limited.
- Location Matters: Most homeowners policies only cover your boat for physical damage when it’s on your property. The moment it’s on the water or at a marina, that coverage often disappears.
- Low Coverage Limits: The biggest surprise for most boat owners is the low payout limit, typically capped at just $1,000 to $1,500. This is barely enough to fix a minor scratch on most modern boats, let alone cover a significant loss like theft.
- Limited Perils: Coverage is usually restricted to specific events like fire or theft from your property. Key marine risks like sinking, collision, or running aground are almost always excluded. Damage from wind or hail is often only covered if the boat is stored in a fully enclosed building.
For a deeper understanding of how homeowners coverage works in our state, check out our comprehensive guide to Homeowners Insurance Florida.
What About Liability for Boating Accidents?
Liability is where relying on a homeowners policy becomes truly risky. While your policy might provide some liability protection if you cause an accident, it only applies if your boat meets very specific and restrictive criteria.
- Size and Horsepower Restrictions: Most policies draw a hard line at boats over 26 feet long or with engines exceeding 25-50 horsepower. This means the average Florida fishing boat, pontoon, or small cruiser is too large and powerful to qualify for liability coverage.
- Excluded Watercraft: The list of what isn’t covered is long. Personal watercraft (Jet Skis, WaveRunners) are universally excluded. Most powered boats that Floridians actually use for fishing and recreation are also left out.
Boating accidents can lead to massive financial liability. The U.S. Coast Guard reports that recreational boating accidents cause tens of millions in property damage and thousands of injuries annually. Without proper liability coverage, you could be personally responsible for medical bills and legal fees that can reach hundreds of thousands of dollars. Understanding these gaps is critical, especially in active boating communities like Pembroke Pines. Learn more in our Homeowners Insurance Pembroke Pines, FL guide.
The Major Gaps and Exclusions in Homeowners Watercraft Coverage
The real story of homeowners insurance for boats is not what it covers, but what it doesn’t. The list of exclusions is long, and any one of them could leave you facing significant out-of-pocket expenses after an accident. This is where the truth about does homeowners insurance cover watercrafts becomes starkly clear.
How Does Homeowners Insurance Cover Watercraft Value?
Even when your homeowners policy technically covers your watercraft, the way it values your boat often leaves you financially short.
- Actual Cash Value (ACV): Homeowners policies pay based on ACV, which is your boat’s current market value minus depreciation. Since boats depreciate quickly, your payout will be significantly less than what you need to buy a new, comparable boat.
- High Deductibles: Standard homeowners deductibles of $1,000 or more can easily wipe out the already low coverage limit of $1,000-$1,500, leaving you with little to no payout.
- Premium Increases: Filing a boat claim on your homeowners policy can lead to higher home insurance premiums at renewal, costing you more in the long run.
These limitations create huge financial gaps. For more insights, explore our resources on Home Insurance The Villages, FL.
What Are the Most Common Watercraft Exclusions?
The exclusions in homeowners policies are gaping holes that can sink your financial security. These aren’t minor technicalities; they are deliberate and can be financially devastating.
- Size and Horsepower Limits: As mentioned, most policies exclude boats over 26 feet or with engines exceeding 25-50 horsepower. This disqualifies a vast number of common recreational boats in Florida.
- Personal Watercraft (PWC) Exclusions: Jet Skis, WaveRunners, and similar craft are almost universally excluded from homeowners policies due to their higher risk profile. If you own a PWC, you have no coverage under your home policy.
- On-Water Collisions and Sinking: This is the most shocking exclusion for many. Your homeowners policy is not designed for marine perils. Damage from hitting a submerged object, colliding with another boat, or sinking is not covered.
- Business or Commercial Use: Using your boat for any income-generating activity, like chartering a fishing trip, will void your coverage.
- Racing Exclusions: Any participation in organized races or competitive events is excluded.
These exclusions exist because boats face unique risks that a homeowners policy isn’t built or priced to handle. For more on how market changes affect coverage, read about Another Home Insurance Company Leaving Florida.
The Superior Protection of a Dedicated Boat Insurance Policy
After seeing the severe limitations of homeowners coverage, the value of a dedicated boat insurance policy becomes clear. A specialized marine policy recognizes your vessel as a significant investment that faces unique risks. It’s built from the ground up to handle marine-specific challenges, offering comprehensive protection that makes sense for life on the water.
What Is Included in a Dedicated Boat Insurance Policy?
A proper boat insurance policy provides coverage that understands the boating lifestyle. These policies are designed by marine experts to protect you from the real-world risks you face.
- Hull Insurance: This is the core of your policy, covering physical damage to your boat from collisions, storms, theft, and sinking, whether it’s on the water, on a trailer, or at the dock.
- Agreed Value Coverage: Unlike a home policy’s Actual Cash Value, an Agreed Value policy pays out a predetermined amount in the event of a total loss. There are no deductions for depreciation, so you know exactly what you’ll receive.
- Total Replacement Value: For newer boats, this option provides enough to buy a brand-new, comparable model if your boat is a total loss.
- High Liability Limits: Boat policies offer liability limits from $100,000 to over $1,000,000, protecting your assets from costly lawsuits resulting from a boating accident.
- Medical Payments Coverage: This covers immediate medical needs for you and your passengers if an injury occurs on your boat, regardless of who is at fault.
For more information, visit our Watercraft & Boat Insurance Services page.
What Specialized Coverages Are Available?
Dedicated boat insurance shines with optional coverages that address specific boating scenarios.
- On-Water Towing and Emergency Assistance: Provides towing, fuel delivery, and jump-starts if you’re stranded on the water.
- Wreckage Removal: Covers the often-staggering cost of removing your boat if it sinks and becomes a hazard.
- Fuel-Spill Liability: Protects you from expensive cleanup costs and fines if your boat accidentally leaks fuel.
- Uninsured/Underinsured Boater Coverage: Steps in to cover your losses if you’re hit by a boater with little or no insurance.
- Personal Effects and Fishing Equipment: Covers your expensive gear, electronics, and other personal items on board.
- Trailer Coverage: Protects the trailer you use to transport your boat.
The National Boat Owners Association on policy types{:target=”_blank”} offers excellent insights into these options. This comprehensive protection shows why asking “does homeowners insurance cover watercrafts” misses the bigger picture. The real question is whether you have the right coverage.
When Do You Absolutely Need a Separate Boat Insurance Policy?
The line between when homeowners coverage might apply and when a dedicated policy is essential is clearer than you might think. If you answer “yes” to any of the following questions, you absolutely need a separate boat insurance policy to be adequately protected.
Is a Separate Boat Insurance Policy Necessary for My Vessel?
Answering the question “does homeowners insurance cover watercrafts” requires looking at your specific vessel and how you use it. Most boat owners in Florida quickly cross the threshold into needing a dedicated policy.
Ask yourself these key questions:
- Is my boat worth more than $1,500? If so, you’ve already exceeded the typical physical damage limit of a homeowners policy.
- Is my boat longer than 26 feet or does it have an engine over 50 horsepower? If yes, your boat is likely too large and powerful for any liability coverage under your home policy.
- Do I own a Personal Watercraft (PWC)? Jet Skis and WaveRunners are almost always excluded from homeowners insurance and require their own policy.
- Do I use my boat on the water? Homeowners policies exclude most on-water risks like collisions, sinking, and storm damage while underway. A dedicated policy is designed for these exact perils.
- Does my lender or marina require insurance? If you financed your boat or keep it at a marina, you will be required to carry comprehensive marine insurance with specific liability limits that a homeowners policy cannot meet.
If you answered “yes” to any of these, your homeowners policy is inadequate. A dedicated boat policy provides comprehensive protection with agreed value coverage, protecting you from the real hazards of boating. For residents in communities like Spring Hill, where boating is a way of life, understanding these distinctions is crucial. Learn more in our guide to Home Insurance Spring Hill, FL.
Navigating Your Options: Watercraft Endorsements vs. Standalone Policies
Some insurers offer a “watercraft endorsement” as an add-on to a homeowners policy. While it may seem like an easy fix, it’s often a halfway measure that can still leave you exposed. Understanding the difference between an endorsement and a full, standalone policy is key to making the right decision.
What Is a Watercraft Endorsement?
A watercraft endorsement is an amendment to your homeowners policy that attempts to fill some of its coverage gaps. It works by “buying back” some of the protection that is normally excluded. For instance, an endorsement might increase the physical damage limit from $1,500 to $10,000 and extend liability to slightly larger or more powerful boats.
While convenient, these endorsements are not a substitute for true marine insurance. The Insurance Information Institute on endorsements{:target=”_blank”} notes that they add back coverage but are still bound by the fundamental restrictions of a home policy. For context on overall coverage strategy, see our guide to the Best Homeowners Insurance in Florida 2025.
Is an Endorsement a Good Alternative to a Separate Boat Insurance Policy?
For most serious boaters, an endorsement is rarely the right answer. It’s like putting a bandage on a problem that needs surgery. Here’s why a standalone policy is superior:
- Coverage Limitations: Endorsements rarely match the comprehensive protection of a dedicated boat policy. They are still part of a homeowners policy framework, which was never designed for marine risks.
- Boat Age and Value Restrictions: Many endorsements have strict limits, refusing to cover boats over a certain age or value, leaving many owners without a viable option.
- Lack of Specialized Coverage: Crucial protections like on-water towing, wreckage removal, and fuel-spill liability are typically absent from endorsements. These are the very coverages that can save you from massive out-of-pocket costs.
- Claim Impact: A claim filed under your watercraft endorsement goes on your homeowners insurance record, which can cause your home premiums to increase.
A standalone boat policy avoids these issues. It offers broader coverage, higher limits, and specialized protections custom to your vessel. It also keeps your boat claims separate, protecting your home insurance history. While an endorsement is better than nothing for a very small boat, a dedicated marine policy is the only way to achieve real peace of mind. Our guide to the Top 10 Homeowners Insurance Companies in Florida can help you understand how different coverages work together.
Don’t Get Sunk by Inadequate Coverage
The truth is clear: relying on your homeowners insurance for your boat means accepting major gaps in physical damage coverage, severe limitations on liability, and no protection against common on-water perils. The financial and legal risks of a boating accident are simply too high to leave to chance.
Depending on homeowners insurance for your boat is like having car insurance that only works in your driveway. The moment you launch your boat, you enter a world of risks your home policy was never designed to handle.
We’ve seen too many Florida boat owners learn this the hard way. A client’s $25,000 center console wasn’t covered when it sank after hitting a submerged log. Another family faced a $150,000 lawsuit after a Jet Ski accident, only to find their homeowners policy excluded personal watercraft entirely. These aren’t rare occurrences—they’re predictable outcomes when adequate coverage isn’t in place.
The question is no longer does homeowners insurance cover watercrafts, but whether you can afford to be without proper marine insurance. Protecting your investment and your family requires a policy built for the water.
An independent insurance agent can help you steer your options and find a comprehensive policy that fits your vessel and boating lifestyle. The team at Florida All Risk Insurance is ready to help you assess your needs and ensure you have the right protection in place before you leave the dock. Don’t let inadequate insurance turn your perfect day on the water into a financial nightmare.
Conclusion
Ready to hit the water with confidence? Contact us today for a free, no-obligation quote on a comprehensive Watercraft & Boat Insurance policy.
Unsure about your current coverage? Let our experts review your Homeowners Insurance policy to identify potential gaps and ensure you’re fully protected.
Contact Us
Protecting your watercraft on Florida’s beautiful waters requires the right insurance partner. At Florida All Risk Insurance, we help you steer marine insurance with clarity and confidence. Our team provides peace of mind so you can focus on making memories on the water, not worrying about coverage.
As an independent insurance agency located in St. Petersburg, we work with multiple carriers to find you the best coverage at competitive rates. We can customize a policy that fits your specific vessel, boating habits, and budget.
Florida All Risk Insurance
Address: 7901 4th St. N STE 300, Saint Petersburg, FL 33702
Phone: (727) 577-2886
Email: [email protected]
Don’t let another boating season pass with inadequate coverage. Give us a call today, and let’s make sure you’re properly protected before your next adventure on the water.
For your reference, this article includes authoritative information from trusted sources including the U.S. Coast Guard Boating Statistics{:target=”_blank”}, the Insurance Information Institute on endorsements{:target=”_blank”}, and the National Boat Owners Association on policy types{:target=”_blank”}. All company links are absolute and direct to relevant product/service pages.

