

Compare Auto Insurance Quotes Florida 2025: Save Big
Why Florida Drivers Need to Compare Auto Insurance Quotes
{:alt=”Scenic Florida coastal highway representing the need to compare auto insurance quotes” data-metadata='{“title”:”Compare Auto Insurance Quotes Florida on a Coastal Highway”,”description”:”A scenic view of a Florida coastal highway with palm trees, representing the journey of finding the best car insurance rates in the Sunshine State.”,”keywords”:”compare auto insurance quotes florida, florida car insurance, auto insurance rates, coastal highway”}’}
For Florida drivers, the advice to compare auto insurance quotes Florida isn’t just a suggestion—it’s essential. Car insurance rates in the Sunshine State are among the highest in the nation, with drivers paying a staggering 68% more than the national average. A typical 6-month policy here costs around $1,841, far exceeding the $1,094 national average.
The good news is that you have the power to fight back against high costs. Here’s why shopping around is so critical:
- Significant Savings: Comparing quotes from at least three companies can save you up to $843 annually.
- Wildly Varying Prices: The exact same coverage could cost $200/month with one insurer and just $120/month with another.
- Personalized Rates: Every insurer weighs factors like your driving record, location, and credit score differently, creating a unique rate for you.
In a state where nearly half of all drivers feel they’re overpaying, comparison shopping is financial self-defense. The reasons for our high rates are complex, involving Florida’s no-fault system, a high number of uninsured drivers, severe weather risks, and insurance fraud. Understanding these factors is the first step, but actively comparing quotes is how you save.
At Florida All Risk Insurance, we’ve helped Florida families navigate this challenging market for over 20 years. As independent agents, we can help you find affordable, comprehensive coverage that protects what matters most.
Understanding Florida’s High Auto Insurance Costs
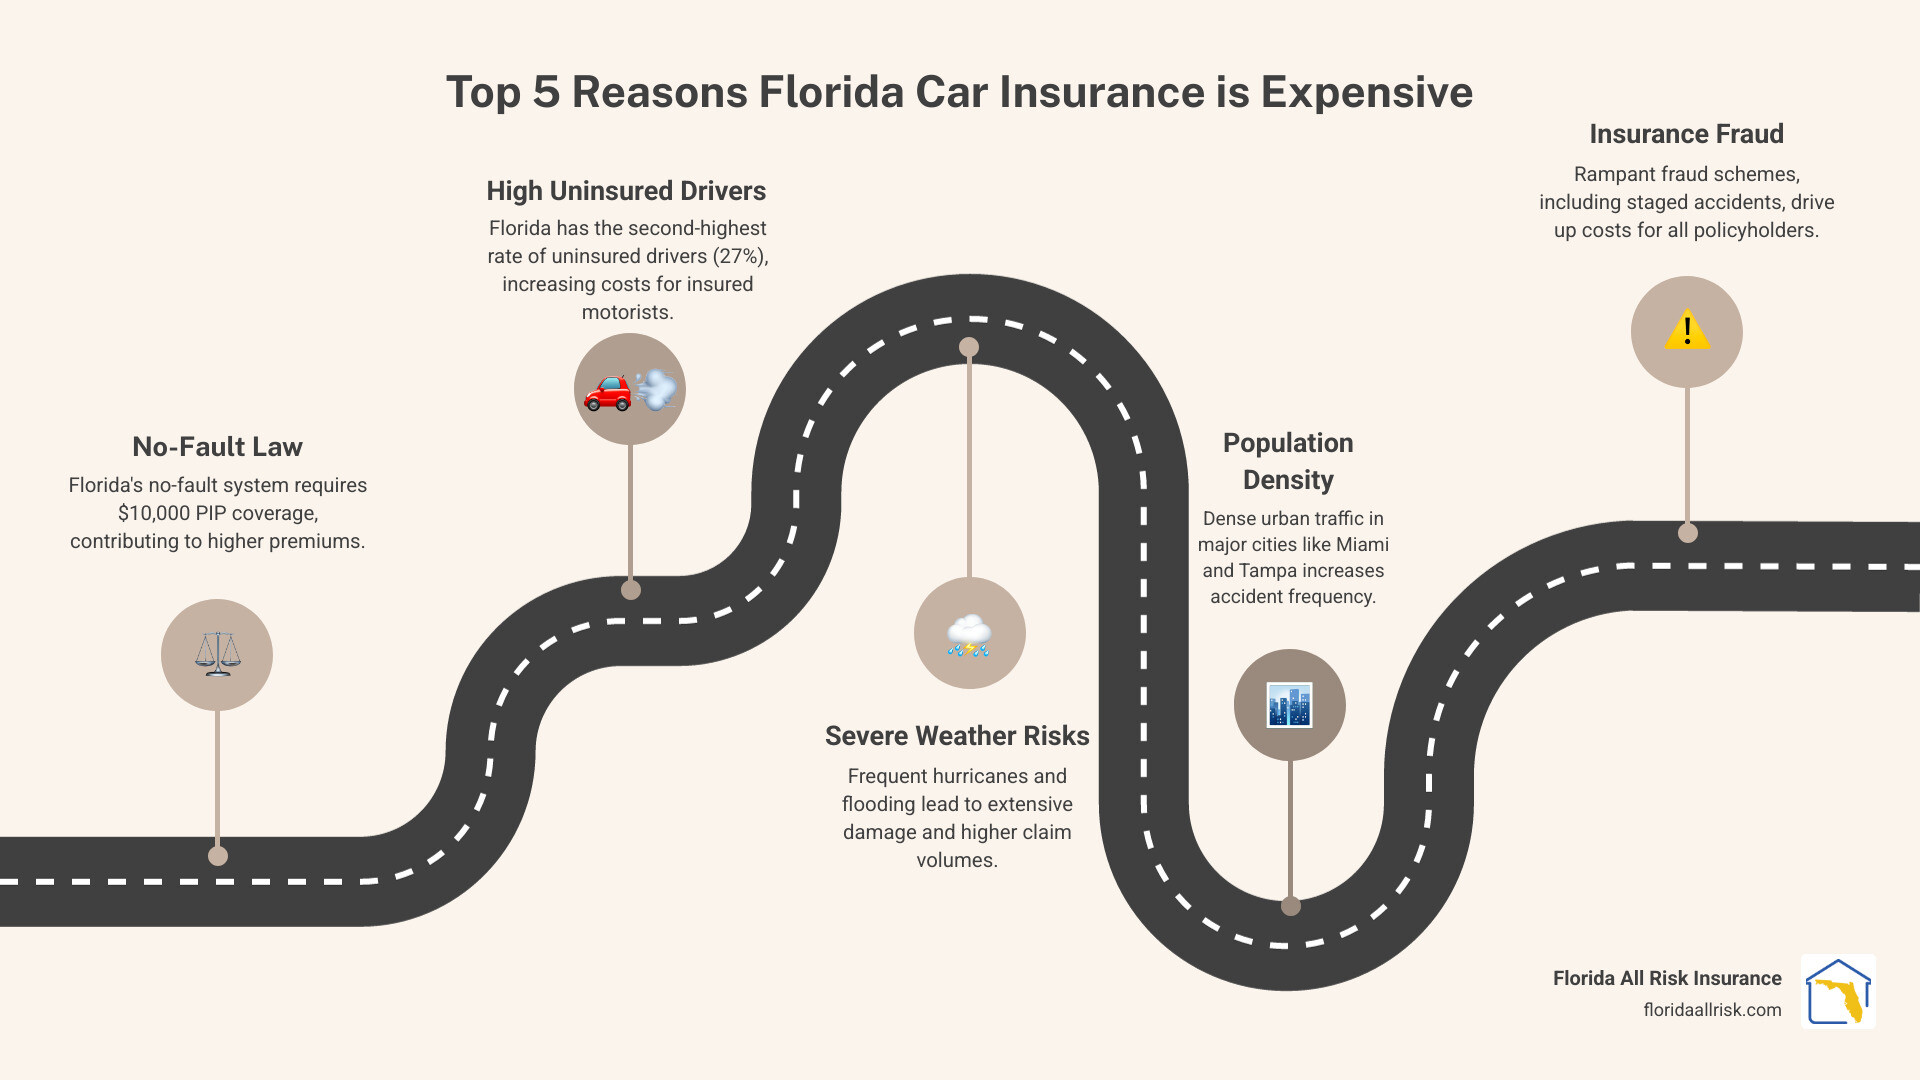
If you’ve ever winced at your Florida car insurance bill, you’re not alone. Our state consistently ranks among the most expensive for auto coverage due to a “perfect storm” of unique factors.
Florida’s No-Fault Insurance System: Florida law requires every driver to carry Personal Injury Protection insurance, or PIP. This means after an accident, your own insurance covers your initial medical expenses, regardless of who was at fault. While designed to speed up claims, this system leads to a high volume of payouts, driving up costs for everyone.
High Rate of Uninsured Drivers: Florida has one of the highest rates of uninsured motorists in the country. According to the Insurance Information Institute’s Facts + Statistics: Uninsured Motorists data, over 20% of drivers are on the road without coverage. When an uninsured driver causes an accident, insured drivers’ policies often have to cover the costs, especially if they have Uninsured Motorist Coverage Florida. These expenses are spread across all policyholders, increasing everyone’s premiums.
Population Density and Traffic: As the third most populous state, Florida’s major cities like Miami, Tampa, and Orlando are packed with vehicles. More cars on congested roads lead to a higher frequency of accidents. Insurers track this data by ZIP code, so living in a high-traffic area directly translates to higher rates.
Severe Weather: The Sunshine State’s tropical climate comes with the significant risk of hurricanes, tropical storms, and flooding. These events cause widespread vehicle damage, leading to a spike in comprehensive claims. Insurance companies factor this seasonal risk into their rates year-round.
Insurance Fraud: Unfortunately, Florida is a hotspot for insurance scams, from staged accidents to fraudulent medical billing. These criminal activities cost the industry billions annually, and those losses are passed on to honest policyholders through increased premiums.
Together, these factors explain why Florida drivers pay an average of $1,841 for a six-month policy—68% higher than the national average. Understanding these forces is key to navigating the market. Because different insurers weigh these risks differently, you can find significant savings when you compare auto insurance quotes Florida providers offer. For more details, visit our page on auto insurance rates florida.
Florida’s Minimum Car Insurance Requirements
To legally drive in Florida, you must understand and maintain the state’s minimum insurance requirements. Our no-fault system dictates that each driver’s own insurance covers their initial costs after an accident, regardless of fault.
Here’s what Florida law requires for every registered vehicle:
- Personal Injury Protection (PIP): You must carry at least $10,000 in PIP coverage. This pays for 80% of your medical bills and 60% of lost wages if you’re injured in an accident. It covers you, your passengers, and resident family members. Learn more about personal injury protection insurance.
- Property Damage Liability (PDL): You also need a minimum of $10,000 in PDL coverage. This pays for damage you cause to someone else’s property, such as their car or fence, in an at-fault accident.
This coverage must be maintained continuously. Letting it lapse can lead to severe penalties, including driver’s license and registration suspension for up to three years and reinstatement fees starting at $500. You can find official details on the Florida Insurance Requirements page. For more on meeting these basics, see our guide to basic auto insurance florida.
{:alt=”Document representing a Florida auto insurance policy” data-metadata='{“title”:”Florida Auto Insurance Policy Document”,”description”:”A close-up view of a generic auto insurance policy document, highlighting the legal and regulatory aspects of car insurance in Florida.”,”keywords”:”Florida auto insurance, insurance policy, legal requirements, car insurance document”}’}
Why Minimum Coverage Isn’t Always Enough
Meeting the state minimums keeps you legal, but it doesn’t keep you financially safe. The most significant gap is that Florida does not require Bodily Injury (BI) Liability coverage. If you cause an accident that seriously injures someone, your minimum policy pays nothing toward their medical bills or lost wages. You would be held personally responsible, potentially facing lawsuits that could threaten your savings, home, and future earnings.
This is why we strongly advise drivers to go beyond the minimum. When you compare auto insurance quotes Florida companies offer, consider these essential coverages:
- Bodily Injury Liability (BI): Protects your assets if you injure someone in an accident. We recommend limits of at least $100,000 per person and $300,000 per accident.
- Uninsured Motorist (UM) Coverage: This is critical protection in a state with so many uninsured drivers. It covers your injuries and damages when the at-fault driver has no insurance or not enough. Learn more about uninsured motorist coverage florida.
- Collision Coverage: Pays to repair or replace your vehicle after a collision, regardless of fault.
- Comprehensive Coverage: Protects your car from non-collision events like theft, vandalism, and natural disasters—a must-have for hurricane season.
Florida’s minimums are a starting point, not a complete solution. Building a policy that truly protects your assets is the smart move. Explore your options on our liability car insurance florida page.
Key Factors That Drive Your Florida Insurance Premiums
When you compare auto insurance quotes Florida insurers provide, you’ll see that prices vary dramatically. That’s because each company uses a unique formula to assess your risk based on dozens of personal factors. Understanding these factors helps you see why shopping around is so effective.
Your Driving Record and History
A clean driving record is your best asset for lower premiums. Insurers reward safe drivers. Conversely, blemishes can significantly increase your rates:
- At-fault accidents can raise your premium by an average of $992 per year in Florida, with the surcharge lasting for three to five years.
- Speeding tickets are red flags for risky behavior. According to NHTSA data on speeding, speeding is a significant contributing factor in motor vehicle fatalities, and even one ticket can increase your rates by 19% or more.
- DUI convictions are a major red flag, potentially increasing your costs by 50% or more and requiring a special FR-44 filing. Navigating this is tough, but our DUI auto insurance florida guide can help.
Your Location Within Florida
Where you park your car at night matters. Your ZIP code is a key rating factor based on local statistics for accidents, crime, and weather events.
- Urban areas like Miami and Tampa have higher population density and more traffic, leading to some of the highest rates in the state.
- Coastal regions face increased risk from hurricanes and flooding, which is factored into premiums.
- Less congested areas like Gainesville typically enjoy much lower rates due to reduced risk.
As a St. Petersburg-based agency, we have deep knowledge of local rate variations. Learn more on our auto insurance st petersburg page.
Your Vehicle and Coverage Choices
The car you drive and the coverage you select are major cost drivers.
- Vehicle Make and Model: High-performance cars, luxury vehicles, and those with high repair costs or theft rates will cost more to insure than a standard sedan with good safety ratings.
- Coverage Level: Choosing liability-only vs. full coverage is a primary decision. Full coverage (which adds collision and comprehensive) costs more but protects your own vehicle.
- Deductible Amount: Your deductible is what you pay out-of-pocket on a claim. Choosing a higher deductible (e.g., $1,000 vs. $500) will lower your premium. Explore your choices on our auto insurance deductible options page.
Personal Demographics
Insurers also use demographic data to predict risk.
- Age: Young, inexperienced drivers face the highest premiums. Rates typically decrease after age 25 and may begin to rise again for senior drivers. Our auto insurance for young drivers guide offers tips.
- Marital Status: Married individuals are statistically seen as lower risk and often receive lower rates.
- Credit-Based Insurance Score: In most states, insurers use a credit-based score to help predict claim likelihood. A better score can lead to lower premiums.
How to Effectively Compare Auto Insurance Quotes Florida
Knowing what drives your rates is half the battle; the other half is using that knowledge to shop effectively. This isn’t just about finding the cheapest price, but the best value. Following a simple process can save you hundreds annually. For more tips, check out our cheap auto insurance quotes florida guide.
Step 1: Gather Your Information
To get accurate, comparable quotes, have the following information ready before you start:
- Driver Information: Driver’s license numbers for all drivers in your household.
- Vehicle Information: The Vehicle Identification Number (VIN) for each car you want to insure.
- Location: Your primary garaging address (where the car is parked overnight).
- Driving Habits: An estimate of your annual mileage for each vehicle.
- Current Policy: Your current policy’s declaration page. This shows your existing coverage limits and deductibles, making it easy to compare apples-to-apples.
- Driving History: Be ready to disclose any accidents or tickets for all drivers in the last 3-5 years.
Step 2: Determine Your Ideal Coverage
This is the most critical step. Don’t just ask for the minimum; ask for the right coverage to protect your financial well-being. As we’ve discussed, Florida’s minimums leave you exposed.
- Assess Your Assets: If you own a home or have significant savings, you need robust Bodily Injury Liability coverage (we recommend at least 100/300 limits) to protect them from lawsuits.
- Protect Yourself: Given Florida’s high rate of uninsured drivers, Uninsured Motorist Coverage Florida is a must-have.
- Protect Your Vehicle: Decide if you need Collision and Comprehensive coverage. If your car is financed or leased, it’s required. If you own it, consider if you could afford to replace it out-of-pocket. Our auto insurance coverage options page can help.
- Choose Your Deductible: A higher deductible lowers your premium, but make sure it’s an amount you can comfortably pay. See our auto insurance deductible options page for guidance.
Once you’ve decided on your coverage levels, use these exact same limits and deductibles for every quote you request.
Step 3: The Best Way to Compare Auto Insurance Quotes Florida
Now it’s time to shop. The goal is to get quotes from at least three to five different insurers. The more you compare, the more you can save.
You could call each company individually, repeating your information over and over. Or, you can work with an independent insurance agent.
At Florida All Risk Insurance, we do the heavy lifting for you. As an independent agency, we work for you, not a single insurance company. We take your information once and shop it across our network of top-rated carriers to find the best combination of coverage, service, and price for your unique profile. We understand the Florida market and can find discounts you might miss on your own.
While online auto insurance quotes florida tools can provide a starting point, they often lack the personalization needed to secure the best deal. An agent can review quotes side-by-side, explain the differences, and offer insights into each company’s reputation for claims handling—a crucial factor that price alone doesn’t reveal.
Unlocking Discounts for Florida Drivers
Even with Florida’s high rates, there are numerous opportunities to save money through discounts. Many drivers don’t take full advantage of what’s available, but proactively asking for discounts can shave hundreds off your annual premium.
Common Discounts to Ask About
When you compare auto insurance quotes Florida insurers offer, make sure you’re asking about every possible discount. Here are some of the most common:
- Bundling/Multi-Policy: Combining your auto insurance with a home, renters, or boat policy from the same carrier can save you 15-25%.
- Multi-Car: Insuring more than one vehicle on the same policy usually earns a discount.
- Safe Driver: A clean driving record with no accidents or violations for 3-5 years is often rewarded with lower rates.
- Good Student: If you have a young driver on your policy with a B average or higher, you could save 10-20% on their portion of the premium. See our auto insurance for young drivers page for more.
- Vehicle Safety Features: Cars with anti-lock brakes, airbags, and anti-theft devices often qualify for discounts.
- Low Mileage: If you work from home or don’t drive much, you may qualify for a discount. Learn how low mileage can slash your florida car insurance bill.
- Payment Discounts: Opting for paperless billing or paying your premium in full upfront can often lead to small savings.
For a complete list, visit our florida car insurance discounts page.
Finding the Best Deals When You Compare Auto Insurance Quotes Florida
Stacking multiple discounts is the key to maximizing savings. An independent agent can help you identify all the discounts you qualify for across different carriers.
Consider telematics or usage-based insurance programs. These use a smartphone app or small device to monitor your driving habits. Safe drivers can earn significant discounts, often 20-30% or more, by demonstrating good habits like smooth braking and safe speeds. Learn more about safe driver insurance discounts.
Another strategy is to re-evaluate your coverage. The Insurance Information Institute suggests that if your car’s value is less than ten times your annual premium, you might consider dropping optional collision and comprehensive coverage. This is a great way to save on an older vehicle, but it requires careful consideration of your financial ability to replace the car if it’s totaled.
Frequently Asked Questions about Florida Auto Insurance
We know you have questions. Here are clear, straightforward answers to some of the most common inquiries we receive.
What is the average cost of car insurance in Florida?
The average cost for a 6-month policy in Florida is around $1,841, which is 68% higher than the national average. This translates to roughly $300/month for full coverage and $100/month for minimum coverage. However, this is just an average; your actual rate will depend on your unique profile, including your driving record, location, and vehicle.
What is the difference between liability-only and full coverage?
- Liability-Only Coverage in Florida typically means the state-required minimums: $10,000 in Personal Injury Protection (PIP) to cover your own injuries and $10,000 in Property Damage Liability (PDL) to cover damage you cause to others’ property. It does not cover damage to your own car.
- Full Coverage is a term for a policy that includes liability (PIP and PDL) plus Collision and Comprehensive coverage. Collision pays for damage to your car from an accident, while Comprehensive covers non-collision events like theft, fire, or storm damage.
How often should I compare car insurance quotes in Florida?
We recommend you compare auto insurance quotes Florida insurers offer at least once a year. Rates change constantly, so an annual review ensures you’re always getting a competitive price. You should also shop for quotes after any major life event that can affect your rates, such as:
- Moving to a new ZIP code
- Buying a new car
- Getting married
- Adding a teen driver to your policy
- A change in your driving record (like a new ticket or accident)
Conclusion
Navigating Florida’s auto insurance market is challenging. With rates 68% higher than the national average, complex laws, and unique risks, it’s easy to feel like you’re overpaying.
But you have more control than you think. Understanding the factors that drive your premium—from your driving record to your ZIP code—is the first step. The most powerful tool at your disposal, however, is comparison shopping.
When you actively compare auto insurance quotes Florida insurers offer, you leverage your power as a consumer. The same coverage can vary by hundreds, even thousands, of dollars between companies. Taking the time to shop around isn’t just a good idea; it’s the key to unlocking significant savings that you can put toward what matters most.
This is where an independent insurance agent provides best value. At Florida All Risk Insurance, we are your advocates. Based in St. Petersburg, we work with a wide range of top carriers to compare personalized quotes on your behalf. We explain the nuances of each policy and help you build custom coverage that fits your life. We know the Florida market because we live here too, and we’ve helped countless families find the right protection at a competitive price.
Ready to stop overpaying and find the best auto insurance rate for your needs? Contact us today for a personalized quote and discover how much you could be saving.
Explore our comprehensive auto insurance solutions and let our expert team guide you to significant savings while ensuring you get the protection you deserve.
Contact Us
Florida All Risk Insurance
6451 38th Ave N
Saint Petersburg, FL 33710
Phone: (727) 344-1400
Email: [email protected]

