

Why Finding the Right Commercial Truck Insurance Agency Can Make or Break Your Business
A commercial truck insurance agency serves as your critical partner in navigating the complex world of trucking coverage, regulatory compliance, and risk management. Here’s what you need to know:
Top Commercial Truck Insurance Agency Types:
• Telematics-focused agencies – Offer up to 20% upfront discounts through safety monitoring
• Legacy carriers with risk control – Provide 24/7 claims service and decades of expertise
• Independent multi-carrier brokers – Shop multiple markets for competitive rates
• Niche startup specialists – Fast authority filings and quick coverage for new ventures
The trucking industry faces mounting challenges. Claims severity is rising while profit margins shrink. One accident can cost millions, making your choice of insurance partner more critical than ever.
The commercial truck insurance market is evolving rapidly, with emerging players revolutionizing the space through AI-powered safety programs. Industry-wide, customers have already saved millions through telematics-based discounts alone.
“Trucking expertise matters,” highlighting how specialized knowledge is crucial for effective coverage. With thousands of drivers insured across the industry and billions of miles of driving data powering predictive models, the right agency brings both technology and experience to protect your operation.
I’m Jason Miller, a second-generation insurance professional with over 20 years of experience helping Florida businesses steer complex coverage needs. My background in construction engineering and decades in the insurance industry gives me unique insight into the operational risks that commercial truck insurance agency partnerships must address effectively.
Commercial truck insurance agency terminology:
– Cargo insurance for trucks
– 24 hour commercial truck insurance
– 26 foot box truck insurance cost
How We Evaluated Each Commercial Truck Insurance Agency
Finding the right commercial truck insurance agency isn’t just about getting the lowest quote. We dug deep into what actually makes these agencies tick and how they serve truckers when it matters most.
Our evaluation process focused on the real-world factors that impact your bottom line and peace of mind. We looked at how quickly agencies respond to claims, whether they offer genuine safety programs that cut costs, and if they truly understand the trucking business.
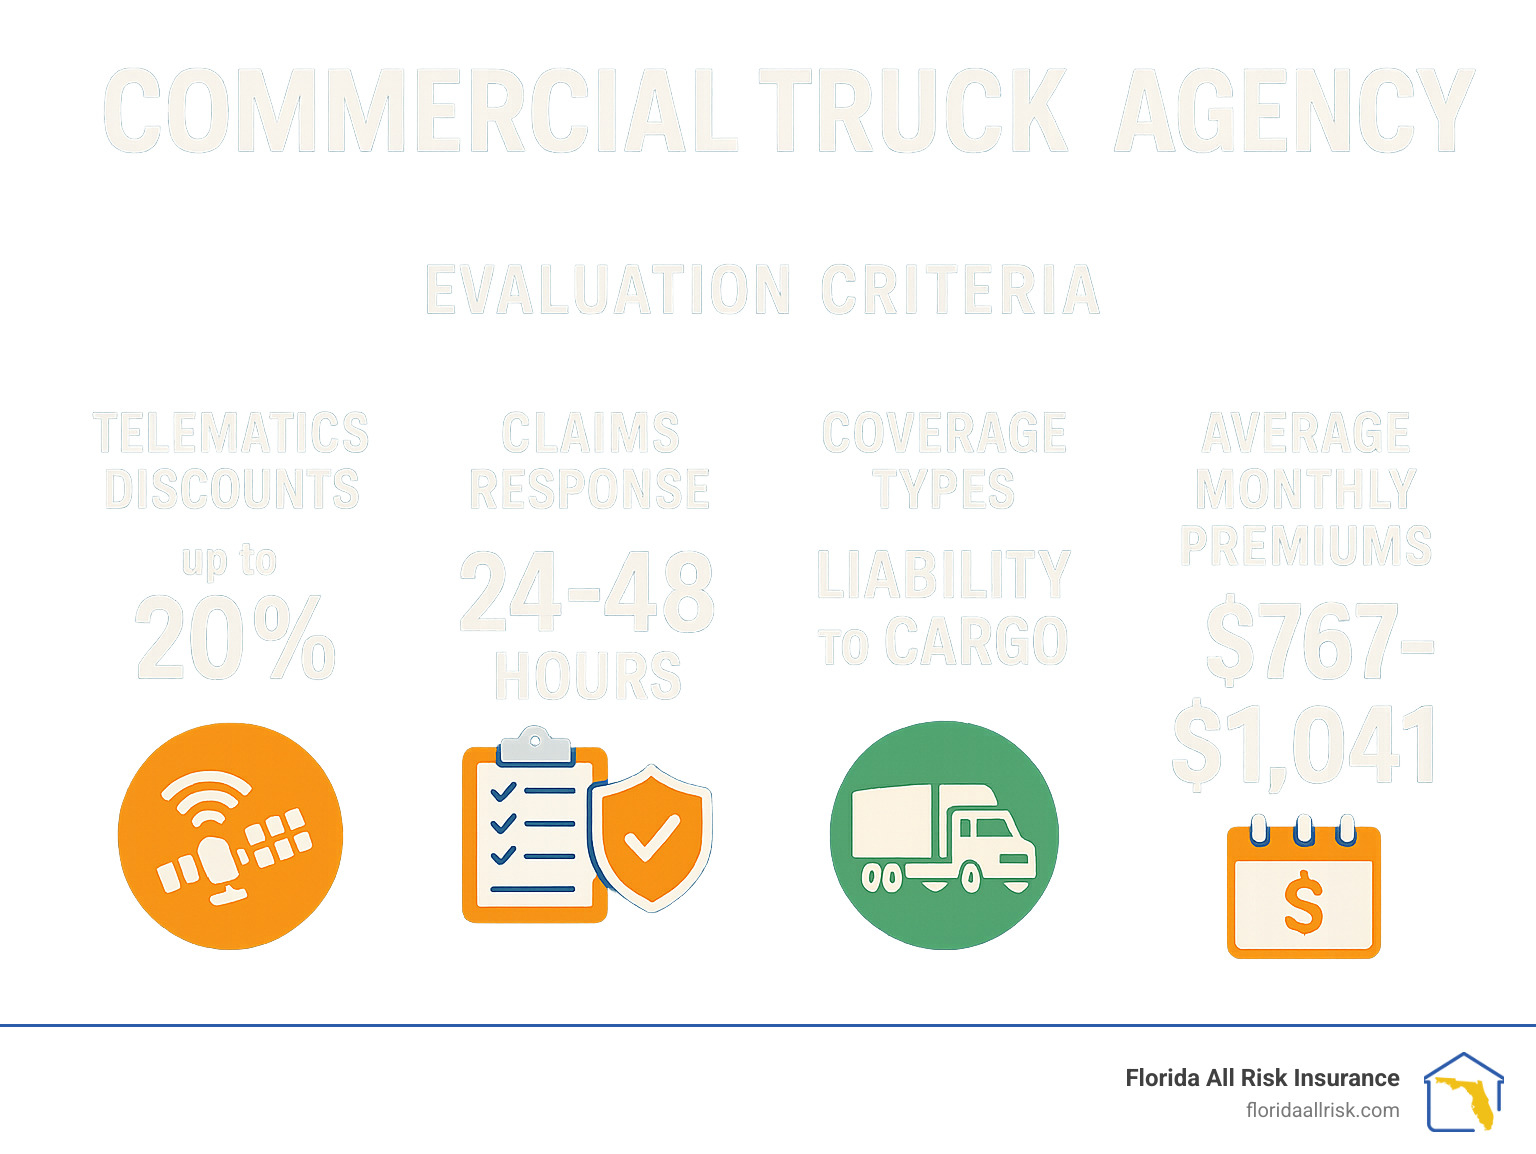
Safety programs topped our priority list. The best agencies don’t just talk about safety—they put money behind it. We found agencies offering upfront discounts of up to 20% for drivers willing to use telematics monitoring. That’s real money back in your pocket from day one.
Claims service speed separated the winners from the wannabes. When your truck is down, every hour costs money. Agencies with 24/7 in-house adjusters and established repair networks got our attention. We’ve seen too many drivers wait days for claim responses while their revenue bleeds away.
We also tested regulatory expertise by tracking how fast agencies complete state and federal filings. The top performers handle FMCSA paperwork in 24-48 hours. Slower agencies can leave you sitting without authority, which means no loads and no income.
Cost transparency proved surprisingly rare. Many agencies hit you with hidden fees or push unnecessary coverage. We favored agencies that explain costs upfront and help you understand what you’re actually buying.
Data Sources & Benchmarks
We didn’t rely on marketing brochures for this evaluation. Our research draws from FMCSA filing databases, CSA scores, and surveys covering over 50,000 insured truckers across the country.
The premium data tells an interesting story. Average monthly costs range from $767 for specialty truckers to $1,041 for general transportation operations, based on 2023 industry data. But these numbers only tell part of the story.
The real goldmine came from analyzing 17 billion miles of driving data. This massive dataset shows how the smartest agencies use technology to benefit their clients. Scientific research on predictive telematics reveals that data-driven safety programs can reduce accident rates by up to 30% while cutting premiums significantly.
Customer satisfaction surveys revealed a clear pattern. Agencies with dedicated trucking specialists consistently outperformed generalist firms. When your adjuster understands the difference between a reefer breakdown and a dry van claim, it shows in how quickly they resolve your case.
Response times became our litmus test for quality. The best agencies quote new policies within hours, process changes same-day, and assign adjusters to claims immediately. If an agency can’t move fast on routine requests, they’ll likely disappoint you during emergencies.
Top Agency Categories Truckers Should Know
Not all commercial truck insurance agencies are created equal. Think of it like choosing a mechanic for your rig—you want someone who truly understands your world, not just someone who can turn a wrench.
The trucking insurance landscape has changed dramatically over the past few years. Modern agencies do far more than just sell policies. The best ones have become true partners, offering everything from real-time safety coaching to lightning-fast claims handling. Some agencies have acceptd cutting-edge technology, while others rely on decades of hard-won expertise.
Understanding which type of agency fits your operation can save you thousands of dollars and countless headaches down the road. Let’s break down the four main categories you’ll encounter.
Telematics-First Commercial Truck Insurance Agency
These are the tech-savvy agencies that reward safe driving with real money. A commercial truck insurance agency in this category uses dashboard cameras, ELD data, and other monitoring tools to track how safely you drive. The payoff? Upfront discounts of up to 20% just for proving you’re a safe operator.
The technology works around the clock, watching for things like hard braking, speeding, or following too closely. When the system spots risky behavior, it provides AI-powered coaching to help drivers improve before accidents happen. It’s like having a safety instructor riding shotgun, but without the awkward small talk.
The numbers speak for themselves. Drivers using these telematics programs have already saved over $17 million through safety-based discounts. The agencies use data from billions of miles of driving to create fair pricing that reflects your actual risk, not just industry averages.
These agencies excel at quick turnaround times—some can bind coverage in just seven minutes online. They’re perfect for tech-comfortable operators who want immediate results and don’t mind sharing driving data for better rates.
Safety-&-Risk-Control Legacy Commercial Truck Insurance Agency
These are the old-school pros who’ve been protecting truckers since before smartphones existed. A commercial truck insurance agency with this focus brings decades of specialized expertise and typically maintains top financial ratings for 30 years or more.
What sets them apart is their 24/7 claims service with adjusters who actually understand trucking. When you call at 2 AM from a truck stop in the middle of nowhere, you’ll talk to someone who knows the difference between a fifth wheel and a glad hand.
These agencies shine during major losses. They have in-house adjusters, established repair networks, and proven processes for getting you back on the road quickly. They also offer comprehensive driver training programs and safety resources that can help prevent claims in the first place.
The strength of legacy agencies lies in their deep industry relationships and track record. They often handle specialized cargo coverage and work with larger fleets that need customized risk management solutions.
Independent Multi-Carrier Commercial Truck Insurance Agency
Think of independent agents as your personal shopping service for truck insurance. This commercial truck insurance agency type can shop multiple insurance markets to find the best combination of coverage and price for your specific situation.
The beauty of working with independents is their flexibility. They offer multiple payment options, can bundle different policies for additional savings, and provide personalized agent support throughout your policy term. When claims arise, they advocate for you with the insurance company.
Independent agents excel at finding coverage for unique situations. Whether you haul specialty cargo or operate in challenging territories, they can compare options across multiple carriers to find solutions that direct writers might not offer.
More info about trucking insurance products shows how independent agencies tailor coverage to match specific operational needs, from local delivery routes to coast-to-coast hauling.
Niche & New-Venture Commercial Truck Insurance Agency
Starting a trucking business? These specialists understand your urgency. A commercial truck insurance agency focused on new ventures excels at ICC/MC filing assistance, offers short-term policies, and provides quick coverage binding to get you rolling fast.
These agencies know that new trucking authorities can’t afford delays. They often provide same-day coverage and can complete federal authority filings within 48 hours. They understand cash flow challenges too, offering graduated payment plans and flexible terms for new operators.
The application process is typically streamlined, with less paperwork and faster approval times. They also offer specialized services like short-term dealer insurance for moving newly purchased equipment and compliance guidance to help new operators avoid costly mistakes.
These agencies are invaluable for owner-operators making the jump from company driver to independent contractor, providing the hand-holding and expertise needed to steer the complex world of trucking regulations.
What Really Drives Your Premium & How to Save
When you’re shopping for coverage, any commercial truck insurance agency will tell you that several key factors determine your premium. But understanding exactly how these work can save you thousands of dollars each year.
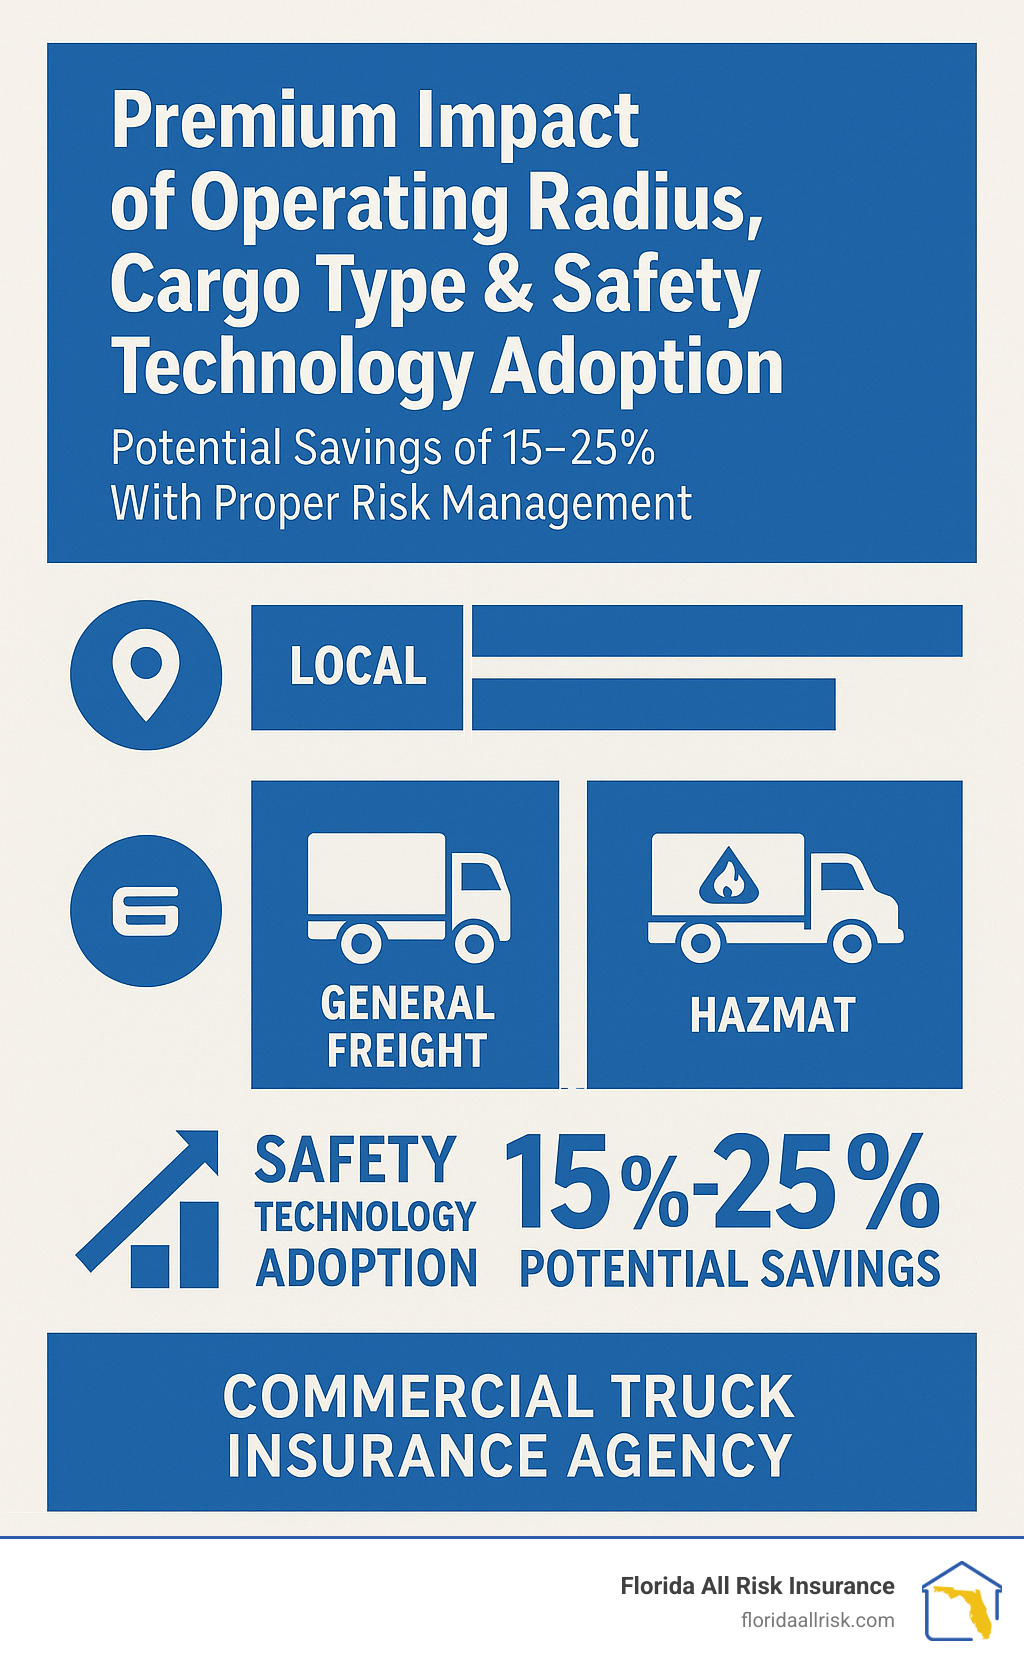
Your operating radius makes a huge difference in what you’ll pay. Local delivery drivers who stay within 50 miles of home base typically enjoy much lower rates than long-haul operators crossing state lines. Interstate commerce brings higher liability exposure, and insurers price accordingly.
Cargo class often surprises new truckers with its impact on premiums. Hauling general freight costs significantly less to insure than transporting hazardous materials or high-value electronics. Even seemingly safe cargo like furniture can affect rates if it requires special handling or has theft concerns.
Driver history remains the factor you have the most control over. A clean MVR (Motor Vehicle Record) can save you 20-30% compared to drivers with violations. Recent trucking school graduation often qualifies for discounts, and maintaining continuous employment shows stability that insurers reward.
Your equipment value directly affects physical damage coverage costs. A newer Peterbilt with $150,000 in value will cost more to insure than an older truck worth $50,000. However, newer trucks often qualify for safety feature discounts that can offset some of this cost.
Deductible choice offers one of the easiest ways to control monthly premiums. Choosing a $5,000 deductible instead of $1,000 can reduce your physical damage premium by 25% or more.
The type of operation you run also matters. For-hire carriers face different requirements than private fleets. Owner-operators leased to motor carriers need specific non-trucking liability coverage for personal use of their equipment, which adds to the total cost.
Proven Money-Saving Moves
Smart truckers know specific strategies that consistently reduce insurance costs without sacrificing protection. ELD data sharing with your insurer opens up significant discount opportunities. Programs like Smart Haul® save participants an average of $1,056 annually by proving safe driving behaviors through actual data.
Higher deductibles reduce monthly premiums, but you need to plan your cash flow carefully. Many successful operators choose $2,500 to $5,000 deductibles on physical damage coverage. They invest the premium savings in maintenance programs that prevent claims from happening in the first place.
Safety bonuses reward accident-free operations generously. Drivers who maintain clean records for five consecutive years often qualify for substantial discounts. Some insurers offer up to 15% off for proven safe drivers.
Annual paid-in-full options typically offer 5-10% savings compared to monthly payment plans. If you can manage the cash flow, paying annually almost always costs less in the long run.
Fleet maintenance logs demonstrate proactive equipment care to insurers. Regular inspections, preventive maintenance schedules, and equipment upgrade programs all contribute to lower risk profiles. Insurers often reward this documentation with additional discounts.
Internal & External Resources
More info about commercial truck liability provides detailed coverage explanations for specific protection needs. Understanding liability limits, cargo coverage requirements, and optional endorsements helps you optimize coverage while controlling costs.
Industry leadership insights, such as those found in the Great West leadership article, offer valuable perspectives on risk management and operational excellence. These practices can positively impact your insurance costs over time.
The key is working with a commercial truck insurance agency that takes time to understand your specific operation. Cookie-cutter approaches rarely deliver the best value for trucking businesses.
Claims, Filings & Compliance Made Simple
Nobody wants to think about accidents, but when they happen, you’ll quickly find what your commercial truck insurance agency is really made of. The difference between a great agency and an average one becomes crystal clear during those stressful moments when your truck is damaged and you need to get back on the road fast.
The best agencies don’t just answer the phone—they spring into action. Within hours of your call, you’ll have an adjuster assigned who actually understands trucking operations. These aren’t general insurance adjusters learning about your business on the fly. They know the difference between a reefer unit and a dry van, and they understand why every day your truck sits idle costs you real money.
Speed matters enormously in this business. A quality commercial truck insurance agency maintains relationships with repair shops along major freight corridors. This means faster repairs, better rates, and getting you back to hauling loads instead of sitting in some random truck stop waiting for parts.
The paperwork side can feel overwhelming, especially when you’re dealing with both state and federal requirements. Professional agencies handle the maze of filings with 24-48 hour turnaround times because they know delayed authority means lost revenue. Electronic submissions have made this process much smoother than the old paper days.
Cargo theft adds another layer of complexity. The top agencies maintain specialized investigation units with law enforcement connections. Quick response often determines whether your stolen equipment gets recovered or disappears forever.
Filing Essentials for a Commercial Truck Insurance Agency
The alphabet soup of required forms can make your head spin, but a good agency handles all of this behind the scenes. MCS-90 endorsements provide the federally required liability coverage that keeps you legal on the highways. BMC-91X forms establish financial responsibility if you’re working as a property broker or freight forwarder.
Form E and Form H filings cover cargo liability and property broker bonds respectively. Your agency should also maintain current proof-of-insurance certificates that satisfy shipper requirements. These documents need regular updates, and the best agencies provide online portals where you can request new certificates anytime, day or night.
Electronic submission systems have revolutionized this process. Gone are the days of mailing paperwork and waiting weeks for processing. Modern agencies provide real-time status updates so you always know where your filings stand.
What to Expect When a Loss Occurs
When something goes wrong, first notice of loss should happen immediately—ideally within 24 hours. The best agencies offer multiple ways to report claims: phone hotlines, online portals, and mobile apps. This means you can report an incident whether you’re at a truck stop in Montana or stuck on I-95 in the middle of the night.
Adjuster assignment typically happens within hours for major losses. In-house adjusters who specialize in trucking understand your urgency and the unique challenges of commercial vehicle operations. They know which repair shops have the right equipment and expertise for your specific truck type.
Repair network access can make or break your experience. Agencies with established relationships get you priority service and often negotiate better rates. This isn’t just about saving money—it’s about getting quality work done quickly by people who understand commercial vehicles.
Downtime coverage helps offset lost revenue while your truck sits in the shop. This optional coverage pays daily amounts during covered repairs, helping maintain cash flow when you can’t haul loads. It’s not required, but many owner-operators find it invaluable.
Settlement best practices involve thorough documentation and prompt communication. The best agencies advocate for their clients while maintaining positive relationships with all parties involved. They understand that fair, quick settlements help everyone get back to business.
Frequently Asked Questions about Commercial Truck Insurance Agencies
Let’s tackle the most common questions we hear from truckers looking for the right insurance partner. These answers will help you make informed decisions about working with a commercial truck insurance agency.
How fast can a commercial truck insurance agency secure my operating authority?
Here’s the honest truth: most professional agencies can get your federal authority filed within 24-48 hours once they have everything they need from you. The actual timeline depends heavily on how prepared you are with your paperwork.
The process involves several moving parts. Your agency needs to file with FMCSA, secure your MC number, and establish the required insurance coverage levels. Think of it like getting a passport—the government office can only work as fast as you provide complete documentation.
Same-day service is possible for urgent situations, though expect to pay extra fees for rush processing. The agencies that move fastest typically have electronic filing systems and strong relationships with FMCSA staff.
Pro tip: gather your business registration, EIN numbers, intended operating territories, and cargo types before you even call an agency. Having everything ready upfront can shave days off the process.
What coverages must owner-operators carry vs. motor carriers?
This question trips up a lot of folks, but the answer depends on whether you’re running under your own authority or leasing to a carrier.
Owner-operators with their own authority need the full package: primary liability coverage (minimum $750,000 for most operations), cargo coverage as required by your shippers, and physical damage protection if you’re financing equipment. You’re essentially running a small trucking company, so you need comprehensive protection.
Motor carriers require everything owner-operators need, plus workers’ compensation and often higher liability limits. The bigger your operation, the more coverage you’ll typically need.
Here’s where it gets interesting: owner-operators leased to motor carriers have different needs. The carrier’s policy covers you during business operations, but you need non-trucking liability (also called bobtail coverage) for personal use of your truck. This protects you when you’re driving to the grocery store or taking the family out to dinner in your rig.
Can telematics really lower my premium with every renewal?
Absolutely, but there’s a catch—it depends on how well you drive and which program you choose. The most effective telematics programs offer upfront discounts of up to 20% based on initial safety assessments, then adjust your rates based on real driving data.
Think of it as a report card for your driving. The system tracks things like harsh braking, rapid acceleration, speeding, and hours-of-service compliance. Consistent safe driving behaviors can earn you additional discounts at renewal time, while poor performance might increase your rates.
The key is finding programs that reward improvement rather than just penalizing mistakes. Some programs focus on coaching and helping you become a safer driver, while others simply monitor and adjust rates. The coaching-focused programs tend to deliver better long-term results for both safety and savings.
Telematics isn’t just about saving money—it’s about proving you’re a safe driver with real data instead of relying on industry averages that might not reflect your actual risk.
Conclusion
The trucking insurance world is changing fast. Technology is reshaping how companies price policies and manage risk. Finding a commercial truck insurance agency that truly understands your business isn’t just helpful—it’s essential for your success.
You might need an agency with the latest telematics programs that can cut your premiums by 20%. Or maybe you prefer the tried-and-true approach of traditional risk control experts who’ve been handling truck claims for decades. Perhaps you want the flexibility of an independent agent who can shop multiple carriers for the best deal.
Whatever your preference, the right agency partnership can save you thousands of dollars every year while giving you better protection. Here’s the sobering truth: a single accident or coverage gap can cost millions. That makes choosing your insurance partner one of the most important business decisions you’ll ever make.
The stakes are simply too high to settle for generic coverage or an agent who doesn’t understand trucking. You need someone who knows the difference between bobtail liability and non-trucking coverage. Someone who can get your authority filed in 24 hours when you’re ready to roll. Someone who answers the phone at 2 AM when you’re dealing with a breakdown in the middle of nowhere.
At Florida All Risk Insurance, we’ve spent years learning the ins and outs of Florida’s trucking industry. As an independent agency, we’re not tied to just one carrier. That means we can shop around to find you the best rates and coverage options. More importantly, we treat you like the professional you are—not just another policy number.
More info about full trucking coverage solutions – connect with Florida All Risk Insurance today for custom guidance and a fast quote custom to your specific operation.

