

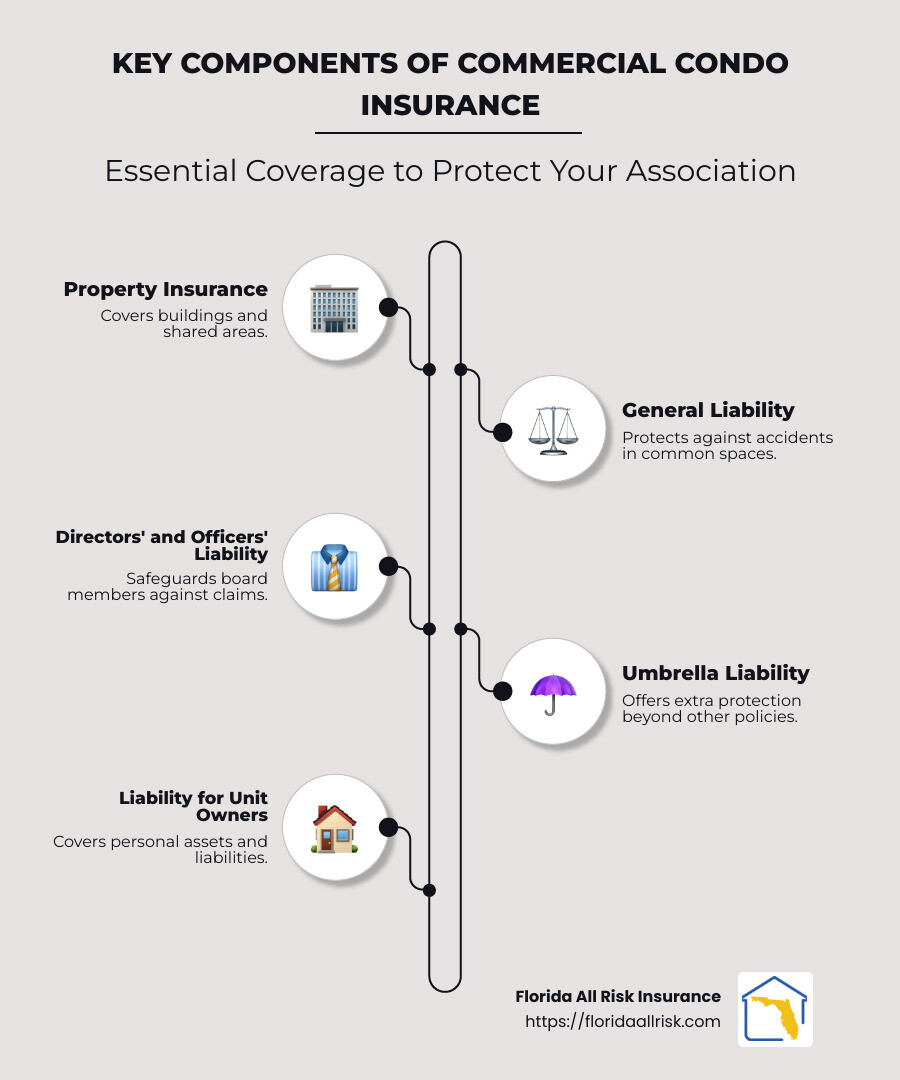
Commercial condo insurance is essential for condominium associations because it safeguards the financial interactions and responsibilities of shared property assets. As these associations own the building structures and common areas, having the right insurance coverage is vital. Here’s a quick look at what commercial insurance for condo associations entails:
- Property Insurance: Protects the building and common areas.
- General Liability: Covers accidents in communal spaces.
- Directors’ and Officers’ Liability: Shields board members from wrongful act claims.
- Umbrella Liability: Offers additional coverage beyond standard policies.
Navigating these options ensures the association is well-protected from financial risks, enabling a focus on managing and enhancing the community.
I’m Jason Miller, a seasoned insurance professional dedicated to guiding you through the intricacies of commercial condo insurance. My 20-year experience in Florida ensures you have the best coverage custom to your needs. Transitioning next, we’ll explore the core components of this insurance to help you make informed decisions.
Know your commercial condo insurance terms:
- all risk commercial property insurance
- commercial property insurance risk
- high risk commercial property insurance
Understanding Commercial Condo Insurance
Commercial condo insurance is crucial for both unit owners and condo associations. It covers different aspects of a condominium community, providing peace of mind and financial protection.
Unit Owner Coverage
For individual unit owners, insurance often focuses on the interior of their units. This is known as “walls-in” coverage. It includes protection for personal property like furniture, electronics, and appliances. Additionally, it offers personal liability coverage. This means if someone gets injured inside your unit, your insurance can help cover medical and legal expenses.
Master Policy
The master policy is purchased by the condo association. It covers common areas such as hallways, roofs, and amenities like pools or gyms. There are three main types of master policies:
- Bare Walls: This is the most basic, covering only the structure and common areas.
- Single Entity: Covers everything in the bare walls policy plus built-in property like fixtures.
- All-in: The most comprehensive, covering all property owned by the condo association and part of the building’s structure.
The master policy’s cost is shared among unit owners through condo fees.
Liability Protection
Liability protection is a significant component of both unit owner policies and master policies. It safeguards against claims or lawsuits for injuries or damages that occur on the property. For unit owners, this means protection within their units. For the condo association, it covers incidents in common areas.
Why is this important? Without adequate liability protection, a single lawsuit could lead to substantial financial loss for either a unit owner or the entire condo association.
Understanding these components of commercial condo insurance ensures that both unit owners and associations are well-protected. It’s important to regularly review your coverage needs and adjust your policy to fit any changes in your living situation or the condo’s master policy.
Next, we’ll dive deeper into the key components of commercial condo insurance to help you choose the right coverage.
Key Components of Commercial Condo Insurance
Commercial condo insurance is essential for protecting the interests of condominium associations. Here’s a closer look at its key components:
Property Insurance
Property insurance is vital for covering the physical assets of the condominium association. It includes the building itself and any related structures. This insurance ensures that if a disaster strikes, like a fire or severe storm, the financial burden of repairing or rebuilding the property doesn’t fall solely on the association.
-
Replacement Cost vs. Agreed Value: Associations can choose between insuring the property at replacement cost or opting for an agreed value endorsement. The latter can help avoid co-insurance penalties.
-
Business Income Coverage: If your condo association rents out spaces, this coverage can compensate for lost rental income due to property damage.
-
Equipment Breakdown Coverage: Covers sudden mechanical failures of essential systems like HVAC or elevators, which can be costly to repair.
General Liability
General liability insurance protects the condo association from claims related to accidents in common areas. This coverage is crucial for safeguarding against incidents ranging from a slip-and-fall to more severe accidents, like construction mishaps that could lead to bodily injuries or property damage.
“General liability insurance can prevent a legal suit from turning into a financial disaster by providing financial protection in case your business is ever sued or held legally responsible for some injury or damage.”
Directors’ and Officers’ Liability (D&O)
Directors’ and officers’ liability insurance is designed to protect the board members of a condo association. It covers claims related to “wrongful acts” such as discrimination or failure to enforce rules. This insurance often includes coverage for legal defense costs, which can be significant.
Umbrella Liability
An umbrella liability policy provides additional coverage beyond the limits of the primary general liability and D&O policies. This is particularly useful for larger associations or those with higher risk exposures. It acts as a financial safety net, offering extra protection against major claims or lawsuits.
Each of these components plays a critical role in a comprehensive commercial condo insurance policy. Together, they ensure that both the physical property and the financial interests of the condo association are well-protected.
Next, we’ll explore how to choose the right coverage for your condominium association.
How to Choose the Right Coverage
Choosing the right commercial condo insurance coverage requires careful consideration of several key factors. Here’s how you can make informed decisions:
By-Laws Review
Start by reviewing your condo association’s by-laws. These rules outline what the association must cover and what individual unit owners are responsible for. Understanding these details helps ensure that your insurance policy aligns with your obligations.
- Master Policy vs. Unit Owner Responsibilities: The master policy typically covers common areas and building structures. However, unit owners might need additional coverage for interior elements and personal property.
Deductible Considerations
Deductibles play a crucial role in determining your insurance costs. A deductible is the amount you pay out-of-pocket before the insurance kicks in.
-
Higher Deductibles, Lower Premiums: Opting for a higher deductible can reduce your premium. However, ensure that the deductible is affordable in the event of a claim.
-
Master Policy Deductible: Be aware of the master policy’s deductible, as it can change annually. Keeping your policy in sync with the master policy avoids unexpected costs.
Additional Coverages
Beyond the basic components, consider additional coverages that address specific risks your condo association might face.
-
Loss Assessment Coverage: This covers your share of a loss assessment charged by the association for damages to common areas.
-
Flood and Earthquake Insurance: If your condo is in a high-risk area, these coverages can provide crucial protection against natural disasters not typically covered by standard policies.
-
Ordinance or Law Coverage: This helps cover the costs of upgrading to current building codes during repairs.
By taking these steps, you can tailor your commercial condo insurance to meet the specific needs of your association. This ensures comprehensive protection and peace of mind for all parties involved.
Next, we’ll answer some frequently asked questions about commercial condo insurance.
Frequently Asked Questions about Commercial Condo Insurance
What is a commercial property insurance policy?
A commercial property insurance policy is designed to protect a condo association’s physical assets. This includes buildings, common areas, and sometimes personal property within the units. The policy typically covers damages from events like fire, theft, vandalism, and certain natural disasters.
-
Building Protection: The policy ensures that the main structure and any attached fixtures are covered. This is crucial for maintaining the integrity of the property.
-
Tools and Equipment: If your condo association owns tools or equipment used for maintenance, these can be included in the coverage. This protects against loss due to theft or damage.
What are the two types of commercial insurance?
When it comes to commercial insurance, there are two primary types:
-
Property Insurance: This covers the physical assets of the condo association. It includes buildings, equipment, and sometimes the personal property within units.
-
Casualty Insurance: This type of insurance covers liability issues. It protects the association from claims related to injuries or damages that occur on the property.
What is a deductible for commercial property insurance?
A deductible is the amount of money a policyholder must pay out-of-pocket before the insurance policy begins to cover a loss. Understanding deductibles is important for managing costs and ensuring affordability.
-
Policyholder Responsibility: The deductible is the policyholder’s responsibility, so it’s crucial to choose an amount that you can afford to pay in case of a claim.
-
Loss Affordability: Opting for a higher deductible can lower your premium, but it means you’ll pay more upfront if a loss occurs. Balancing these factors helps in maintaining a cost-effective insurance strategy.
By understanding these key aspects of commercial condo insurance, condo associations can better steer their coverage options and choose the best protection for their needs.
Next, we’ll conclude by highlighting the benefits of working with Florida All Risk Insurance for your commercial condo insurance needs.
Conclusion
Choosing the right insurance for your condo association is crucial. At Florida All Risk Insurance, we understand the unique needs of condo associations and specialize in providing custom coverage solutions that fit those needs perfectly.
Our team in St. Petersburg, Florida, is committed to offering personalized service to each of our clients. As an independent agency, we have access to a wide range of carriers, which means we can offer you the most competitive rates available. This flexibility allows us to tailor insurance packages that ensure comprehensive protection for your condo association without breaking the bank.
Whether you’re looking to protect your property, manage liability risks, or ensure your board of directors is covered, we are here to help. Our expertise in commercial condo insurance means you can trust us to guide you through the complexities of insurance policies and help you make informed decisions.
For more information on how we can help protect your condo association, visit our Commercial Property Insurance page.
Partner with us at Florida All Risk Insurance and experience peace of mind knowing your condo association is well-protected.

