

Protecting Your Business with Comprehensive Coverage
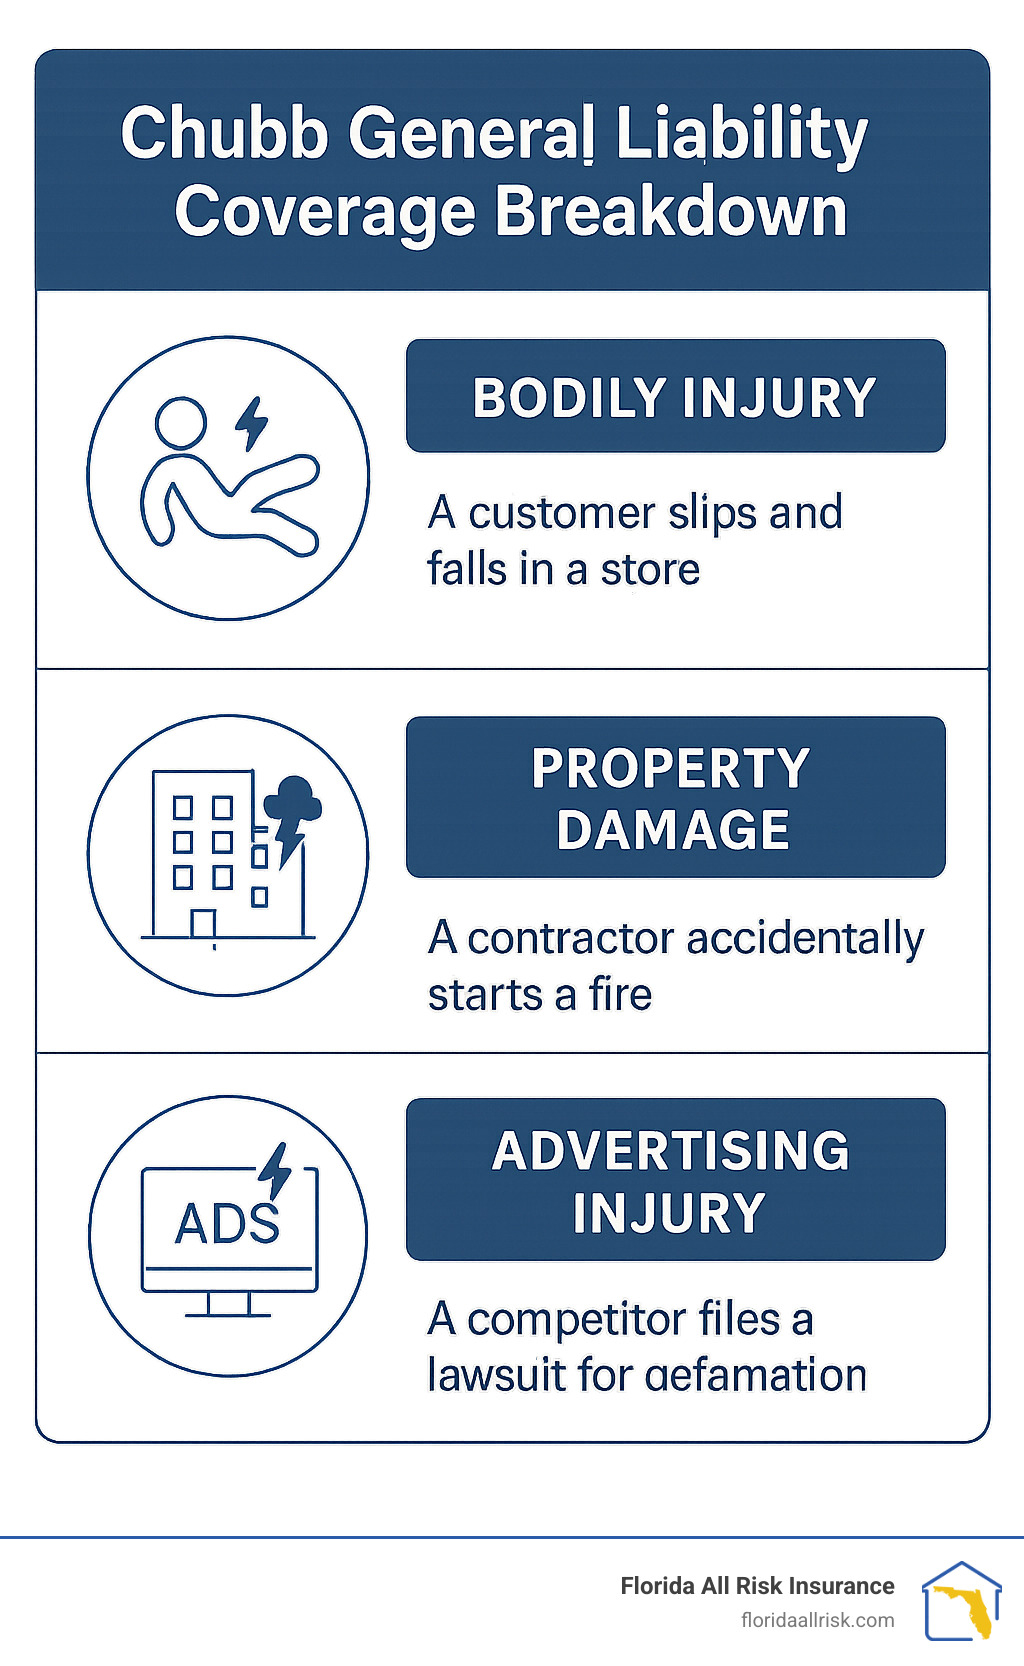
Chubb general liability insurance provides essential protection for businesses against third-party claims of bodily injury, property damage, and advertising injury. This foundational coverage helps shield your company’s assets from potentially devastating lawsuits and financial losses.
Quick Guide to Chubb General Liability
- Coverage: Bodily injury, property damage, personal & advertising injury
- Capacity: Up to $100 million available
- Global Reach: Operations in 54 countries with capabilities in 200+ countries
- Target Markets: Businesses of all sizes across 500+ eligible classes
- Key Features: Worldwide territory coverage, automatic additional insured status for vendors and subsidiaries
- Differentiators: Award-winning claims handling, crisis assistance, product withdrawal coverage
In today’s litigious business environment, having robust liability protection isn’t just smart—it’s essential. Chubb’s general liability insurance stands out for its comprehensive coverage, financial strength backed by over $200 billion in assets, and exceptional claims service consistently ranked #1 by risk managers.
What makes Chubb’s offering unique is its flexibility. Policies can be purchased as standalone coverage or packaged with property insurance. They can be written on either an occurrence or claims-made basis, giving businesses options that align with their specific risk management strategies.
I’m Jason Miller, and with over 20 years of experience helping Florida businesses find the right insurance protection, I’ve seen how Chubb general liability coverage provides critical protection for companies facing evolving liability exposures.
Chubb general liability definitions:
– general risk insurance
– excess public liability
– professional liability insurance for independent contractors
Understanding Chubb General Liability Insurance
When it comes to protecting your business from unexpected claims, Chubb general liability insurance stands out as a powerhouse solution. This comprehensive coverage is designed with one clear purpose: to shield your business from third-party claims that allege bodily injury, property damage, or personal and advertising injury. With impressive capacity to provide up to $100 million in coverage, Chubb offers the financial muscle many businesses need for true peace of mind.
Chubb isn’t just any insurer – as the world’s largest publicly traded property and casualty insurance group, they’ve built a remarkable global presence. Operating in 54 countries with capabilities extending to over 200 countries worldwide, Chubb can follow your business wherever opportunity leads you. This extensive reach makes them an ideal partner whether you’re a local Florida business with dreams of expansion or already operating across borders.
What makes Chubb general liability particularly valuable is its worldwide territory coverage for suits brought in North America. Plus, you’ll appreciate that Chubb automatically includes vendors, real estate managers, and lessors of equipment and premises as insureds – no separate endorsements needed. This thoughtful approach means broader protection is built right into your policy from day one.
Who Needs Chubb General Liability?
While virtually every business faces some degree of liability risk, certain operations especially benefit from Chubb’s specialized approach.
If you’re running a start-up or small business, Chubb’s Business Owner’s Policy (BOP) offers custom protection for companies with up to $30 million in annual revenue across more than 500 business classes. It’s big protection scaled perfectly for growing companies.
Manufacturers face unique challenges with product liability exposures, which is why Chubb’s robust coverage includes automatic product withdrawal expense coverage – a feature that can save the day if you ever need to recall products.
For contractors and construction companies performing work at client sites, Chubb’s broad contractual liability coverage and premises operations protection provides essential safeguards against the many risks you face daily.
Wholesalers and distributors in the supply chain gain automatic vendors coverage and protection against claims stemming from distributed products – crucial protection for businesses that move goods from makers to markets.
Service firms providing professional expertise can combine general liability with specialized coverages like errors and omissions protection, creating a comprehensive shield against the unique risks you face.
Key Features of Chubb General Liability
At its core, Chubb general liability insurance includes several fundamental protections that form the backbone of your business security.
Bodily injury coverage protects you when someone claims physical harm occurred because of your business operations. This extends beyond just the physical injury to include resulting mental anguish, shock, or humiliation. Imagine a customer slipping on your freshly mopped floor – this coverage would respond to their injury claim.
Property damage liability has your back when someone claims you’ve damaged their property. Chubb goes further with broad form property damage that extends protection beyond typical policies, giving you more comprehensive coverage.
Personal and advertising injury protection is increasingly important in today’s digital world. This covers claims alleging libel, slander, copyright infringement, and invasion of privacy. Chubb even extends this to include discrimination, harassment, and segregation (except employment-related incidents).
Medical payments coverage handles medical expenses for minor injuries regardless of fault. Chubb’s three-year reporting period from the date of accident is longer than many standard policies, giving injured parties more time to seek necessary treatment.
Vendors coverage automatically extends protection to vendors selling or distributing your products – a thoughtful feature that manufacturers and distributors particularly value.
With Chubb general liability insurance from Florida All Risk Insurance, you’re not just buying a policy – you’re securing a partnership with a global leader that understands the unique challenges Florida businesses face. Learn more about what general liability insurance covers to ensure your business has the protection it deserves.
Core Coverages & Flexible Improvements
When you invest in Chubb general liability insurance, you’re getting a protection package built to handle real-world business challenges. Think of it as your business’s safety net – there when you need it most.
Premises and Operations Liability
Ever worry about someone getting hurt at your business location? This coverage has your back. If a client slips on your freshly mopped floor or a delivery person tumbles down your steps, premises liability coverage steps in to help. It covers the everyday risks that come with simply opening your doors for business.
Products and Completed Operations
This protection is crucial if you make, sell, or distribute products – or if you complete work for clients. Imagine you’re a contractor who installed flooring that later buckles and causes someone to fall, or you’re a manufacturer whose product malfunctions and damages a customer’s home. Chubb general liability would help cover these situations, protecting your business from potentially devastating claims.
Contractual Liability
Business contracts often require you to accept certain liabilities – it’s just part of doing business. Chubb includes broad contractual liability coverage that protects you when you’ve assumed liability through agreements with clients, vendors, or landlords. This coverage extends to bodily injury, property damage, and even advertising and personal injury claims.
Additional Standard Features
What makes Chubb general liability stand out is the extras they include that other insurers might charge extra for:
-
Broad Form Property Damage: Goes beyond basic coverage to provide more comprehensive property damage protection.
-
Crisis Assistance Expenses: Included automatically with a $50,000 sub-limit at no extra cost. When a covered incident threatens your business reputation, this helps manage the PR fallout and protect your brand.
-
Product Withdrawal Expenses: Also included automatically with a $25,000 sub-limit. If you need to recall a defective product, this coverage helps with those unexpected expenses.
Want to dig deeper into what general liability covers? Check out our detailed guide on What Does General Liability Insurance Cover?
Optional Add-Ons to Chubb General Liability
Think of Chubb general liability as your foundation – but sometimes you need to build higher or wider. That’s where these valuable add-ons come in:
Umbrella/Excess Liability provides extra protection above your primary policy limits. It’s like having a second safety net when a major claim exceeds your standard coverage.
Cyber ERM (Enterprise Risk Management) has become essential in our digital world. This three-pronged approach combines risk transfer, loss prevention services, and post-incident response to address growing cyber threats.
Liquor Liability is a must-have if your business serves, sells, or manufactures alcoholic beverages. Standard policies exclude these risks, making this add-on crucial for restaurants, bars, and event venues.
Professional Errors & Omissions coverage protects against claims of financial harm due to your professional advice or services – essential for consultants, accountants, and service providers.
DigiTech ERM offers specialized protection for technology companies with unique digital exposures that standard policies don’t address.
Industry-Specific Tailoring
One size never fits all in business insurance. That’s why Chubb general liability can be customized for specific industries:
Life Sciences companies face unique challenges with complex products that interact with human health. Pharmaceutical manufacturers, biotech firms, and medical device companies benefit from Chubb’s specialized protection.
Technology businesses need coverage as innovative as they are. Software developers, IT consultants, and hardware manufacturers can get protection designed for digital-age risks.
Clean Energy providers like solar, wind, and alternative energy companies face emerging risks that traditional policies weren’t designed for. Chubb offers solutions custom to this growing sector.
Construction professionals benefit from expanded completed operations coverage and protection designed for the unique risks of building and renovation work.
Small Business BOP combines property and liability coverage in one convenient package for eligible small businesses with revenues under $30 million, with industry-specific improvements built right in.
Advantages, Appetite & Global Reach
When you choose Chubb general liability insurance, you’re not just buying a policy – you’re partnering with a financial powerhouse that stands ready to protect your business. With more than $200 billion in global assets, Chubb has the financial muscle to handle even the most substantial claims without breaking a sweat.
What really sets Chubb apart is their claims handling – consistently ranked #1 by risk managers in the Advisen Claims Satisfaction Survey. This isn’t just an empty accolade; it reflects real businesses getting real help when they need it most.
Behind the scenes, Chubb maintains an impressive network of over 400 risk engineers worldwide. These professionals don’t just wait for problems to happen – they work proactively with businesses to spot potential liability issues before they turn into costly claims. Think of them as your business’s personal safety inspectors, helping you avoid trouble rather than just responding to it.
Chubb’s underwriters aren’t generalists – they’re specialists who deeply understand specific industries. This means when you apply for coverage, you’re working with someone who truly gets the unique challenges your business faces. For more details about their approach to liability protection, check out Broadform Liability Insurance | Chubb.
Global Extension Benefits
Does your business operate internationally? Chubb general liability shines even brighter with its Global Extension option. Their Master Controlled Programs let you manage your worldwide insurance from one central point while still meeting local insurance requirements in each country where you operate.
The Difference-in-Conditions coverage is particularly valuable – it ensures your overseas operations receive the same quality protection as your domestic program by filling gaps in local policies. No more worrying about inconsistent coverage as your team crosses borders.
Navigating international insurance regulations can feel like trying to read a map in the dark. Chubb’s multinational compliance expertise lights the way, with local insurance professionals in 54 countries who understand the regulatory landscape. And if something does go wrong abroad, their seamless global claims network ensures you’ll receive the same high-quality service whether the incident happens in Miami or Milan.
Chubb Risk Appetite Snapshot
Chubb doesn’t take a one-size-fits-all approach to underwriting. They classify businesses into three severity levels to determine the right coverage approach:
Light Severity businesses include retail stores, offices, and apartments – places where liability exposures tend to be more predictable and less severe. If you run a small boutique or manage an office building, you’ll likely fall into this category.
Moderate Severity encompasses manufacturers, wholesalers, contractors, and service providers with medium-level exposures. These businesses face more complex risks but still operate within reasonably predictable parameters.
High Severity covers energy companies, heavy manufacturing operations, and other businesses where significant liability risks are part of daily operations. Even with these challenging exposures, Chubb’s substantial capacity allows them to offer meaningful protection.
This thoughtful classification system enables Chubb to cast a wide net across industries while maintaining disciplined underwriting standards – giving your business access to quality coverage custom to your specific risk profile.
Claims Scenarios, Exclusions & Risk Management
Let’s talk about what happens when things go wrong – because in business, they sometimes do. Understanding how Chubb general liability responds in real-world situations helps show why this coverage is so valuable for your business.
Picture this: a customer visits your retail store, catches their foot on uneven flooring, and suffers a broken hip requiring surgery. Your general liability policy would step in to cover their medical expenses, lost wages, and potential pain and suffering damages. This is the classic “trip-and-fall” scenario that many business owners worry about.
Or imagine your company distributes electronic accessories that malfunction and cause a fire in a customer’s home. Your Chubb general liability would cover the property damage and any resulting injuries to the homeowner or their family.
Business acquisitions create another interesting scenario. After purchasing another company, your business might face a lawsuit for defective products manufactured by the acquired company before you bought them. With the right coverage provisions, Chubb’s policy would protect you from these “successor liability” claims.
Chubb even provides coverage for liability arising from owned watercraft up to 15 meters in length – a valuable feature you won’t find in all general liability policies.
While Chubb general liability offers comprehensive protection, it’s important to understand what’s not covered. Standard policies typically exclude pollution claims, which require specialized environmental coverage. Claims related to asbestos and lead are generally excluded as well. Professional mistakes require separate errors and omissions coverage, while employment-related claims like discrimination or harassment need employment practices liability insurance. And for protection against claims stemming from management decisions, you’ll need directors and officers liability coverage.
Real-World Claim Response by Chubb General Liability
Chubb’s excellence in handling claims really shines through in real situations. When a vacuum vessel exploded at a European manufacturing plant, Chubb’s Global Extension coverage responded seamlessly, coordinating with local adjusters while maintaining consistent coverage standards across international borders.
In another case, a business faced allegations that their advertising materials infringed on a competitor’s copyright. Chubb general liability not only covered the defense costs but also connected the business with specialized intellectual property defense attorneys who knew exactly how to handle such complex claims.
After counterfeit cell phone accessories caused fires in multiple locations, one distributor faced numerous third-party claims. Chubb’s liability coverage responded to these claims while their risk engineers helped implement improved quality control measures to prevent similar incidents in the future – showing how Chubb goes beyond just paying claims to actually solving problems.
Risk Engineering & Prevention Tools
Chubb general liability isn’t just about responding after something goes wrong – it’s about preventing problems in the first place. Their risk engineering services include professional onsite surveys where experts evaluate your premises to identify and address potential hazards before they cause injuries.
Chubb also offers valuable training programs to help your employees understand and mitigate liability risks. Their data-driven analytics identify trends and focus prevention efforts where they’ll have the greatest impact. And because different industries face different challenges, Chubb provides custom risk management advice based on deep knowledge of sector-specific exposures.
These prevention tools are particularly valuable for Florida businesses, where unique environmental factors and a busy tourist economy create special liability considerations. At Florida All Risk Insurance, we help you leverage these Chubb resources to create a safer business environment while maintaining comprehensive protection.
How to Buy, Policy Forms & Ongoing Support
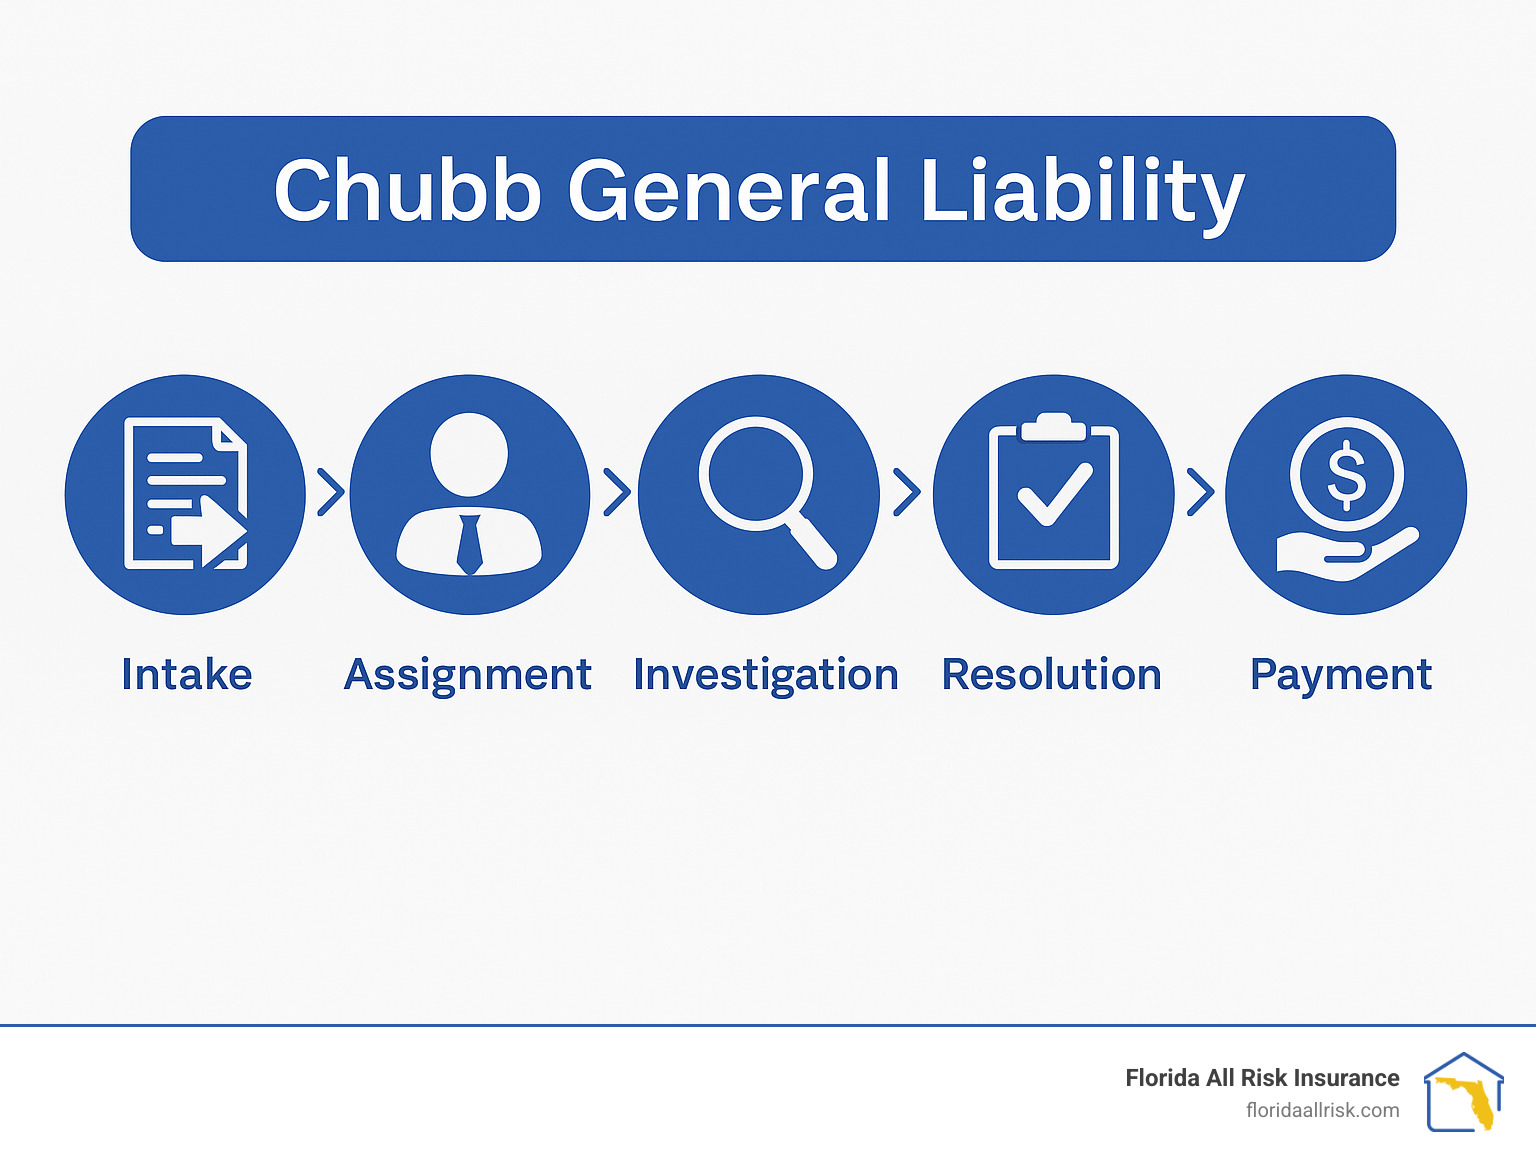
Getting Chubb general liability insurance is easier than you might think. As someone who’s helped hundreds of Florida businesses find the right protection, I can walk you through the straightforward process:
First, we’ll sit down for a friendly consultation to understand your business operations and unique exposures. No two businesses are alike, and this personalized approach ensures you get exactly the coverage you need—nothing more, nothing less.
After our chat, you’ll complete an application with details about your business operations, revenue, locations, and other key information. Don’t worry—we’re here to help with any questions along the way! Chubb’s underwriters will then review your application (they might ask for a bit more information to get the full picture of your business).
Once the underwriting team has what they need, you’ll receive a detailed quote outlining your coverage options, limits, and premium. When you’re ready to move forward, we’ll bind the coverage and get your policy documents issued promptly.
Occurrence vs. Claims-Made Policy
One important decision you’ll need to make is whether to choose an occurrence or claims-made policy. Here’s a simple breakdown of the differences:
| Feature | Occurrence Policy | Claims-Made Policy |
|---|---|---|
| Coverage Trigger | When the injury or damage occurs | When the claim is made and reported |
| Reporting Window | Any time after the policy period | During the policy period or extended reporting period |
| Long-Term Protection | Covers claims made years later for incidents during the policy period | Requires continuous coverage or tail coverage |
| Premium Stability | Generally stable premiums | Premiums may increase as exposure base grows |
| Best For | Businesses with stable operations | Businesses with changing exposures or needing premium flexibility |
For smaller businesses with revenue up to $30 million, Chubb offers an excellent Business Owner’s Policy (BOP) that combines Chubb general liability with property coverage and additional improvements. This package solution is available for over 500 business classes and provides streamlined protection at a competitive price.
Ready to get started? You can begin the quote process by visiting General Liability Insurance | Get a Quote or—even better—give us a call at Florida All Risk Insurance. We’ll make the process painless!
Wondering about costs? Check out our helpful article on General Liability Insurance Cost for more information about what factors influence your premium.
Support for Agents & Clients
The relationship doesn’t end once your Chubb general liability policy is in place. In fact, that’s when some of the best benefits begin!
Chubb provides ongoing support through comprehensive training resources that help you understand your coverage and implement effective risk management strategies. Their dedicated claims professionals specialize in specific industries and claim types, ensuring you work with adjusters who truly understand your business when you need them most.
With 48 local branch offices across North America, you’ll always have access to personalized service. And for those middle-of-the-night concerns or weekend questions, Chubb’s 24/7 portal gives you online access to policy management tools, claims reporting capabilities, and valuable risk management resources.
At Florida All Risk Insurance, we pride ourselves on being your advocate throughout the entire insurance journey. We’ll help you steer the application process, explain coverage options in plain English, and be there to answer questions whenever they arise. Our goal is to make insurance simple, so you can focus on what you do best—running your business.
Frequently Asked Questions about Chubb General Liability
What businesses qualify for Chubb’s Business Owner’s Policy?
You might be wondering if your small business can benefit from Chubb’s specialized Business Owner’s Policy (BOP). The good news is that Chubb has made this comprehensive coverage available to a wide range of small businesses with annual revenue up to $30 million.
Whether you run a cozy retail shop, a professional office, a service-based business, manage apartments or condominiums, or even operate a light manufacturing facility, you could qualify for this protection. With over 500 eligible business classes, Chubb has designed this package with small business needs in mind.
What makes the BOP particularly valuable is how it bundles property and chubb general liability coverage together, then improves it with modern protections like privacy and data breach coverage, employment practices liability, and even equipment breakdown protection. It’s essentially a one-stop solution for small business insurance needs.
How much general liability limit should I carry?
This is perhaps the most common question we hear from business owners, and for good reason – having too little coverage can leave you vulnerable, while excessive limits might mean you’re paying for protection you don’t need.
Many small businesses start with what’s often called a 1/2 policy: $1 million per occurrence and $2 million aggregate limit. But in reality, the right amount depends on your specific situation. We consider factors like:
- Your industry’s typical liability exposures
- Your company’s annual revenue
- How many locations you operate
- What your contracts with clients or landlords require
The beauty of chubb general liability is its flexibility – with capacity up to $100 million, Chubb can structure your coverage with higher limits for your most critical exposures or provide blanket limits across all coverages. At Florida All Risk Insurance, we take the time to understand your business and recommend limits that make sense for your unique situation.
How does Chubb handle multinational claims?
If your business operates internationally, you’ll appreciate Chubb’s sophisticated approach to global claims. When an incident occurs overseas, you don’t have to steer unfamiliar legal systems alone.
Chubb general liability with Global Extension activates local claims teams who understand regional regulations and practices. Think of it as having a local expert in your corner, wherever the claim occurs. This approach ensures you receive consistent, high-quality claims service worldwide.
What’s particularly valuable is the difference-in-conditions protection, which addresses gaps between local policies and your home country coverage. This means you won’t face surprising coverage shortfalls just because an incident happened abroad.
The coordination between local and home country claims teams creates a seamless experience, with clear communication throughout the process. For businesses with international operations, this global capability represents one of the strongest advantages of choosing Chubb as your liability insurance partner.
Conclusion
When it comes to protecting your business from unexpected liability claims, Chubb general liability insurance delivers peace of mind that’s hard to match. I’ve seen how the right coverage can make all the difference when a customer slips on a wet floor or when a product unexpectedly causes damage.
What makes Chubb stand out isn’t just their impressive financial strength (though $200 billion in assets certainly helps you sleep better at night). It’s their thoughtful approach to coverage that includes those extras that many standard policies charge extra for – like crisis assistance when your reputation is on the line, or product withdrawal coverage when you need to pull a problematic item from the market.
For Florida businesses with international aspirations or operations, Chubb’s Global Extension is a game-changer. It ensures that whether an incident happens in Tampa or Tokyo, you’ll receive the same level of protection and service. Their presence in 54 countries means you’re never far from expert assistance when you need it most.
Here at Florida All Risk Insurance, we’re proud to offer Chubb general liability solutions to our clients throughout the Sunshine State. As your neighbors in St. Petersburg, we understand the unique challenges Florida businesses face – from seasonal tourist influxes to hurricane-related disruptions that can create unexpected liability scenarios.
Being an independent agency gives us the flexibility to tailor your coverage precisely to your needs. We’re not here to sell you a one-size-fits-all policy; we’re here to build a protection plan that addresses your specific industry risks and growth goals.
Don’t wait for a lawsuit to find gaps in your liability coverage. Let’s have a conversation about how Chubb general liability insurance can form the foundation of your business protection strategy. Our team is ready to guide you through the options and find the right fit for your company.
For more information about our comprehensive general liability options, visit our coverage page. Your business has worked too hard to be left vulnerable – let’s protect what you’ve built together.

