

Why Car Insurance Costs More in St. Petersburg Than You Think
Cheap car insurance St Petersburg drivers need isn’t just about finding the lowest premium—it’s about getting real value without sacrificing essential coverage. If you’re looking for affordable auto insurance in the Sunshine City, here’s what you need to know:
Quick Answer for St. Petersburg Drivers:
• Average full coverage: $294/month ($22 more than Florida average)
• Cheapest minimum coverage: GEICO at $43/month (60% below city average)
• Best full coverage deal: State Farm at $182/month (38% below city average)
• Liability-only average: $106/month or $1,272/year
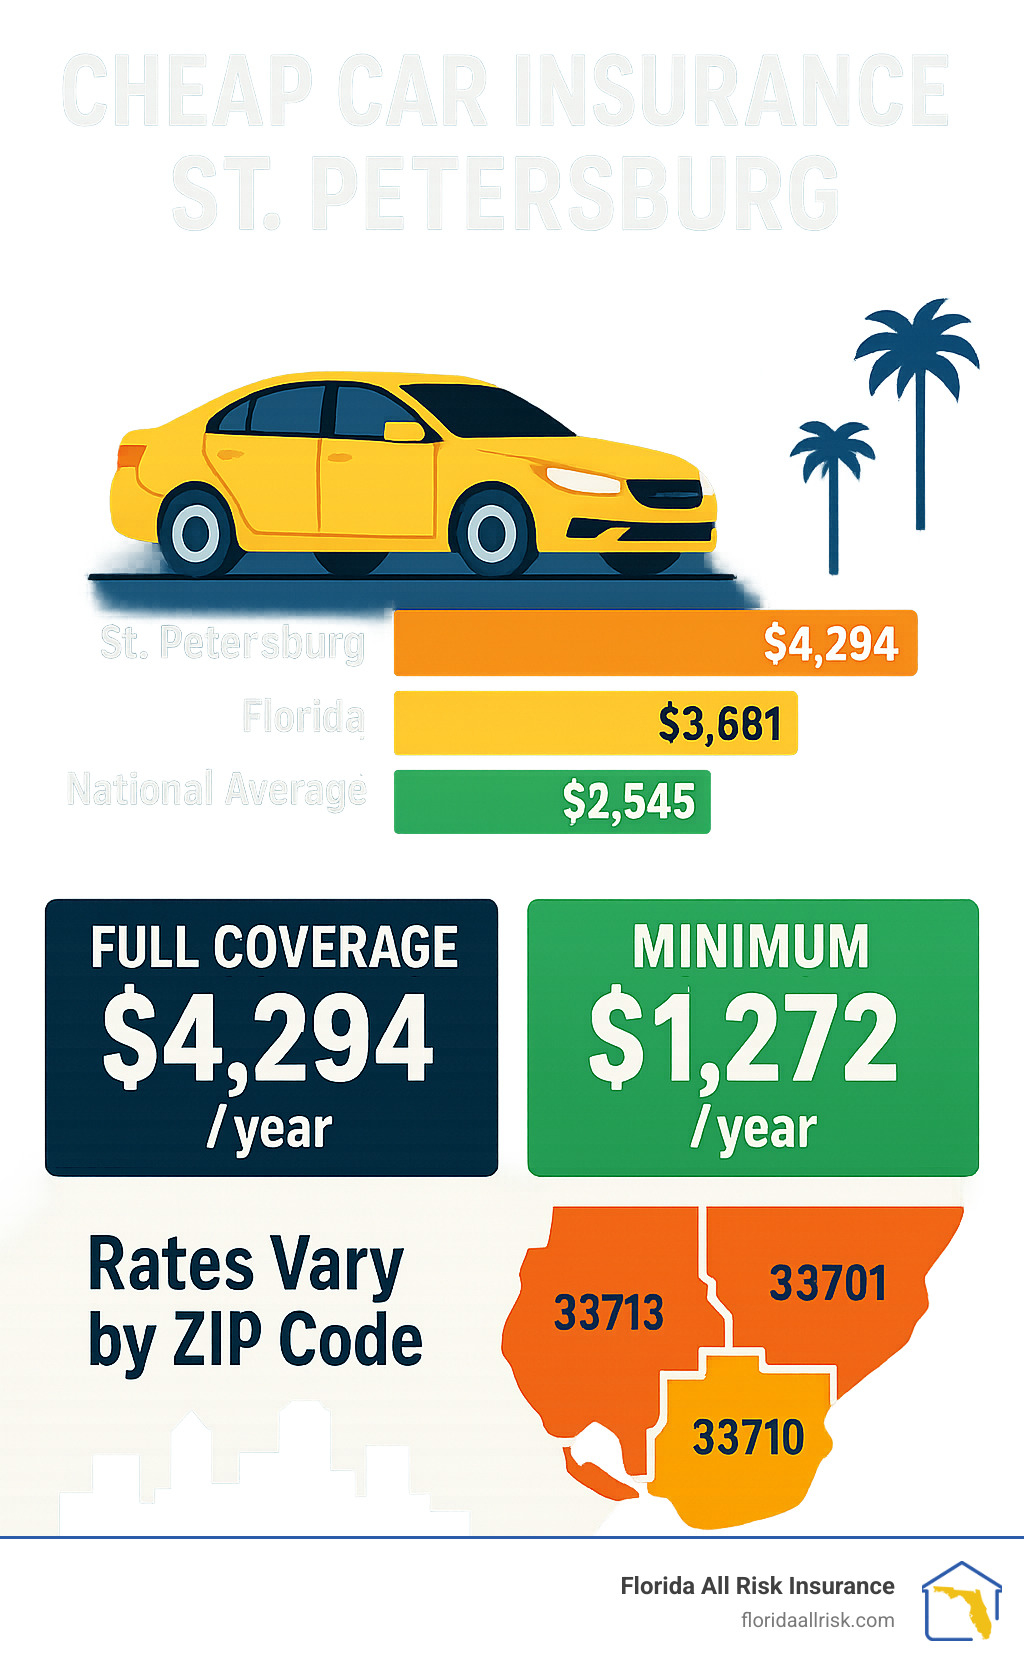
St. Petersburg drivers face unique challenges when shopping for auto insurance. The city’s $4,294 annual average for full coverage sits well above Florida’s $3,681 state average. But here’s the good news: smart shoppers who compare quotes and work with experienced agents can cut their premiums significantly.
Weather patterns, traffic density, and local accident rates all push St. Pete premiums higher than many Florida cities. Teen drivers feel this impact most, paying an average of $1,083 monthly for full coverage. Even a single speeding ticket bumps the average rate to $347 per month—an 18% increase that sticks around for years.
I’m Jason Miller, a second-generation insurance professional with over 20 years of experience helping Florida drivers secure affordable coverage. My team at Florida All Risk Insurance has guided thousands of St. Petersburg residents through the process of finding cheap car insurance St Petersburg families can actually afford while maintaining proper protection.
Similar topics to Cheap car insurance St Petersburg:
– Florida car insurance discounts
– Temporary car insurance Florida
– Florida classic car insurance
Cheap Car Insurance St Petersburg: What Drivers Really Pay
Let’s cut straight to what matters most—the actual dollars coming out of your pocket each month. When I review policies for St. Petersburg drivers, I consistently see full coverage averaging $294 monthly and minimum liability running $106 monthly. These numbers put our city noticeably above both Florida and national averages, which is why shopping smart isn’t just helpful—it’s essential.
Here’s what might surprise you: a 35-year-old driver with good credit and a clean record can often secure coverage for around $2,667 annually with the right carrier. The catch? Many drivers end up paying much more because they don’t know how coverage choices, age, and driving history impact their rates.
| Coverage Type | Monthly Cost | Annual Cost |
|---|---|---|
| Minimum Liability | $106 | $1,272 |
| Full Coverage | $294 | $3,528 |
Average Premiums by Coverage Level
The gap between liability-only and full coverage tells an important story about value versus risk. At $106 monthly, liability-only coverage meets Florida’s legal requirements and keeps you on the road legally. But here’s the reality check—if your car gets damaged in a storm, stolen, or totaled in an accident, you’re covering those costs entirely out of pocket.
Full coverage at $294 monthly represents a significant jump, but it protects your vehicle investment. When you’re driving through St. Pete’s afternoon thunderstorms or navigating busy intersections during tourist season, that comprehensive and collision coverage becomes invaluable.
One money-saving tip I always share: pay annually instead of monthly. Most carriers offer 5-10% discounts for upfront payment. On a $294 monthly policy, that annual payment could save you $176-$353 per year—enough to cover a nice dinner out or put toward your next vacation.
Cheap Car Insurance St Petersburg by Neighborhood & ZIP
Good news for cheap car insurance St Petersburg shoppers—where you live in the city doesn’t dramatically impact your rates. The variation across neighborhoods typically spans only about $16 monthly, which is much smaller than most drivers expect.
ZIP code 33713 shows some of the most affordable rates, with minimum liability averaging $87 monthly and full coverage at $258 monthly. Areas like 33701 and 33710 show similar patterns with only slight variations based on local traffic patterns and accident statistics.
This relatively small geographic spread means your driving record and credit score carry much more weight than your specific address. Whether you’re in downtown, the beaches, or residential neighborhoods, competitive rates are available with the right approach.
Cheap Car Insurance St Petersburg for Teens & Seniors
Age creates the most dramatic rate differences in St. Petersburg. Teen drivers aged 16-19 face an average of $1,083 monthly for full coverage—a number that can shock parents but reflects real statistical risk. Even liability-only coverage runs $367 monthly for teens.
The silver lining? Good student discounts can provide substantial relief for teens maintaining B averages or better. Defensive driving courses offer additional savings while teaching valuable skills for handling St. Pete’s unique driving challenges, from tourist traffic to sudden weather changes.
Drivers 60 and older typically see their rates level off and often decrease. By age 35, most drivers reach their optimal rate plateau, making this an ideal time to compare policies and lock in competitive coverage. Senior drivers often qualify for mature driver course discounts and low-mileage programs that reflect their typically safer driving patterns.
Even one speeding ticket increases premiums by about 18%—making safe driving habits your most powerful tool for keeping cheap car insurance St Petersburg rates manageable regardless of your age.
Factors That Drive Rates Up—or Down—in the Burg
Living in St. Petersburg means enjoying 361 days of sunshine annually, but all that beautiful weather also means more time on the road—and more opportunities for accidents. As a coastal Florida city, St. Pete has its own unique personality when it comes to insurance rates, and understanding these local factors can help you find truly cheap car insurance St Petersburg drivers deserve.
The city’s commitment to environmental projects, like the North Shore Park Seagrass Bank Mitigation Project, shows our community’s dedication to sustainability. However, ongoing construction and infrastructure improvements can temporarily affect traffic patterns, which insurers factor into their risk calculations.
Your credit score stands out as the single most powerful factor you can control. Here’s a number that might shock you: drivers with poor credit in St. Petersburg pay 93% more for full coverage compared to those with good credit. That’s nearly double the cost for the same exact coverage! Improving your credit score from poor to good could literally cut your insurance bill in half.
The type of vehicle you drive makes a huge difference too. That sleek sports car might turn heads on Central Avenue, but it’ll also turn your insurance premium upward. Vehicles with strong safety ratings and lower repair costs enjoy reduced rates, while high-theft models and luxury cars command premium prices.
Miles driven annually affects your risk profile significantly. If you’re working from home or live close to everything you need, those reduced miles can translate to meaningful discounts. Many insurers offer low-mileage programs that reward drivers who stay under certain annual thresholds.
St. Petersburg’s coastal location brings both beauty and risk. Our exposure to severe weather events like hurricanes and tropical storms factors into rate calculations. Meanwhile, traffic density on major routes like I-275 and the Howard Frankland Bridge contributes to accident frequency that insurers carefully track.
Driving Record & Violations
Your driving record tells your insurance story better than anything else. A clean record—free of accidents, tickets, and violations—opens the door to the best available rates. It’s like having a golden ticket in the insurance world.
Even seemingly minor infractions pack a financial punch. Drivers with a single speeding ticket see their average full coverage premium jump to $347 per month—that’s an 18% increase that sticks around for three to five years. One moment of heavy foot can cost you hundreds of dollars annually.
At-fault accidents typically result in even steeper increases, with some drivers seeing rate hikes of 46% or more. The financial impact extends far beyond the immediate repair costs, affecting your premiums for years to come.
SR-22 and FR-44 filings represent the most serious category of violations. Required after major infractions like DUI convictions, these certificates of financial responsibility mandate higher minimum coverage limits and often limit your choice of carriers. While specialized programs and high-risk insurers can still provide coverage, expect to pay premium rates until you can demonstrate improved driving behavior over time.
Personal Factors You Control
The good news? Several major factors that impact your rates remain completely within your control. Credit management tops this list—maintaining good credit can cut your premiums nearly in half compared to poor credit scores. Simple steps like paying bills on time, keeping credit utilization low, and monitoring your credit report for errors can save you thousands annually.
Bundling your auto insurance with other policies creates immediate savings opportunities. Multi-policy discounts typically range from 5-25%, and at Florida All Risk Insurance, we help clients identify the most beneficial bundling combinations across our full range of coverage options. Your homeowners or renters insurance might just be the key to open uping significant auto insurance savings.
Deductible choice represents another powerful cost management tool. Higher deductibles reduce your monthly premiums but increase your out-of-pocket costs when filing claims. We recommend choosing the highest deductible you can comfortably afford in an emergency—it’s like self-insuring the smaller stuff while protecting against major losses.
For even more money-saving strategies, explore our comprehensive guide to Best Car Insurance Discounts. Every discount you qualify for puts money back in your pocket while maintaining the protection you need on St. Pete’s roads.
Meeting – and Exceeding – Florida’s Minimum Requirements
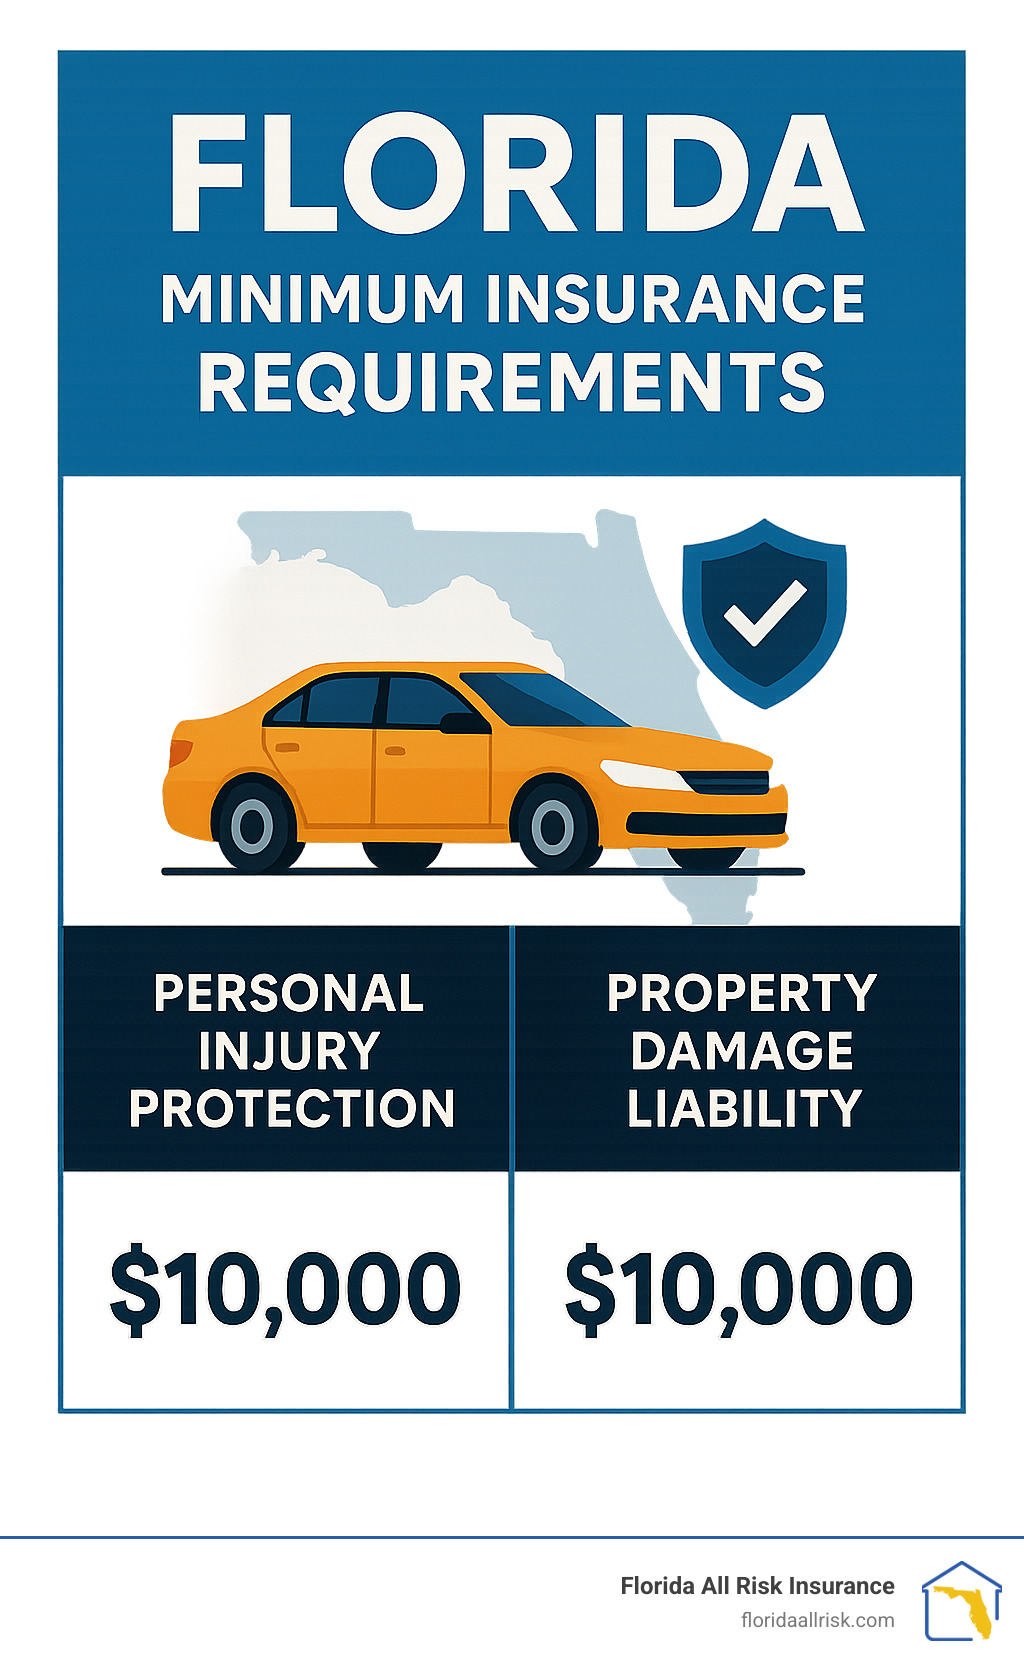
Florida keeps things simple when it comes to mandatory auto insurance, but “simple” doesn’t always mean “sufficient.” Every driver in the Sunshine State must carry Personal Injury Protection (PIP) coverage of at least $10,000 and Property Damage Liability (PDL) of at least $10,000. What makes Florida unique is that we’re one of only two states that doesn’t require Bodily Injury liability coverage—though that doesn’t mean you should skip it.
Here’s the reality check: $10,000 in PIP coverage might sound reasonable until you consider that a single emergency room visit can easily exceed that amount. The $10,000 PDL minimum won’t even cover the cost of most new vehicles, let alone luxury cars or trucks that are increasingly common on St. Petersburg roads.
PIP coverage helps pay your medical expenses regardless of who caused the accident, which sounds great in theory. But when you’re dealing with serious injuries from a crash on I-275 or the Howard Frankland Bridge, that $10,000 disappears quickly. PDL coverage handles damage you cause to other people’s property—their cars, fences, or buildings—but modern vehicles can easily cost $30,000 to $80,000 or more.
Smart drivers in St. Petersburg add optional Bodily Injury liability to protect against lawsuits when they injure other people. Comprehensive and collision coverage protect your own vehicle from theft, vandalism, weather damage, and crash repairs. Uninsured motorist protection becomes your safety net when other drivers lack adequate coverage—which happens more often than you’d think.
For detailed information about all your coverage options in our area, check out our comprehensive guide to Car Insurance in St Petersburg.
Penalties for Driving Without Insurance in St Pete
Getting caught without insurance in Florida isn’t just expensive—it’s financially devastating. The state takes uninsured driving seriously, and the penalties escalate faster than you might expect.
First-time offenders face a $150 reinstatement fee and automatic license suspension for up to three years. Yes, you read that correctly—three years. Your license stays suspended until you provide proof of insurance and pay that reinstatement fee, which means no legal driving to work, school, or anywhere else.
Second offenses within three years bump the reinstatement fee to $250 while maintaining that brutal three-year suspension period. Third offenses carry a $500 reinstatement fee and the same lengthy suspension. These penalties don’t include the impound fees if your car gets towed, court costs, or the headache of dealing with the legal system.
The financial pain doesn’t end when you finally get your license back. Insurance companies view coverage lapses as red flags, often doubling or tripling your premiums when you try to get back on the road. Some insurers won’t touch drivers with recent lapses, forcing you into high-risk markets with limited options and sky-high rates.
Coverage Recommendations Beyond the Minimum
While Florida’s minimum requirements keep you legal, they won’t keep you financially safe. Full coverage that includes comprehensive and collision protection makes sense for any vehicle worth more than a few thousand dollars—which covers most cars on the road today.
Gap insurance becomes essential if you’re financing or leasing your vehicle. This coverage pays the difference between your car’s actual cash value and your remaining loan balance if the vehicle gets totaled. Without gap coverage, you could find yourself paying $5,000 or more on a car that’s sitting in a junkyard.
Glass waiver coverage eliminates deductibles for windshield repairs and replacements. In Florida, where road debris flies constantly and severe weather strikes regularly, this coverage pays for itself quickly. A single windshield replacement can cost $300 to $800 or more, depending on your vehicle.
Roadside assistance provides practical help when your car breaks down, your battery dies, or you get a flat tire. For St. Petersburg drivers who commute across bridges or travel frequently around the Tampa Bay area, this coverage offers peace of mind and real value.
Uninsured and underinsured motorist coverage protects you when other drivers lack adequate insurance. Since many Florida drivers carry only the bare minimum coverage, this protection becomes increasingly important. When someone with $10,000 in coverage causes $50,000 in damages, this coverage fills the gap that could otherwise come out of your pocket.
Proven Ways to Score the Lowest Quotes
Getting cheap car insurance St Petersburg drivers can trust starts with shopping smart. The biggest mistake I see drivers make? Getting just one quote and calling it done. Insurance rates vary wildly between companies—sometimes by hundreds of dollars for identical coverage.
I always tell my clients to get quotes from at least three different carriers. What makes one company expensive for you might make another company your best deal. Your age, driving record, credit score, and even your ZIP code all factor into each insurer’s unique pricing formula.
Working with an independent agent like our team at Florida All Risk Insurance gives you a major advantage here. Instead of calling multiple companies yourself, we can pull quotes from numerous carriers in minutes. We’ll show you the real differences between policies—not just the price, but what you’re actually getting for your money.
Telematics programs offer another smart way to cut costs if you’re a safe driver. These usage-based insurance programs track how you actually drive through a smartphone app or small device in your car. They monitor things like hard braking, rapid acceleration, and nighttime driving.
Good drivers typically save 10-30% through telematics programs. The data doesn’t lie—if you’re truly a safe driver, these programs reward you with lower rates. Some drivers worry about privacy, but the potential savings often outweigh those concerns.
Don’t forget about regular policy reviews. Your life changes, and your insurance needs change with it. Got married? Bought a house? Turned 25? Each of these milestones could open up new discounts you didn’t qualify for before.
We recommend reviewing your policy at least once a year. Sometimes you’re paying for coverage you no longer need, or missing discounts that could save you serious money. For personalized quotes that take all these factors into account, check out our St Petersburg Auto Insurance Quotes service.
Discounts Every Driver Should Request
Here’s something that surprises many drivers: insurance companies won’t automatically apply every discount you qualify for. You need to ask for them specifically. It’s like leaving money on the table if you don’t.
The multi-car discount tops my list of must-have savings. If you have more than one vehicle in your household, insuring them together typically saves 10-25% per vehicle. Even if the cars belong to different family members, you can often combine them under one policy for significant savings.
Homeowner discounts apply even if you don’t bundle your home and auto insurance with the same company. Insurance companies view homeowners as more stable and responsible, which translates to lower auto rates. If you own your home, make sure every insurer knows about it.
Many drivers overlook employer group discounts. Your company might have negotiated special rates with certain insurers. Professional organizations, alumni associations, and even some credit unions offer group insurance discounts. It takes just a quick call to your HR department to find out what’s available.
Senior discounts usually kick in around age 50 or 55. These recognize that mature drivers tend to have fewer accidents and traffic violations. If you’re approaching these age milestones, ask about senior savings programs.
Setting up auto-pay might seem small, but it typically saves 3-5% annually. Plus, you’ll never risk a coverage lapse from a missed payment. That peace of mind alone makes auto-pay worth setting up.
Military discounts honor current and former service members with reduced rates and special programs. If you’ve served our country, make sure your insurance company knows about it.
High-Risk & SR-22 Strategies
Being labeled “high-risk” doesn’t mean you’re stuck with sky-high rates forever. I’ve helped plenty of drivers in challenging situations find affordable coverage while they rebuild their driving records.
Non-owner policies work great for drivers who need insurance but don’t own a car. Maybe you’re between vehicles, or you primarily use public transportation but occasionally borrow or rent cars. These policies cost much less than standard auto insurance while keeping your coverage continuous.
Driver training courses serve double duty—they make you a safer driver and often qualify you for insurance discounts. Many insurers reduce rates for completing defensive driving or traffic safety courses, especially if you have recent violations on your record.
Raising your deductible provides immediate premium relief. Yes, you’ll pay more out-of-pocket if you file a claim, but sometimes that trade-off makes sense. Choose the highest deductible you can comfortably handle in an emergency.
Monthly payment plans help manage cash flow when you’re facing higher premiums. While paying annually usually offers discounts, monthly payments ensure you can maintain continuous coverage without a large upfront cost. Continuous coverage is crucial for eventually getting back to standard rates.
The key is patience and persistence. High-risk status isn’t permanent. Keep your record clean, maintain continuous coverage, and work with an experienced agent who understands the high-risk market. Your rates will improve over time.
Frequently Asked Questions about Cheap Car Insurance in St Petersburg
What is the average cost of car insurance in St Petersburg?
If you’re wondering what you should expect to pay for car insurance in the Sunshine City, the numbers might surprise you. Cheap car insurance St Petersburg drivers are looking for typically runs $294 per month for full coverage and $106 per month for liability-only coverage. That works out to $3,528 annually for comprehensive protection and $1,272 for the bare minimum.
Here’s the reality check: these rates sit higher than both Florida’s state average of $3,681 annually and the national average of $2,016. Why? St. Petersburg’s coastal location brings weather risks, our busy roads create more accident opportunities, and let’s face it—everyone wants to live here, which means more traffic.
But before you panic about these averages, they’re just that—averages. Smart shoppers who take the time to compare quotes and work with experienced local agents often find rates significantly below these numbers. The key is knowing where to look and what factors work in your favor.
Who offers the cheapest quotes for my situation?
This is the million-dollar question, and honestly, there’s no one-size-fits-all answer. What makes car insurance pricing tricky is that the cheapest carrier for your neighbor might be the most expensive for you. It all depends on how each company weighs factors like your age, driving record, credit score, and even your ZIP code.
That said, our research shows some encouraging numbers. For minimum coverage, we’ve seen rates as low as $43 per month—that’s a whopping 60% savings compared to the city average. For full coverage, competitive rates start around $182 per month, which represents 38% below what most drivers pay.
The secret sauce? Getting personalized quotes from multiple carriers. Each insurance company uses different formulas to calculate risk, which means you could save hundreds of dollars simply by finding the right match for your specific situation.
How does St Pete compare to Tampa, Orlando & Miami rates?
St. Petersburg sits in a sweet spot when it comes to Florida car insurance costs. Our average full coverage rate of $4,294 annually puts us right in the middle of the pack compared to other major Florida cities.
While we typically pay more than smaller inland cities (thanks to our coastal location and urban traffic), we’re generally more affordable than high-cost areas like Miami. Tampa rates run fairly similar to ours, given our shared geography and traffic patterns. Orlando’s rates can vary depending on which part of the metro area you’re comparing.
The bottom line? St. Petersburg’s competitive insurance market helps keep rates reasonable for a major metropolitan area. Our coastal lifestyle comes with some premium costs, but the trade-off of living in paradise makes it worthwhile for most of us. Plus, with the right approach to shopping for coverage, you can find rates that won’t break the bank while protecting what matters most.
Conclusion
The journey to finding cheap car insurance St Petersburg drivers can actually afford doesn’t have to feel overwhelming. You now have the roadmap to steer this process successfully—from understanding why St. Pete rates average $294 monthly for full coverage to finding how the right strategies can cut your costs significantly.
The numbers tell a clear story. While St. Petersburg’s insurance costs sit above state averages, smart drivers who maintain good credit, shop multiple carriers, and maximize available discounts regularly save hundreds or even thousands annually. Whether you’re a teen driver facing those steep $1,083 monthly rates or a senior looking to optimize your coverage, the tools for success remain the same.
Compliance with Florida’s requirements forms your foundation, but don’t stop at the $10,000 PIP and $10,000 PDL minimums. Full coverage protects your investment and provides peace of mind when navigating everything from downtown traffic to storm season. The difference between liability-only and comprehensive protection often matters most when you need it most.
Working with an experienced independent agent changes the entire experience. Instead of calling company after company, you get access to multiple carriers through one conversation. At Florida All Risk Insurance, we’ve spent over two decades helping St. Petersburg families find that sweet spot between affordable premiums and solid protection.
Your next step is simple: get those personalized quotes. Rates vary dramatically between carriers for identical coverage, and what works best for your neighbor might not be optimal for your situation. We make this process straightforward by comparing options across our network of carriers and identifying opportunities you might miss on your own.
The road ahead looks brighter when you’re properly insured at rates that fit your budget. For comprehensive information about all your auto coverage options, visit our auto insurance page and find how Florida All Risk Insurance helps you lock in the best rate today. Let’s get you back on St. Pete’s roads with confidence and coverage you can count on.

