

Cheap Business Insurance 2025: Master Savings!
Why Finding Cheap Business Insurance is Essential for Florida Businesses
Cheap business insurance doesn’t mean cutting corners on protection—it means finding the right coverage at the best possible price. For Florida business owners, this balance is crucial given the state’s unique risks and competitive market.
Quick Answer for Cheap Business Insurance:
- General Liability: Can start as low as $17/month.
- Business Owner’s Policy (BOP): Averages around $141/month (combines liability + property).
- Professional Liability: Averages around $62/month for service-based businesses.
- Workers’ Compensation: Averages around $86/month when employees are hired.
The reality is stark: a simple slip-and-fall accident can result in lawsuits exceeding $100,000. Yet many Florida business owners operate without adequate protection, believing insurance is too expensive. This misconception can be devastating, as a single claim can bankrupt an uninsured business overnight.
The good news is that protection is more affordable than most realize. The key lies in understanding your specific risks, comparing options strategically, and working with professionals who know Florida’s insurance landscape.
I’m Jason Miller, a second-generation insurance professional with over 20 years of experience helping Florida businesses find cheap business insurance solutions that don’t compromise on quality. Through Florida All Risk Insurance, I’ve guided thousands of business owners in securing comprehensive protection that fits their budgets and operational needs.
Relevant articles related to cheap business insurance:
- business insurance for small businesses
- buy business insurance online
- what does general liability insurance cover
Understanding the Foundation: What is Business Insurance and Why is it Crucial?
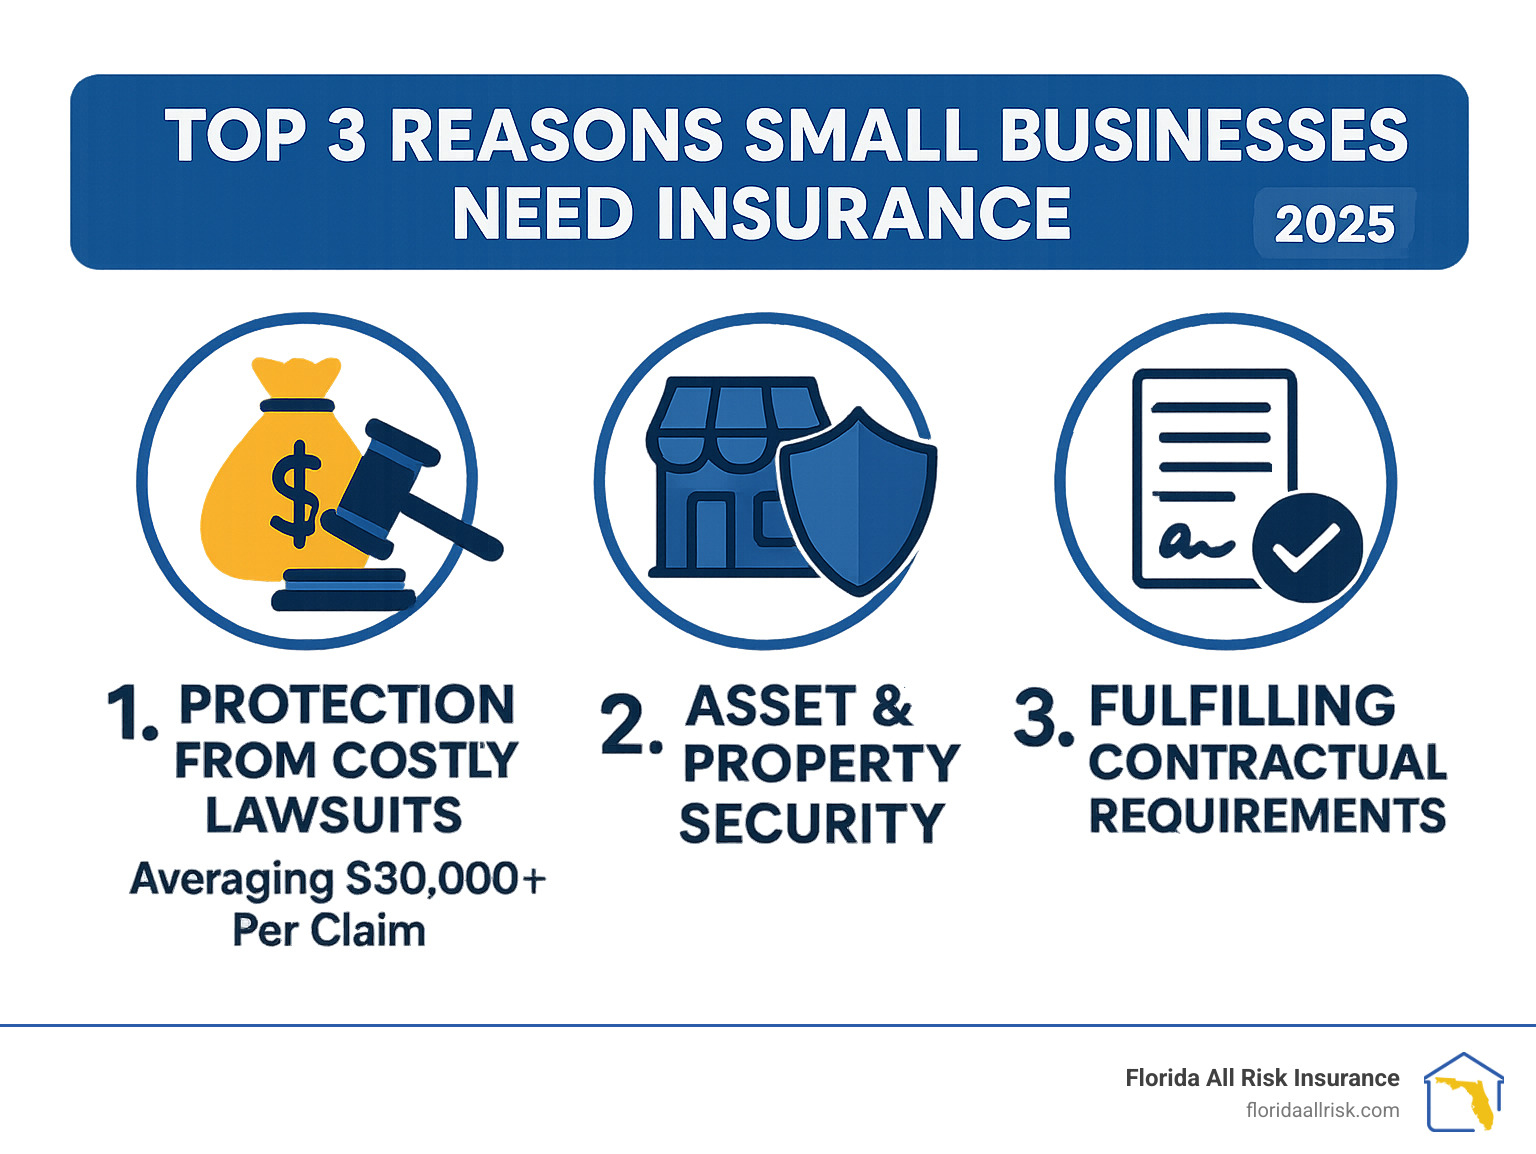
Think of business insurance as your financial safety net. It’s a collection of different coverage types, each designed to protect your business from specific risks that could otherwise be catastrophic. It transforms unpredictable, massive expenses into manageable, predictable monthly premiums. When a customer slips, a fire damages your office, or a client claims your professional advice cost them money, insurance steps in to handle the financial fallout.
Beyond protecting your assets, business insurance often fulfills legal requirements. If you have employees, workers’ compensation is the law. Many clients and landlords also require proof of general liability coverage. Having proper insurance builds client trust by demonstrating professionalism and ensures business continuity, allowing you to focus on growth instead of worrying about what-if scenarios.
Who Needs Business Insurance?
If you’re running a business, you likely need insurance. This applies to:
- Small business owners: Whether you run a café, retail shop, or service business, you face daily risks of customer injury or property damage.
- Freelancers and consultants: Even if you work from home, you can be sued for errors in your work or damage client property during a site visit.
- Contractors and tradespeople: Job sites are inherently risky. Insurance covers accidents, stolen tools, and injuries.
- Home-based businesses: Your homeowner’s policy rarely covers business-related incidents. Our guide on Safeguard Your Home-Based Business explains how to fill these gaps.
- LLCs and sole proprietors: An LLC protects your personal assets from business debts, but your business assets remain vulnerable without insurance. Sole proprietors face unlimited personal liability, making coverage critical.
- Startups: Skipping insurance to save money early on is a major risk. Protection is most critical when you’re building something valuable from the ground up.
The High Cost of Being Uninsured
Operating without insurance is a financial gamble. A single uninsured incident can have devastating consequences.
- Bodily injury costs: A customer injury can lead to a lawsuit demanding payment for medical bills, lost wages, and pain and suffering, easily exceeding $50,000.
- Property damage expenses: Accidentally damaging a client’s property, from a luxury car to expensive equipment, can result in claims that cripple a small business.
- Legal defense fees: Defending your business in court—even against a frivolous lawsuit—can cost tens of thousands of dollars in attorney fees and court costs.
- Business closure: For most small businesses, a single large uninsured claim is an existential threat that can lead to bankruptcy.
The irony is that cheap business insurance options exist that would have prevented these scenarios. With general liability insurance starting as low as $17 per month, there’s no reason to operate without this essential protection.
Decoding Your Options: A Guide to Common Business Insurance Policies
Finding cheap business insurance that actually protects you requires understanding that there’s no one-size-fits-all solution. The best approach is to start with fundamental coverages and then add specialized protection as needed. This strategy ensures you are properly protected while keeping premiums reasonable. You can explore our full range of Business Insurance Products to see how we tailor coverage for different industries.
Let’s walk through the most common types of business insurance.
General Liability Insurance (GLI)
GLI is the foundation of most business insurance plans. It covers everyday risks that come with normal business operations, protecting you when accidents happen to people who aren’t your employees. GLI typically covers:
- Bodily injury: A customer slipping on a wet floor in your store.
- Property damage: Your business operations accidentally damaging someone else’s property.
- Advertising injury: Claims of libel, slander, or copyright infringement in your marketing.
GLI also covers your legal defense costs, even if a lawsuit is frivolous. For more details, see our page on Commercial General Liability Insurance.
Professional Liability Insurance (E&O)
Also called Errors and Omissions (E&O) insurance, this policy protects against claims related to the quality of your professional services. If your business gives advice or provides expertise, E&O is crucial. It’s essential for consultants, accountants, real estate agents, and financial advisors. For example, if a consultant’s advice leads to a client’s financial loss, E&O insurance would cover the legal defense and any resulting settlement. Learn more on our Business Liability Insurance page.
The Key Difference: General Liability vs. Professional Liability
The distinction is simple:
- General Liability covers physical risks: bodily injury, property damage, and advertising harm.
- Professional Liability covers financial losses resulting from professional mistakes, negligence, or failure to perform services as expected.
A customer slipping in your store is a General Liability claim. An accountant’s error causing tax penalties is a Professional Liability claim. Many businesses need both.
Business Owner’s Policy (BOP)
A Business Owner’s Policy (BOP) is a smart bundle that combines several essential coverages into one policy, often at a lower cost than buying them separately. A typical BOP includes:
- General Liability Insurance
- Commercial Property Insurance (protects your building, equipment, and inventory)
- Business Interruption Insurance (replaces lost income if you must temporarily close)
According to industry data, the average annual premium for a BOP is around $1,687, or about $141 per month. It’s often the most cost-effective way to get comprehensive protection. Find more details on our Insurance for Small Businesses page.
Other Essential Coverages to Consider
- Workers’ Compensation Insurance: Legally required in Florida if you have employees. It covers medical expenses and lost wages for work-related injuries. The average annual premium is around $1,032, or about $86 per month.
- Commercial Auto Insurance: Necessary if you use vehicles for business. Personal auto policies won’t cover business use.
- Cyber Liability Insurance: Increasingly vital for businesses that handle customer data or process online payments. It helps cover costs related to data breaches and cyberattacks.
- Commercial Property Insurance: Can be purchased as a standalone policy if you need more coverage than a BOP offers. See our page on Cheap Commercial Property Insurance for affordable options.
For comprehensive guidance on business insurance requirements, the U.S. Small Business Administration provides detailed information on what types of coverage different businesses typically need.
The Big Question: How Much Does Business Insurance Cost?
“How much will this cost?” is a common question, but there’s no single answer. Business insurance costs vary dramatically based on your business’s unique characteristics. The type of work you do, your location, the number of employees, and your claims history all play a role.

The good news is that cheap business insurance is attainable when you understand what influences pricing. For more details, visit our page on General Liability Insurance Cost.
Key Factors That Influence Your Premiums
Insurance companies use detailed risk assessments to set your premiums. Key factors include:
- Industry and Risk Level: A high-risk industry like construction will pay more than a low-risk home-based consulting business.
- Business Location: Florida’s unique risks, like hurricanes, affect pricing. Local claim rates and regulations also play a part.
- Employees and Payroll: More employees and a larger payroll increase workers’ compensation and liability premiums.
- Annual Revenue: Higher revenue often indicates greater exposure, which can influence policy pricing.
- Claims History: A history of frequent or costly claims will increase your premiums.
- Policy Limits and Deductibles: You have direct control here. Higher limits increase premiums, while higher deductibles lower them. We can help you determine How Much General Liability Insurance Do I Need?.
Average Cost Statistics: A General Benchmark
While every business is unique, these industry averages provide a useful baseline:
- General Liability Insurance: Many businesses pay around $42 per month on average, though some policies can start as low as $17 per month.
- Business Owner’s Policy (BOP): This bundle averages around $141 per month.
- Workers’ Compensation Insurance: Averages about $86 per month, but this varies significantly by industry.
- Professional Liability Insurance: Typically runs about $62 per month on average.
These are just averages. Your actual costs will depend on your specific business. Working with an independent agency like ours allows us to shop multiple carriers to find the best price for your needs.
Strategies for Finding Cheap Business Insurance Without Sacrificing Quality
Finding cheap business insurance is about being a savvy shopper who balances cost with comprehensive protection. The biggest mistake is focusing only on price, as a cheap policy might not cover you when you need it most. Smart shopping means understanding what you’re buying and ensuring it fits your specific risks.
At Florida All Risk Insurance, our expertise in Florida Small Business Insurance allows us to find genuine savings. We focus on optimizing your policy structure, bundling coverages, and implementing risk management practices that insurers reward with lower premiums. This approach often results in better protection at a lower cost.
1. Bundle Policies for Maximum Savings
Bundling your insurance is one of the smartest ways to find cheap business insurance. The Business Owner’s Policy (BOP) is a prime example, combining General Liability, Commercial Property, and Business Interruption insurance into one package. This approach typically saves money compared to buying each policy individually.
Beyond cost savings, bundling simplifies your life. With one carrier, you have one point of contact for claims and one renewal date. At Florida All Risk Insurance, we analyze your needs to find every possible bundling option, ensuring you get maximum value and the most competitive rates.
2. Customize Your Coverage and Limits
A personalized approach to your policy can lead to significant savings while ensuring you’re properly protected. It’s about tailoring your coverage to fit your business perfectly—not too much, and not too little.
- Choose the right deductible. Your deductible is what you pay out-of-pocket before insurance kicks in. A higher deductible lowers your premium, but means more upfront cost if you file a claim. For a low-risk business, this can save hundreds annually.
- Set realistic policy limits. These are the maximum amounts your insurer will pay. While higher limits offer more protection, they also increase your premium. We help you assess appropriate limits based on your actual risk exposure, so you avoid over-insuring.
- Understand exclusions and endorsements. Exclusions are what your policy doesn’t cover, while endorsements add coverage for specific risks. A cheap policy might have major exclusions, leaving you vulnerable. The Insurance Information Institute offers valuable resources to help you understand different coverage options and assess your business insurance needs.
The goal is to find the best value, not just the lowest price. Comprehensive coverage is often more cost-effective than facing a denied claim.
3. How to Find Cheap Business Insurance by Managing Your Risks
One of the most effective ways to secure cheap business insurance is to make your business a lower-risk client. Insurers reward businesses that proactively prevent claims with lower premiums.
- Implement safety programs. Training employees on proper procedures and hazard awareness reduces workplace accidents and lowers workers’ compensation claims.
- Maintain your property. Regularly inspecting your premises for hazards like uneven floors or loose handrails can prevent costly liability claims. Documenting these checks shows insurers you’re proactive.
- Provide clear instructions. If you sell products, clear usage instructions and warning labels can prevent customer injuries and subsequent claims.
- Establish clear protocols. Documenting your procedures, from social media policies to protocols for handling client property, creates a paper trail that can be invaluable in defending against claims.
Good risk management pays dividends beyond insurance savings. It leads to less downtime, happier employees, and satisfied customers—a true investment in your business’s success.
4. Pay Your Premium Annually
Here’s a simple tip that many business owners overlook: pay your annual premium upfront. Most insurance carriers add administrative fees for monthly payment plans, which can add up to a 5% or greater increase in your total cost over a year.
By paying annually, you eliminate these extra charges. Many carriers also offer a “paid in full” discount. While this requires better cash flow management, it’s a straightforward way to make your cheap business insurance even more affordable. Many of our clients set money aside each month to prepare for the annual payment, getting the savings without the cash flow shock.
How to Get a Quote and Secure Your Policy
Ready to explore your options for cheap business insurance? Getting a quote is the first step. You can get quick estimates through online tools or work with an independent agent like us for a more custom approach.
While online tools are fast, working with an expert who understands your specific needs is where the real value lies. You can start the process to Buy Business Insurance Online through our platform, but we recommend a personal consultation to ensure you get the best coverage.
Preparing Your Information for a Quote
To get the most accurate quotes, have the following information ready:
- Your legal business name and primary address.
- Your specific industry or profession.
- Your years in business.
- Number of employees and total payroll.
- Annual revenue or sales figures.
- The coverage types you’re interested in.
- Your previous claims history (be honest—it builds trust).
Why Working with an Independent Agent Can Help You Find Cheap Business Insurance
As an independent agency, Florida All Risk Insurance offers advantages that online-only shopping can’t match:
- Access to multiple carriers: We shop the market on your behalf to find the most competitive rates and coverage.
- Unbiased advice: Our loyalty is to you, not a single insurance company. We provide objective recommendations to help you make informed decisions.
- Personalized service: We take the time to understand your unique business and its risks, ensuring your coverage fits perfectly.
- Market knowledge: We know the Florida insurance market inside and out, including local regulations and risks.
- Finding hidden discounts: We are adept at finding discounts for bundling, safety records, and other factors that you might miss on your own.
Frequently Asked Questions About Affordable Business Insurance
Business owners looking for cheap business insurance often have similar questions. Here are answers to the most common ones we hear.
Is the absolute cheapest business insurance policy always the best choice?
No. The goal is to find the best value, not just the lowest price. An extremely cheap policy often means you’re underinsured, with low coverage limits or major exclusions that leave you exposed. A single denied claim can cost far more than the money saved on premiums. Balancing price and protection is key.
Can I get business insurance if I have a claims history?
Yes. A claims history may lead to higher initial premiums, but it doesn’t disqualify you. Be transparent about your history with your agent. The most important step is to demonstrate what risk management improvements you’ve made to prevent similar incidents from happening again. As independent agents, we know which carriers are more forgiving of past claims and can help present your business in the best possible light.
How often should I review my business insurance policies?
We recommend an annual review at a minimum. However, you should also review your policies whenever your business undergoes a significant change. This includes hiring new employees, adding new services or products, increasing revenue, moving to a new location, or purchasing major equipment. Regular reviews ensure your coverage remains adequate and that you’re still getting a competitive rate.
Protecting Your Florida Business Affordably
Finding cheap business insurance is about making smart, informed decisions that protect your business without breaking the bank. The key is to secure coverage that fits your specific needs while taking advantage of every opportunity to save responsibly—through bundling, customizing limits, managing risks, and paying annually.
As an independent agency in Saint Petersburg, Florida, Florida All Risk Insurance understands the unique challenges local businesses face. Our deep knowledge and access to a wide range of carriers allow us to identify savings you might not find on your own. We don’t just sell insurance; we build relationships and craft protection strategies that grow with your company.
Operating without adequate insurance is a gamble no business owner should take. With the right coverage, you can focus on expanding your business with confidence. Cheap business insurance that doesn’t compromise on quality is achievable when you have the right partner.
Ready to protect your Florida business? Get a Quote for Your Business today to find the perfect balance of comprehensive coverage and competitive rates.
Contact Us
Florida All Risk Insurance
Address: Saint Petersburg, FL
Email: [email protected]

