

Navigating the Roads of the Sunshine City: A Complete Guide to Car Insurance in St. Pete
Welcome to St. Petersburg, a vibrant city where sunshine, culture, and coastal living converge. But with its growing popularity comes busier roads, unique weather patterns, and specific challenges for drivers. Finding the right car insurance st pete that fits your lifestyle and budget doesn’t have to be a complex puzzle. Whether you’re a new resident drawn to the waterfront parks or a long-time local navigating the Grand Central District, understanding your car insurance options is crucial for financial security.
Quick Answer for St. Pete Car Insurance Seekers:
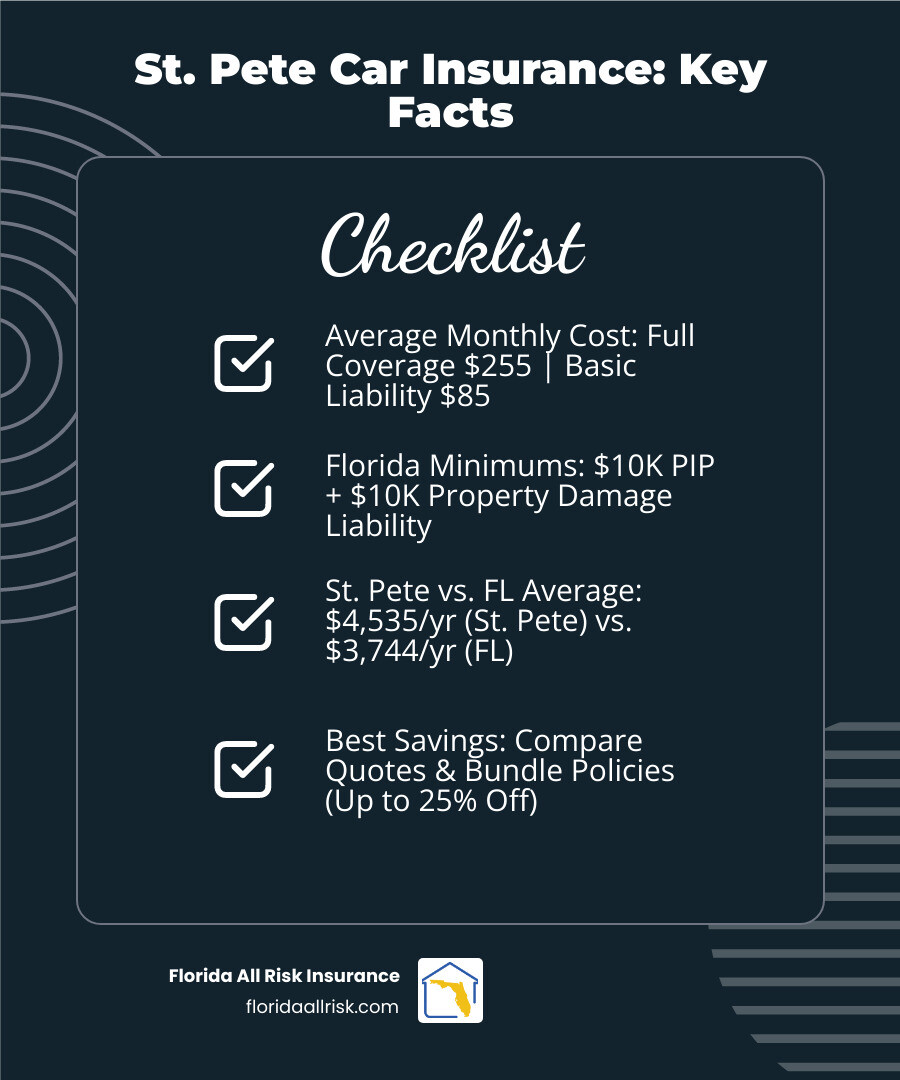
- Average monthly cost: Approximately $255 for a full coverage policy and $85 for a basic liability policy. These are just starting points; your rate will vary.
- Florida minimum requirements: All drivers must carry $10,000 in Personal Injury Protection (PIP) and $10,000 in Property Damage Liability (PDL). As we’ll explore, this is often dangerously insufficient.
- St. Pete vs. Florida average: St. Petersburg’s median annual premium of $4,535 is notably higher than the Florida state median of $3,744, reflecting localized risk factors.
- Best savings strategy: The most effective way to save is by comparing quotes from multiple insurance carriers and bundling your auto policy with home or renters insurance, which can open up discounts of up to 25%.
Living in St. Petersburg means sharing the road with tourists heading to the St. Pete Pier, navigating sudden afternoon thunderstorms that can turn streets into streams, and dealing with event traffic from Rays games or the Grand Prix. With 14,819 car crashes recorded in Pinellas County in 2023, having robust insurance coverage isn’t just a legal requirement—it’s essential financial protection against the unexpected. The higher-than-average costs in our city are driven by factors like population density, coastal weather risks, and liftd repair expenses. This guide is designed to explain these factors and empower you to secure quality coverage without overpaying.
I’m Jason Miller, a second-generation insurance professional with over two decades of dedicated experience in the Florida market. My family has a combined 60+ years of expertise, giving us a deep-rooted understanding of the Sunshine State’s unique insurance landscape. My team at Florida All Risk Insurance lives and works here in the Tampa Bay area. We know the challenges St. Petersburg drivers face because we face them too. Our mission is to find you coverage that protects not just your vehicle, but your assets and your peace of mind.
Understanding Car Insurance Costs in St. Petersburg
Before you can find savings, you need to understand what you can expect to pay for car insurance st pete. The numbers provide a baseline, but the story behind them is what truly matters for protecting your vehicle and your wallet. Let’s break down the costs for St. Petersburg drivers.
On average, a driver in St. Pete can expect to pay around $85 per month for a basic liability policy that meets Florida’s minimum requirements. For more robust protection, a full coverage policy—which includes collision and comprehensive—averages about $255 per month. It’s critical to remember that these are just averages. Your final premium is a highly personalized figure based on a multitude of factors, including your driving history, the type of vehicle you own, your chosen coverage limits, and even your credit-based insurance score. For a broader look at statewide trends, our analysis of Auto Insurance Rates Florida offers additional context.

How St. Pete Compares to Other Cities
St. Petersburg’s median annual rate for full coverage is $4,535, placing it significantly above Florida’s state median of $3,744 and the national average of around $2,014. This highlights that while Florida is an expensive state for car insurance, St. Pete is one of its pricier markets. Here’s how our city stacks up against others:
| Location | Average Monthly Full Coverage | Average Annual Full Coverage |
|---|---|---|
| St. Petersburg | $255 | $4,535 (Median) |
| Tampa | $295 | $3,540 |
| Orlando | $299 | $3,588 |
| Miami | $362 | $4,344 |
| Jacksonville | $221 | $2,652 |
| Florida State Average | $286 | $3,744 (Median) |
| National Average | $168 | $2,014 |
Note: Averages are estimates and can vary widely. Median rates provided where available for more accurate representation.
The data shows that while Miami may have higher average monthly rates, St. Pete’s median cost is among the highest in the state. Understanding the local dynamics behind these figures is the key to finding better rates.
Why Are Rates Higher in St. Petersburg?
Several interconnected local factors contribute to the higher car insurance st pete premiums.
- Population Density and Traffic Congestion: St. Petersburg is the fifth most populous city in Florida and the most densely populated county in the state. This density means more cars on the road, leading to frequent congestion on major arteries like I-275, US-19, and 4th Street North. More vehicles in close proximity inevitably lead to a higher frequency of accidents, which insurers price into their rates.
- High Accident Frequency: In 2023, Pinellas County saw 14,819 vehicle crashes, resulting in thousands of injuries. While this number has decreased slightly, it still represents a significant risk environment for insurers. High-traffic intersections and tourist-heavy areas around downtown and the beaches are particular hotspots.
- Coastal Weather Risks: Our beautiful coastal location comes with a price. Hurricane season brings the threat of widespread vehicle damage from wind and flooding. Beyond major storms, sudden and intense thunderstorms are a year-round phenomenon, creating slick roads and low visibility that contribute to accidents. The risk of flood damage, especially in low-lying areas like Shore Acres, makes comprehensive coverage a near necessity, driving up overall costs.
- Liftd Repair Costs: The cost of living in urban coastal areas translates to higher operational costs for auto repair shops, including labor rates and commercial rent. Furthermore, modern vehicles are equipped with complex sensors and technology that are expensive to repair or replace, pushing the average claim cost higher. These expenses are ultimately passed on to consumers through their premiums.
- High Rate of Uninsured Drivers: Florida has one of the highest percentages of uninsured drivers in the nation, with some estimates placing it over 20%. When an insured driver is hit by someone without insurance, the claim falls on their own Uninsured Motorist (UM) coverage. The high likelihood of needing to use this coverage forces insurers to charge more for it, increasing premiums for all responsible drivers.
- Litigious Environment and PIP Fraud: Florida’s no-fault system, while intended to streamline small claims, has unfortunately been susceptible to fraud and litigation. This litigious environment, particularly surrounding Personal Injury Protection (PIP) claims, creates massive legal and claims-related expenses for insurance companies. These costs are a major driver of why Florida’s insurance rates are among the highest in the country.
Key Factors That Influence Your Car Insurance St Pete Rates
Insurance companies don’t pull your premium out of thin air. They use sophisticated algorithms and a process called underwriting to assess your individual risk profile. Dozens of personal factors are weighed, and each detail about you, your car, and your driving habits can shift your final rate up or down. Understanding these factors is the first step toward controlling your costs.
Your Driving Record and History
This is the most significant factor in determining your rate. A clean driving record with no accidents, tickets, or violations is your golden ticket to the lowest premiums. Conversely, a history of incidents signals higher risk to insurers.
- At-Fault Accidents: A single at-fault accident can increase your premium by 30-50% or more, an impact that can last for three to five years.
- Speeding Tickets: Even a minor speeding ticket can raise your rates by 20-30%. Multiple tickets will have a cumulative effect.
- DUI/DWI: A conviction for driving under the influence is the most severe infraction. It can cause your rates to double or triple, and you will be required to file an FR-44 certificate, classifying you as a high-risk driver for years. To verify an agent’s credentials for handling such specialized filings, you can use the authoritative FINRA BrokerCheck database.
| Violation Type | Average Annual Premium Increase (St. Pete) |
|---|---|
| One Speeding Ticket (16-29 mph over) | +$750 |
| One At-Fault Accident (with property damage) | +$1,200 |
| DUI/DWI Conviction | +$3,500+ |
How Demographics and Personal Details Affect Your Premium
Insurers use demographic data as a proxy for risk, based on vast pools of statistical claims data.
- Age and Experience: Age is a powerful rating factor. Young, inexperienced drivers have statistically higher accident rates, leading to exorbitant premiums. Rates begin to drop significantly around age 25 and typically reach their lowest point for drivers in their 50s and 60s.
| Driver Age | Average Annual Full Coverage Rate (St. Pete) |
|---|---|
| 18-Year-Old | $13,500 |
| 25-Year-Old | $5,800 |
| 35-Year-Old | $4,650 |
| 55-Year-Old | $4,100 |
- Credit-Based Insurance Score: In Florida, insurers are permitted to use a credit-based insurance score to predict the likelihood of a future claim. While it’s not the same as your FICO score, it is derived from your credit history. Statistically, individuals with lower credit scores file more claims, so a poor score can lead to substantially higher premiums. Conversely, a strong credit history can earn you significant discounts.
- Marital Status & Education: Married individuals often receive slightly lower rates, as data suggests they file fewer claims. Some insurers also offer small discounts for drivers who have completed a four-year college degree or higher.
Your Vehicle and Coverage Choices
The car you drive is a major component of the insurance cost equation.
- Vehicle Type: A high-performance sports car or a luxury SUV will cost more to insure than a standard sedan or minivan. This is due to higher purchase prices, more expensive repair costs (especially for foreign parts), and higher theft rates.
- Safety Features: Modern safety features can earn you valuable discounts. Anti-lock brakes, airbags, electronic stability control, and anti-theft systems all reduce risk and can lower your premium.
- Coverage and Deductibles: Your chosen coverage has a direct impact. A minimum liability policy is cheapest, but a full coverage policy with high limits is most expensive. Your deductible—the amount you pay out-of-pocket before insurance kicks in—also plays a key role. A higher deductible ($1,000) will result in a lower premium, while a lower deductible ($250) will cost more. Balancing protection and cost is essential, and understanding auto insurance deductible options is a great place to start. For more guidance, see our resources on Affordable Car Insurance Florida.
The Impact of Your St. Pete ZIP Code
Even your specific address within St. Petersburg matters. Insurers analyze claims data on a hyper-local level, looking at risks associated with each ZIP code.
- Localized Risks: Neighborhoods with higher rates of vehicle theft, vandalism, or accident frequency will have higher average premiums. For example, rates in a dense downtown ZIP code like 33701 may be higher than in a more suburban area like 33709.
- Parking: Where you park your car overnight can also make a difference. Parking in a secure, locked garage is seen as lower risk than parking on the street, and may result in a small discount.
| St. Pete ZIP Code | Neighborhood | Average Annual Full Coverage Rate |
|---|---|---|
| 33701 | Downtown | $4,850 |
| 33702 | Gateway / NE St. Pete | $4,600 |
| 33705 | South St. Pete / Old Southeast | $4,750 |
| 33709 | Lealman / West St. Pete | $4,550 |
| 33710 | Tyrone / Jungle Terrace | $4,450 |
Florida’s Minimum Requirements and Why They Aren’t Enough
Florida operates under a “no-fault” car insurance system, which has specific minimum coverage requirements for all registered vehicles. While meeting these legal minimums is mandatory, relying on them alone can be a financially devastating mistake for St. Pete drivers.
Understanding Florida’s No-Fault Law and Minimums
The state of Florida requires every driver to carry:
- $10,000 in Personal Injury Protection (PIP): This coverage pays for your own medical expenses and lost wages after an accident, regardless of who was at fault. However, it only covers 80% of eligible medical bills and 60% of lost wages, up to the $10,000 limit. In the case of a serious injury, this amount can be exhausted after a single visit to the emergency room.
- $10,000 in Property Damage Liability (PDL): This covers damage you cause to another person’s property, such as their car, in an at-fault accident.
Crucially, Florida does not require Bodily Injury (BI) Liability coverage, which pays for injuries you cause to others. This is a critical gap in protection.
The High Cost of Minimum Coverage: A Scenario
Imagine you are driving on 4th Street North and you accidentally run a red light, causing a multi-car accident. You hit a new SUV and injure its two occupants.
- Damage to the SUV: The vehicle is valued at $50,000. Your $10,000 PDL policy pays out its limit, leaving you personally responsible for the remaining $40,000.
- Injuries to the Occupants: The driver and passenger suffer moderate injuries, with combined medical bills reaching $80,000. Since you don’t have Bodily Injury Liability, you are personally liable for the entire $80,000.
In this common scenario, a driver with minimum coverage is now facing a lawsuit for $120,000. Your assets, including your home, savings, and future wages, are all at risk.
Beyond the Minimum: Essential Coverage Options
To truly protect yourself, you must build a policy that goes far beyond the state minimums. Consider these crucial additions:
- Bodily Injury Liability (BI): This is arguably the most important coverage you can buy. It protects your assets by covering medical expenses, lost wages, and legal costs if you injure someone in an accident. We recommend limits of at least $100,000 per person / $300,000 per accident.
- Uninsured/Underinsured Motorist (UM/UIM): With over 20% of Florida drivers being uninsured, this coverage is vital. It protects you and your passengers if you’re hit by a driver with no insurance or not enough insurance to cover your injuries. You should also understand the difference between stacked and non-stacked UM coverage, a key detail in Florida. Learn more about Uninsured Motorist Coverage in Florida.
- Collision and Comprehensive: These two coverages protect your own vehicle. Collision pays for damage to your car from an accident (e.g., hitting another car or a pole). Comprehensive covers non-accident events like theft, vandalism, fire, or weather damage—essential for St. Pete’s storm season.
- Medical Payments (MedPay): This optional coverage helps fill the gaps left by PIP. It can cover the 20% of medical bills that PIP doesn’t, and it can also be used to pay your PIP deductible.
Drivers should thoroughly review the available auto insurance coverage options to build a policy that provides adequate protection for their individual circumstances.
Penalties for Driving Without Car Insurance St Pete
The consequences for driving uninsured in Florida are severe and immediate. If you are caught without the required PIP and PDL coverage, you face:
- Immediate suspension of your driver’s license, vehicle registration, and license plates.
- A reinstatement fee starting at $150 for a first offense. This fee escalates to $250 for a second offense and $500 for subsequent offenses within a three-year period.
- A potential SR-22 certificate requirement. This designates you as a high-risk driver to the state and will cause your insurance premiums to be significantly higher for several years. The financial cost of proper insurance is a fraction of the penalties and long-term financial pain of getting caught without it.
Actionable Strategies to Lower Your Car Insurance St Pete Premiums
While St. Petersburg has higher-than-average rates, you are not powerless. By taking a strategic and proactive approach, you can significantly reduce your monthly premium without sacrificing crucial protection. Here are the most effective strategies for finding affordable car insurance st pete.
1. Compare Quotes from Multiple Carriers
This is the single most important step you can take. Insurance rates for the exact same driver and vehicle can vary by hundreds or even thousands of dollars per year between different companies. Don’t assume the first quote you get is the best one.
- Independent Agents: Working with an independent insurance agency like Florida All Risk Insurance gives you a significant advantage. We represent multiple carriers, allowing us to shop the market on your behalf to find the best combination of coverage and price for your specific needs.
- Captive Agents: These agents work for a single company (e.g., State Farm, Allstate) and can only offer you that company’s products.
- Direct Insurers: These companies (e.g., Geico, Progressive) sell directly to consumers online or over the phone. While convenient, you are responsible for doing all the comparison shopping yourself.
2. Bundle Your Policies for Maximum Savings
If you own a home or rent an apartment, bundling your auto insurance with your homeowners or renters insurance policy is one of the easiest and most effective ways to save. Most companies offer a multi-policy discount that can be as high as 25%. Beyond the significant savings, it simplifies your financial life by having one point of contact and one bill for your primary insurance needs. This strategy is often a deciding factor when choosing among the best auto insurance companies in St. Petersburg.
3. Hunt for Every Available Discount
Insurers offer a wide array of discounts, but they often don’t apply them automatically. You need to ask. Review this checklist and see which ones you might qualify for:
- Driver-Based Discounts:
- Good Student: For young drivers with a ‘B’ average or better.
- Defensive Driving Course: Completing an approved course can provide a discount for 3-5 years.
- Low Mileage: If you have a short commute or don’t drive often.
- Good Driver / Claims-Free: For maintaining a clean record for a set number of years.
- Profession/Affiliation: Discounts for certain professions (e.g., teachers, engineers, first responders) or membership in organizations (e.g., military, alumni associations).
- Policy-Based Discounts:
- Multi-Car: Insuring more than one vehicle with the same company.
- Paid-in-Full: Paying your entire 6- or 12-month premium upfront.
- Automatic Payments / Paperless Billing: Small but easy discounts for administrative convenience.
- Continuous Insurance: For having no lapses in coverage, even if you switch companies.
4. Optimize Your Coverage and Deductibles
Review your policy annually to ensure your coverage still makes sense for your situation.
- Raise Your Deductible: Increasing your comprehensive and collision deductibles from $500 to $1,000 can lower your premium by 15-30%. Just be sure you can comfortably afford the higher out-of-pocket cost if you need to file a claim.
- Drop Unnecessary Coverage: If you drive an older car with a low market value, it may no longer be cost-effective to pay for full coverage. As a general rule, if your annual premium for collision and comprehensive is more than 10% of your car’s Blue Book value, you should consider dropping it.
5. Improve Your Credit-Based Insurance Score
Because a better credit history correlates with lower insurance risk, improving your credit can lead to lower premiums over time. Focus on paying bills on time, keeping credit card balances low, and avoiding opening unnecessary new lines of credit. This long-term strategy can yield significant savings.
Special Considerations for St. Pete Drivers
Driving in St. Petersburg isn’t just about the daily commute; it’s about navigating a unique environment with specific circumstances that can impact your car insurance st pete needs and costs. From hurricane preparedness to insuring a prized classic, here’s what local drivers need to know.
Insurance for High-Risk Drivers
Having a blemished driving record—such as multiple at-fault accidents, a DUI conviction, or a lapse in coverage—can place you in a “high-risk” category. While this means you’ll face higher premiums, coverage is still attainable.
- SR-22 Certificate: This isn’t a type of insurance, but rather a certificate of financial responsibility that your insurer files with the state on your behalf. It proves you have active, state-required insurance and is often required after violations like driving without insurance or a license suspension.
- FR-44 Filing: This is a more stringent requirement specifically for drivers convicted of a DUI or other serious violations in Florida. It mandates much higher liability limits: $100,000 per person, $300,000 per accident in Bodily Injury Liability, and $50,000 in Property Damage Liability. These limits are significantly higher than standard policies, and the FR-44 must be maintained for three years without a lapse. Specialized insurers can provide this coverage, which may include options like non-owner car insurance in Florida if you don’t own a vehicle but need to maintain the filing.
Protecting Your Classic Car
St. Petersburg has a thriving classic car culture, but a standard auto policy is inadequate for protecting these unique investments. Classic car insurance is specifically designed for these vehicles.
- Agreed Value Coverage: This is the cornerstone of a classic car policy. You and the insurer agree on the car’s value upfront. In the event of a total loss, you receive that full agreed-upon amount, with no deduction for depreciation. This is far superior to the “actual cash value” offered by standard policies.
- Mileage Limitations and Use Restrictions: These policies are more affordable because they assume the car is not a daily driver. They often come with annual mileage limitations (e.g., 2,500 or 5,000 miles per year) and require the car to be stored in a secure, enclosed garage. Owners should explore dedicated options for Florida classic car insurance to properly safeguard their investment.
Local Driving Conditions and What They Mean for Your Car Insurance St Pete
Your insurance policy should be custom to address the specific challenges of the St. Pete environment.
- Weather: Hurricane season (June–November) and the year-round risk of flooding, especially during “King Tides” in neighborhoods like Shore Acres and Snell Isle, make comprehensive coverage non-negotiable. This coverage is what protects your vehicle from damage caused by high winds, falling objects, and rising water. Even St. Pete’s daily afternoon thunderstorms create hazardous, slick road conditions that contribute to a higher rate of accidents.
- Tourist and Event Traffic: Peak tourist season and major local events dramatically increase traffic density with drivers who are often unfamiliar with local roads. Be extra cautious during events like the Firestone Grand Prix, a Tampa Bay Rays game, or even the popular Saturday Morning Market, as these bring congestion and increase the risk of fender-benders, especially in the downtown core and near the pier.
- Rideshare and Delivery Driving: If you drive for services like Uber, Lyft, DoorDash, or Instacart, your personal auto policy will not cover you while you are working. You need a commercial policy or a special rideshare endorsement from your insurer to be protected while on the clock. Driving without this coverage can lead to a denied claim and personal liability for any damages.
- Local Development: St. Petersburg is constantly evolving. Ongoing construction projects, like the redevelopment of the Tropicana Field site or major roadwork on the I-275 corridor, can create temporary and long-term changes to traffic patterns, detours, and road hazards. Staying aware of these projects, such as those listed on the city’s project website, can help you avoid incidents that could negatively impact your insurance rates.
Conclusion: Your Partner for Affordable St. Pete Car Insurance
Navigating the complexities of car insurance st pete can feel like a daunting task, but it doesn’t have to be. Throughout this guide, we’ve digd deep into the specifics of insuring a vehicle in the Sunshine City. We’ve explored the average costs and the local factors that drive them, dissected Florida’s dangerously low minimum requirements, and outlined the severe penalties for driving without proper coverage. Most importantly, we’ve provided a clear, actionable roadmap to help you find the most affordable rates without compromising on the protection your family and assets deserve.
The key takeaways are simple but powerful: you must be a proactive consumer of insurance. This means diligently comparing quotes from a variety of carriers, asking about every possible discount, leveraging the power of bundling your policies, and understanding how your personal choices—from the car you drive to the deductible you select—impact your bottom line. Maintaining a clean driving record and a healthy credit score are long-term strategies that will always yield the best results.
As an independent insurance agency rooted in the St. Petersburg community, Florida All Risk Insurance is uniquely positioned to be your advocate in this process. We don’t work for one single insurance company; we work for you. This allows us to shop the entire market on your behalf, comparing offerings from a wide range of top-rated carriers to find the perfect fit for your budget and your unique needs. Our goal is to move beyond a one-size-fits-all approach, providing personalized service and comprehensive solutions that give you custom-custom coverage at a competitive price. We are committed to helping you protect what matters most so you can enjoy the beautiful roads of St. Pete with true peace of mind.
Don’t let the search for affordable car insurance st pete leave you feeling overwhelmed or underinsured. Let our expertise be your guide. We’re here to answer your questions, provide expert advice, and build the best policy for you.
Explore our auto insurance solutions today and find how we can help you save!
Contact Us
Florida All Risk Insurance
Saint Petersburg, FL
Phone: (727) 304-0909
Email: [email protected]

