

Business insurance St. Petersburg: Safeguard Your Future 2025
Why Your St. Petersburg Business Needs a Safety Net
Business insurance St. Petersburg is the essential financial safeguard for your company, protecting it from the lawsuits, natural disasters, and unexpected losses that could destroy everything you’ve built. St. Petersburg’s vibrant and diverse business community—from the busy restaurants on Beach Drive and the unique shops on Central Avenue to marine businesses at the port, construction companies rebuilding our skyline, and innovative tech startups—faces a unique combination of risks that demand proper insurance coverage. This dynamic environment offers incredible opportunities for growth, but it also comes with serious threats. These can range from common incidents like customer slip-and-fall accidents and equipment theft to modern dangers like sophisticated cyber attacks and the ever-present risk of Florida’s notorious hurricane season. Without the right coverage, a single lawsuit or a powerful storm could wipe out years of hard work and investment in an instant.
The stakes are real and quantifiable. According to industry data, 43% of cyber attacks target small businesses, and the consequences can be devastating. Commercial insurance is a complex field as there are so many types of businesses and so many aspects to any one business, according to local insurance experts. This complexity is precisely why choosing the right insurance partner—one who understands the local St. Pete market—matters so much for your company’s survival and long-term growth.
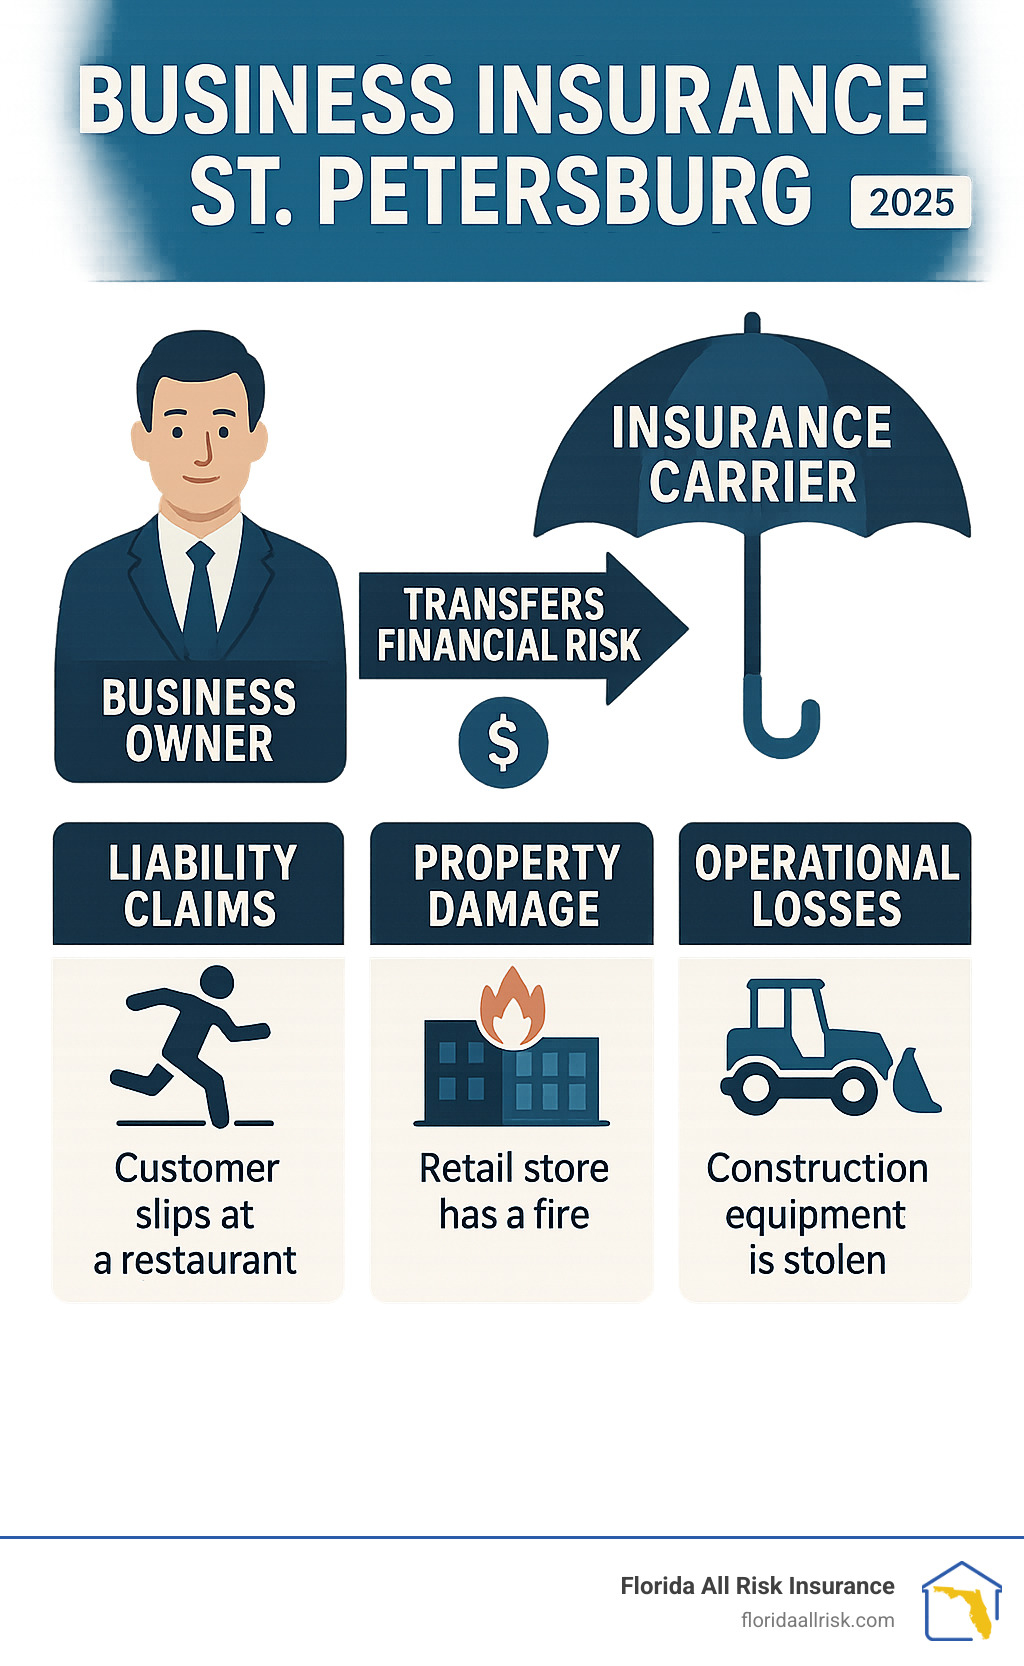
Business insurance St. Petersburg terms to learn:
- commercial property insurance
- commercial property and business interruption insurance
- independent business insurance agents
Every business, regardless of its size or industry, operates with a degree of inherent risk. In a thriving, high-traffic market like St. Petersburg, these risks are often amplified. Imagine a busy restaurant near the Pier where a customer could slip on a wet floor, a kitchen fire could erupt during peak hours, or a hurricane could shatter windows and flood the dining room. For a construction company working on a new downtown condo, a worker could be seriously injured on site, or thousands of dollars in tools and materials could be stolen overnight. Even a seemingly low-risk tech startup in the Innovation District faces the constant threat of data breaches, ransomware attacks, or professional negligence claims from a client who alleges a costly error in their work.
Protecting your livelihood is paramount. Your business is your passion, your investment, and your future. Business insurance St. Petersburg acts as a crucial safety net, absorbing the financial shock of unforeseen events. It allows you to pursue your vision with confidence, knowing you have a robust defense against potential disasters. One of the most significant and growing threats is the risk of lawsuits. The chances of getting sued have dramatically increased for business owners in the last decade. Legal battles are not only stressful but also incredibly costly, often running into tens or even hundreds of thousands of dollars. Business insurance can cover defense costs, settlements, and court-awarded damages, preserving your capital for growth.
Beyond legal challenges, St. Petersburg businesses must contend with the serious environmental risks of our coastal location. Hurricanes and floods are not abstract possibilities; they are realities we must plan for annually. Safeguarding your physical assets—your building, equipment, and inventory—means having the right insurance policies in place to rebuild and recover quickly. Comprehensive business insurance St. Petersburg provides invaluable peace of mind, allowing you to focus on what you do best: innovating, serving your customers, and driving the growth of your enterprise.
Essential Business Insurance Coverages for St. Pete Entrepreneurs
Navigating business insurance St. Petersburg can seem complex, but it boils down to a few core protections designed to address the most common and costly risks. While every business has unique needs that may require specialized policies, several foundational coverages form the backbone of any smart risk management strategy in our coastal city.
The Foundation: General Liability Insurance
General Liability Insurance is the workhorse of business protection. This policy is designed to protect your business when a third party—such as a customer, client, or vendor—claims that your business operations caused them bodily injury or damaged their property. It’s the first line of defense against the everyday risks of interacting with the public.
This essential coverage protects against a wide range of claims:
- Bodily injury claims: If a customer slips on a spilled drink in your cafe or trips over a cord in your office.
- Customer property damage: If one of your employees accidentally scratches a client’s expensive hardwood floor while making a delivery.
- Product liability: If a food product you sell causes food poisoning or a handcrafted item has a defect that injures a customer.
- Advertising injury: For claims of copyright infringement in your marketing materials, libel, or slander.
- Lawsuit defense costs: Even if a claim against you is frivolous and ultimately dismissed, defending your business in court is expensive. General Liability covers attorney fees, court costs, and other legal expenses.
General Liability protects against bodily injury or property damage claims by third parties, making it a non-negotiable policy for any serious business owner. Personal umbrella liability policies generally have an exclusion for business-related liability, so your personal insurance will not cover these incidents. To learn more, see What Does General Liability Insurance Cover? and How Much General Liability Insurance Do I Need?.
Protecting Your Physical Assets with Commercial Property Insurance
Commercial Property Insurance protects the physical assets that make your business run, from the building itself to the equipment inside and the inventory on your shelves. Commercial Property safeguards physical business premises against damages from covered events like fire, theft, vandalism, and many types of storm damage.
Key protections include:
- Building coverage: For the physical structure if you own the property.
- Equipment protection: Covering everything from your office computers and point-of-sale systems to specialized machinery and tools.
- Inventory insurance: For the products you manufacture or sell.
- Furniture and fixtures: Including displays, desks, shelving, and other business contents.
- Business Personal Property (BPP): A broad category for other physical assets, including items owned by the business that are not part of the building itself.
- Tenant’s Improvements and Betterments: Covers improvements you’ve made to a leased space, which you would lose if the building were destroyed.
When evaluating this coverage, understand the difference between Replacement Cost Value (RCV), which pays to replace your property with new items of similar kind and quality, and Actual Cash Value (ACV), which only pays the depreciated value. RCV provides superior protection. Replacing everything after a major loss can be financially devastating, and this policy ensures you can rebuild and restock without draining your savings. For more details, visit our Commercial Property Insurance page.
Specialized Coverage for St. Petersburg’s Coastal Climate
St. Petersburg’s beautiful coastal location brings unique and severe weather risks that standard policies might not fully cover. It is critical to address these gaps.
- Flood insurance: This is crucial because standard commercial property policies almost universally exclude damage from flooding (defined as rising surface water). Generally does not offer flood insurance as part of standard coverage due to high risk in Florida, so a separate policy through the National Flood Insurance Program (NFIP) or a private carrier is necessary. You can assess your property’s specific risk by checking FEMA’s Flood Map Service Center.
- Windstorm coverage: While some wind damage is covered by standard property policies, damage from named hurricanes may be subject to a separate, much higher hurricane deductible. This deductible is often a percentage (e.g., 2%, 5%, or 10%) of your total insured property value, not a flat dollar amount, which can result in a significant out-of-pocket expense.
- Business Interruption Insurance: Often called Business Income Insurance, this is a game-changing coverage that can be the key to your business’s survival after a disaster. If a covered event (like a fire or hurricane) forces you to temporarily close your doors, this policy replaces your lost net income and covers ongoing expenses like rent, utilities, and payroll. It ensures you can meet your financial obligations and pay your key employees even when you have no revenue coming in.
Being prepared with the right combination of coastal coverage lets you focus on running your business instead of constantly worrying about the weather.
Understanding Florida’s Legal Requirements for Business Insurance St. Petersburg
When it comes to business insurance St. Petersburg, some coverages aren’t just smart business decisions – they are mandated by Florida law. Failing to comply with these state requirements can lead to severe consequences, including hefty fines, stop-work orders issued by the state, personal liability for injuries, and even the forced closure of your business.
The most significant legal requirement for most businesses revolves around Workers’ Compensation insurance. If you have employees, Florida law almost certainly requires you to carry this coverage. The purpose of this system is straightforward: Workers compensation laws were created to ensure employees injured on the job receive fixed monetary awards, eliminating the need for litigation. This no-fault system provides benefits to injured workers while protecting employers from potentially crippling lawsuits.
Here’s where the law gets specific: most non-construction businesses in Florida need to secure Workers’ Compensation coverage once they have four or more employees, whether those employees are full-time or part-time. However, the rules are much stricter for the construction industry, a major economic driver in St. Petersburg. If your business is in construction, you are required to have coverage with just one employee. Agricultural businesses have their own set of rules as well. This is not optional; it’s a mandatory requirement enforced by the Florida Division of Workers’ Compensation. Penalties for non-compliance can include fines of up to double what the premium would have been for the period of non-compliance.
Many business owners get confused about what Workers’ Compensation actually covers. It is not a general health insurance policy. Workers’ Compensation is designed specifically for injuries sustained on the job and is not health insurance. It pays for medical expenses, rehabilitation costs, and a portion of lost wages for employees who get hurt or become ill as a direct result of their work duties. It’s a separate, standalone policy that you can’t bundle into other coverage – in-home businesses and standard Business Owner’s Policies (BOPs) typically do not include this vital protection.
Commercial Auto Insurance is another legal must-have, but only if your business owns, leases, or operates vehicles. Commercial auto insurance is mandatory if your business owns or operates vehicles. This applies whether you have a single delivery van for your restaurant, a fleet of service trucks for your HVAC company, or an executive car titled in the business’s name. Florida’s minimum liability requirements must be met.
Crucially, even if your employees use their personal cars for business errands—like visiting clients, making bank deposits, or picking up supplies—your business is exposed to significant risk. If that employee causes an accident while on the clock, their personal auto policy may deny the claim because it was being used for commercial purposes. This is where “hired and non-owned auto liability” coverage becomes essential. Business auto policies differ from personal auto policies in many technical respects, requiring an agent’s explanation to avoid potentially catastrophic coverage gaps. Always ensure your business name appears as the “principal insured” on any policy for a company-owned vehicle.
Beyond these foundational requirements, some industries face additional mandates. Professional service providers like doctors, lawyers, architects, and engineers often need to carry Professional Liability insurance (also known as Errors & Omissions) to maintain their state licenses. Construction companies working on public projects typically need to secure specific surety bonds and carry higher liability limits. Healthcare providers face a complex web of coverage mandates, and certain contractors must carry specific insurance amounts to even be eligible to bid on projects. The key is understanding what applies to your specific business, as Florida’s requirements can vary significantly based on your industry, number of employees, and business activities.
For comprehensive guidance on Florida’s specific insurance landscape, check out our detailed resource on Florida Small Business Insurance. Understanding these legal requirements is your first step toward proper protection and peace of mind.
How to Find the Right Insurance Partner in St. Petersburg
Choosing the right partner for your business insurance St. Petersburg needs is as critical as any other strategic business decision. You aren’t just buying a policy; you are investing in a relationship with a trusted advisor who understands the local market, advocates for your best interests, and provides crucial support when you need it most.
Understanding your options is the first step. In the insurance world, there are three main types of providers, each with a different business model:
- Independent agents work with multiple, carefully selected insurance companies. This allows them to shop the market on your behalf to find the best combination of coverage, service, and price.
- Captive agents represent only one single insurance company. While they may have deep knowledge of their company’s products, they cannot offer competing options.
- Direct writers sell their own company’s policies directly to consumers, often online or through call centers, with a model that emphasizes self-service over personalized advice.
| Feature | Independent Agents | Captive Agents | Direct Insurance Writers |
|---|---|---|---|
| Number of Carriers | Represent multiple insurance companies | Represent only one insurance company | Sell insurance directly to consumers online/phone |
| Policy Options | Wide range of options; can shop for best fit/price | Limited to the offerings of their single company | Limited to their own company’s products |
| Client Advocacy | Work for the client; can advocate during claims | Work for the insurance company; loyalty is to them | No direct agent relationship; you advocate for yourself |
| Personalization | Highly personalized; custom-custom solutions | Can be personalized, but within company limits | Less personalized; standardized, one-size-fits-all offerings |
| Service Model | Relationship-based; ongoing service, policy reviews | Provide service for their company’s policies | Primarily transactional; self-service support portals |
| Local Expertise | Often deeply embedded in the local community | Varies; may or may not be local | Typically operate from large, centralized call centers |
Local expertise is a vital, often underestimated, advantage in a unique market like St. Petersburg. An agent who lives and works here understands our coastal climate, local building codes, neighborhood-specific flood risks, and the common challenges faced by local businesses. They know which insurance carriers have a proven track record of handling hurricane claims efficiently and fairly, and they can guide you through the complex claims process when disaster strikes.
The Benefits of Working with a Local, Independent Agency
A local, independent agency offers a powerful combination of choice, personalization, and advocacy that is hard for other models to match.
- Personalized, Unbiased Advice: An independent agent takes the time to conduct a thorough needs analysis, understanding your specific operations, risks, and budget. They then craft a coverage plan custom to you, rather than pushing a predetermined product.
- Access to a Broader Market: Your agent can shop the market for you, leveraging their relationships with various insurers to find better coverage at more competitive prices. This saves you the immense time and effort of getting quotes from multiple companies yourself.
- Deep Community Knowledge: Local agents understand St. Petersburg’s unique challenges. They know the difference in flood risk between Snell Isle and the Old Northeast, are familiar with local ordinances, and have experience helping businesses just like yours steer the insurance landscape.
- A True Advocate: A great independent agent acts as your long-term partner. They proactively review your coverage as your business grows, help you with risk management, and most importantly, stand by your side to advocate on your behalf during a claim, ensuring you receive a fair and prompt settlement.
To learn more about these advantages, visit our page on Independent Business Insurance Agents.
Evaluating Providers: What to Look for in Business Insurance St. Petersburg
When choosing your insurance partner, conduct your due diligence. Consider these critical factors:
- Financial Stability of Carriers: Ensure the insurance carriers being proposed have strong financial ratings from independent agencies like A.M. Best (an “A” rating is a good benchmark). This indicates their ability to pay claims, even after a widespread catastrophe.
- Customer Reviews and Reputation: Look for consistent positive feedback on Google, Yelp, and other platforms. Pay attention to comments about communication, responsiveness, and claims handling.
- Claims Process and Reputation: Ask the agent about the claims processes of the carriers they recommend. A good reputation for fair and timely settlements is crucial. The cheapest policy is worthless if the carrier won’t pay a legitimate claim.
- Industry Specialization: An agency with experience insuring businesses in your specific industry (e.g., restaurants, construction, tech) will have a deeper understanding of your risks and the coverages you need.
- Licensing and Credentials: Verify that the agency and agent are properly licensed in Florida. You can do this through the Florida Department of Financial Services’ Licensee Search.
- Customization and Consultation: Your business is unique; your insurance should be too. Look for a partner who asks thoughtful questions and focuses on educating you, not just selling you a policy.
For a comprehensive guide, check out our resource on Insurance Agencies in St. Petersburg, FL. The cheapest option isn’t always the best value. Investing in quality coverage and expert service is an investment in protecting everything you’ve worked so hard to build.
Decoding the Dollars: Business Insurance Costs and Savings
Understanding the cost of business insurance St. Petersburg can feel opaque because every premium is custom-calculated based on a wide array of factors unique to your business. Knowing what drives these costs is the first step toward making informed decisions and identifying opportunities for significant savings without sacrificing crucial protection.
Key factors influencing your premium include:
- Industry and Operations: A roofing contractor faces inherently higher risks than a graphic designer working from a home office. Insurance companies use classification codes (like NAICS or ISO codes) to categorize your business and set a baseline risk level.
- Business Size and Revenue: More employees, higher annual revenue, and a larger payroll generally mean more exposure to potential claims, which translates to higher premiums for liability and workers’ compensation insurance.
- Location, Location, Location: In St. Petersburg, this is a major factor. Proximity to the coast dramatically increases hurricane and flood risks, directly impacting commercial property insurance rates. Other location factors include local crime rates and the rating of your local fire department (Protection Class).
- Claims History: Your business’s loss history is a primary indicator of future risk. A clean claims record can lead to significant discounts, while a history of frequent claims will signal higher risk to underwriters and increase your costs.
- Coverage Limits & Deductibles: The amount of coverage you choose (your policy limits) directly affects the price. Higher limits mean higher premiums. Conversely, your deductible—the amount you agree to pay out-of-pocket on a claim before insurance kicks in—has an inverse relationship. Choosing a higher deductible can lower your premium.
- Building Construction: For property insurance, a masonry or fire-resistive building will have lower rates than a wood-frame structure, especially in a hurricane-prone area.
Smart Strategies to Lower Your Premiums
While some cost factors are fixed, you have considerable control over others. You can actively lower your rates through smart risk management and strategic policy choices.
- Bundle Policies with a BOP: For many small to medium-sized businesses, a Business Owner’s Policy (BOP) is a great option. It conveniently combines general liability, commercial property, and often business interruption insurance into a single package, usually at a discounted rate compared to buying each policy separately.
- Implement a Formal Risk Management Program: Show insurers you are a proactive, low-risk client. This includes having documented safety training programs for employees, robust quality control processes, and strong cybersecurity protocols like multi-factor authentication and regular data backups.
- Prioritize Workplace Safety: A safe workplace is the best way to control workers’ compensation costs. Hold regular safety meetings, keep your premises free of hazards, and invest in ergonomic equipment. A positive safety culture reduces claims and can lower your insurance premiums over time.
- Install Security and Safety Systems: Central-station fire and burglar alarms, sprinkler systems, and security cameras can earn you significant discounts on your property insurance.
- Choose Higher Deductibles Wisely: If your business maintains a healthy cash flow, opting for a higher deductible on your property or auto policies can lead to immediate premium savings. Just be sure you can comfortably cover the deductible amount in the event of a claim.
- Conduct Annual Policy Reviews: Your business is not static, and neither are your insurance needs. A yearly review with your agent ensures your coverage is appropriate for your current operations, that you aren’t overpaying for coverage you no longer need, and that you are taking advantage of any new available discounts.
An experienced independent agent can be your best ally in implementing these strategies effectively. For more guidance on finding affordable yet robust coverage, explore our guide on Cheap Business Insurance. The ultimate goal is not just to find the cheapest price, but to achieve the best value—the optimal balance of comprehensive protection and affordability.
The Simple Path to Getting a Business Insurance Quote
Getting a business insurance St. Petersburg quote should be a straightforward and empowering process. At Florida All Risk Insurance, we’ve streamlined the steps to ensure you not only get the right protection but also understand the value behind it, so you can get back to running your business with confidence.
The journey starts with a simple phone call or online inquiry. We firmly believe that taking the time to have a real conversation and understand your business upfront leads to far superior protection down the road. To provide accurate coverage options and pricing, we need to learn about your unique situation.
Having the right information ready makes the process smooth and efficient. Be prepared to discuss:
- Your business operations: A detailed description of what you do, the services you provide or products you sell, and your primary customer base.
- Annual revenue and payroll: These figures help determine the scale of your operations and are key factors for liability and workers’ compensation premiums.
- Number of employees: This is crucial for workers’ compensation and understanding your overall liability exposure.
- Physical location: Your address helps determine risks related to weather, crime, and fire protection.
- Vehicles: Information on any vehicles owned or used by the business.
- Previous insurance and claims history: A copy of your current policies and a claims history report (known as a loss run) are extremely helpful.
Don’t worry if you don’t have exact figures at your fingertips; estimates are perfectly fine to start the conversation. We can always refine the details and adjust your policy as your business grows and evolves. While some online-only tools promise instant quotes, we find that an agent-assisted process often uncovers critical coverage needs and money-saving opportunities that automated systems might miss. You can learn more about the purchasing process on our Buy Business Insurance page.
What to Expect When Requesting a Quote for Business Insurance St. Petersburg
When you reach out to us for a business insurance St. Petersburg quote, you’re not just starting a transaction; you’re starting a partnership.
Our process begins with a consultation to understand your operations, goals, and biggest concerns. This isn’t a sales pitch; it’s a genuine findy effort to learn what makes your business tick. Whether you’re worried about slip-and-fall accidents in your retail store, data breaches at your tech firm, or surviving hurricane season, we want to know what keeps you up at night.
Next, we craft customized proposals. Leveraging our strong relationships with multiple top-rated insurance carriers, we shop the market on your behalf to find the best combination of coverage and price. We’ll then present you with several clear, easy-to-understand options that are custom to your specific needs and budget.
Understanding your coverage is crucial. We take the time to translate insurance jargon into plain English. We’ll walk you through your proposal, explaining what’s covered, what’s not (the exclusions), and why each piece matters for your St. Pete business. We encourage you to ask questions! A good agent should be able to clearly explain their recommendations. Consider asking:
- What are the most common claims for a business like mine in this area?
- Can you explain the main exclusions in this policy?
- What is the carrier’s reputation for handling claims?
- How will my premium change if my business grows this year?
Throughout this entire process, your privacy and business information remain protected. We handle your sensitive data with the utmost care and confidentiality. You can review data handling practices through the Google Privacy Policy for any online interactions. Our ultimate goal is to ensure you feel completely confident in your insurance decisions, backed by a local team that truly understands the unique challenges and opportunities of doing business in St. Petersburg.
Conclusion: Fortify Your Business for a Prosperous Future
In the vibrant and changing landscape of St. Petersburg, safeguarding your business is not just a necessity; it’s a strategic imperative. We’ve explored why business insurance St. Petersburg is your essential safety net, protecting your empire from lawsuits, liabilities, and the unique challenges posed by our coastal environment. From the foundational General Liability to crucial Commercial Property and specialized Flood and Windstorm coverages, we’ve outlined the policies that form the bedrock of your protection.
We’ve also digd into Florida’s legal mandates, ensuring you’re aware of requirements like Workers’ Compensation and Commercial Auto insurance. Most importantly, we’ve highlighted the invaluable benefits of partnering with a local, independent agency like ours – one that offers personalized advice, access to multiple carriers, deep community knowledge, and unwavering client advocacy. By understanding the factors influencing costs and implementing smart savings strategies, you can secure robust protection without breaking the bank.
The path to getting a business insurance quote is simple and designed to empower you with knowledge. Our commitment is to ensure you understand your coverage and feel confident in your choice.
Your business is more than just a livelihood; it’s a bold step into the market, fueled by your hard work and vision. Don’t leave your hard-earned success to chance. Take proactive steps today to fortify your business for a prosperous future.
Learn more about protecting your commercial property today
For additional resources and insights on business insurance, we encourage you to visit:
- U.S. Small Business Administration – Business Insurance Overview
- Insurance Information Institute – Business Insurance Basics
Contact Us
Ready to protect your St. Petersburg business? We’re here to help you steer business insurance St. Petersburg with the personal touch you deserve.
At Florida All Risk Insurance, we believe insurance should be about relationships, not just policies. When you reach out, you’ll speak with real people who understand the local market and genuinely care about your business’s success.
Prefer to reach out by email? Drop us a line at [email protected]. We’ll get back to you promptly with answers to your questions or to schedule a convenient time to discuss your coverage needs in detail.
Our office is right here in Saint Petersburg, FL, where we’ve been serving the local business community for years. We know the challenges you face—from hurricane season preparations to the everyday risks of running a business in our vibrant coastal city. That local expertise makes all the difference when it comes to getting the right coverage at the right price.
Florida All Risk Insurance
Saint Petersburg, FL
Phone: (727) 232-1100
Email: [email protected]

