

Protecting Your Sunshine State Venture
Business insurance Florida is essential for protecting your company against the unique risks of operating in the Sunshine State. Whether you’re facing hurricanes, floods, or everyday business liabilities, the right insurance coverage keeps your venture secure and compliant with state law.
Quick Answer: What You Need to Know About Business Insurance in Florida
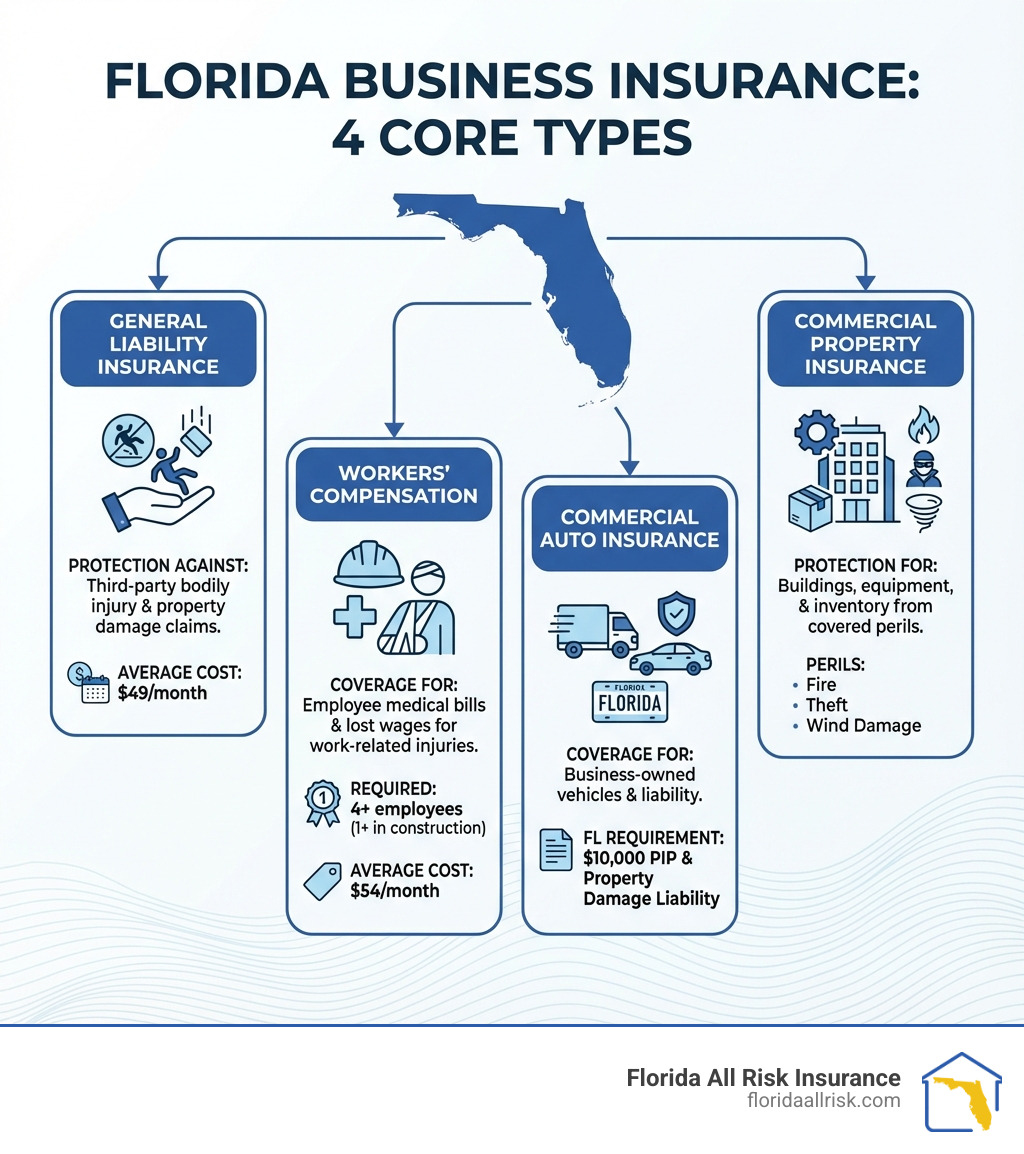
- Workers’ Compensation: Required for businesses with 4+ employees (or 1+ in construction)
- Commercial Auto: Mandatory for all business-owned vehicles (minimum $10,000 PIP and property damage liability)
- General Liability: Not legally required but often needed for leases and contracts (avg. $49/month)
- Professional Liability: Essential for service providers and advisors (avg. $71/month)
- Commercial Property: Protects your physical assets from fire, theft, and weather damage
Florida’s economy depends on small businesses. These enterprises employ 3.6 million Floridians across countless professions, from coastal restaurants to inland tech startups. But running a business in Florida comes with distinct challenges that many other states simply don’t face.
Hurricanes threaten coastal operations every summer and fall. Flooding can damage inventory and equipment in a matter of hours. The state’s tourism-driven economy creates unique liability exposures, especially for hospitality, retail, and service businesses.
Without proper insurance, a single lawsuit, storm, or accident could wipe out everything you’ve built. A slip-and-fall customer injury could cost tens of thousands in legal fees. A hurricane could destroy your physical location. An employee injury without workers’ comp coverage could result in fines and lawsuits that threaten your personal assets.
This guide walks you through the entire process of securing business insurance Florida coverage—from understanding mandatory requirements to comparing quotes and finding the best rates. You’ll learn which policies you legally need, which ones protect you from common Florida risks, and how to save money while getting comprehensive protection.
I’m Jason Miller, and I’ve been helping Florida businesses secure comprehensive business insurance Florida coverage for over 20 years, drawing on more than 60 years of combined family experience in this state’s unique insurance marketplace. My goal is to make the quote process clear, simple, and custom to your specific needs so you can focus on growing your business with confidence.
Business Insurance Florida terms to know:
Understanding Florida’s Mandatory Insurance Laws
Operating a business in Florida means understanding and adhering to specific state laws regarding insurance. These aren’t just suggestions; they are legal obligations designed to protect employees, the public, and even your business from financial ruin. Failing to meet these requirements can lead to severe penalties, but fulfilling them provides peace of mind, protects your assets, and ensures the safety and well-being of your employees. Let’s explore the specifics.
Workers’ Compensation Insurance Requirements
When it comes to protecting your team, workers’ compensation insurance is paramount and often legally mandated. Florida state law requires businesses with four or more employees, whether full-time or part-time, to carry workers’ compensation insurance. This isn’t just a good idea; it’s the law, ensuring that if one of your dedicated team members gets injured or falls ill because of their job, their medical bills and a portion of their lost wages are covered. This coverage is crucial for both your employees and for shielding your business from potentially devastating lawsuits.
Now, here’s a little twist for our friends in the construction industry: the rules are even stricter. If you’re running a construction business in Florida, you must provide workers’ compensation insurance even if you have just one employee. That’s right, just one! This reflects the higher risks associated with construction work. The average cost for workers’ compensation insurance in Florida is around $54 per month, a small price to pay for such vital protection. It covers medical bills, rehabilitation costs, and a percentage of lost wages, preventing injured employees from having to sue your business directly for these expenses.
Commercial Auto Insurance Requirements
If your business relies on vehicles – whether it’s a delivery van, a service truck, or even a car used for client visits – commercial auto insurance is a non-negotiable requirement in Florida. Unlike some states, Florida operates under a “no-fault” auto insurance system, which means every driver must carry Personal Injury Protection (PIP).
Florida’s minimum requirements for auto liability coverage are:
- $10,000 in property damage liability per accident
- $10,000 in personal injury protection (PIP)
It’s critical to understand that your personal auto insurance policy almost certainly won’t cover accidents that occur while you’re using a vehicle for business purposes. Personal policies have specific exclusions for commercial use, which means if you or an employee gets into an accident during work hours, you could be left footing the entire bill out of pocket.
This is where Hired and Non-Owned Auto (HNOA) insurance comes into play. If your employees use their personal vehicles for work-related tasks, or if you occasionally rent vehicles for business use, HNOA coverage can protect your business from liability in case of an accident. It’s a smart addition that fills a significant gap in coverage, especially as many small businesses start out by having employees use their own cars for deliveries or errands.
Implications of Non-Compliance
Ignoring Florida’s mandatory insurance requirements isn’t just risky; it can be disastrous for your business. The state takes these laws seriously, and the consequences for non-compliance can range from inconvenient to financially crippling.
Imagine receiving hefty fines that quickly add up, or worse, a stop-work order that forces you to halt all operations until you’re compliant. This not only causes immediate financial losses but can also damage your reputation with clients and employees. Without proper workers’ compensation, an injured employee could sue your business, potentially exposing your personal assets if your business isn’t structured to protect them. Furthermore, repeated non-compliance could lead to the revocation of your business license, effectively shutting down your operations. It’s a situation no business owner wants to face, highlighting why understanding and securing the right business insurance Florida policies is so vital.
Key Insurance Policies for Florida Businesses
While state law dictates certain minimums, truly protecting your Florida business means looking beyond just the mandatory requirements. A comprehensive insurance strategy involves tailoring coverage to your specific risks, ensuring you’re prepared for the unexpected twists and turns that come with entrepreneurship in the Sunshine State. Let’s explore some of the most common and crucial policies that go beyond the basics.
General Liability Insurance
Often considered the cornerstone of a solid business insurance portfolio, General Liability Insurance (sometimes called Commercial General Liability or CGL) protects your business from common third-party claims of bodily injury, property damage, and even advertising injury. Think of it as your safety net for everyday mishaps.
For instance, if a customer slips and falls in your St. Petersburg storefront, breaking their arm, General Liability would help cover their medical expenses and your legal defense costs if they sue. If an employee accidentally damages a client’s property while working on-site, this policy would step in. It also covers claims arising from libel, slander, or copyright infringement in your advertising.
While not legally required by the state of Florida, General Liability is almost universally recommended. Many commercial landlords and clients will require proof of this coverage before signing leases or contracts, making it a de facto requirement for doing business. The average cost for General Liability insurance in Florida is around $49 per month, offering significant protection for a relatively small investment.
Professional Liability (Errors & Omissions)
If your business provides advice, services, or expertise, then Professional Liability Insurance, also known as Errors and Omissions (E&O) insurance, is your specialized shield. This policy protects you from claims of negligence, errors, or omissions in the professional services you provide that result in financial loss for your client.
Consider a consultant whose advice leads to a client’s financial setback, an accountant who makes a critical error on a tax return, or a real estate agent accused of misrepresentation. These scenarios aren’t covered by General Liability because they don’t involve physical injury or property damage; they involve professional mistakes. E&O insurance would cover legal defense costs, settlements, or judgments, even if the claim is unfounded.
For professionals like IT consultants, marketing agencies, architects, engineers, lawyers, and even personal trainers, E&O is indispensable. It’s often required by licensing boards or client contracts. In Florida, the average cost for Professional Liability insurance is about $71 per month, reflecting the specialized nature of its protection.
General Liability vs. Professional Liability
| Feature | General Liability Insurance | Professional Liability (E&O) |
|---|---|---|
| Covers | Physical damages (bodily injury, property damage) | Financial losses from professional services/advice |
| Example | A client slips and falls in your office. | An accountant makes an error on a tax return, causing client fines. |
| Who Needs It | Nearly all businesses. | Service-providing professionals. |
Business Owner’s Policy (BOP)
For many small to mid-sized Florida businesses, a Business Owner’s Policy (BOP) is an incredibly efficient and cost-effective way to get comprehensive coverage. A BOP bundles several essential policies into one convenient package, often at a lower premium than purchasing each policy separately.
Typically, a BOP combines:
- General Liability Insurance: Protecting against third-party bodily injury and property damage.
- Commercial Property Insurance: Covering your business’s physical assets—your building (if you own it), equipment, inventory, and furniture—from perils like fire, theft, and wind damage.
- Business Interruption Insurance: This crucial component helps replace lost income and covers extra expenses (like temporary relocation) if your business is forced to close temporarily due to a covered property loss, such as hurricane damage.
A BOP can be customized to fit your specific needs, making it a versatile option for a wide range of businesses, from retail shops and restaurants to offices and contractors. It simplifies your insurance management and ensures you have a strong foundation of protection against common risks in one neat package.
How Your Florida Business Impacts Insurance Costs
When we talk about the cost of business insurance Florida, there’s no single price tag. Just like every business is unique, so too are the factors that influence your insurance premiums. Imagine trying to price a custom-built home versus a standard model – the details matter! Insurance companies perform a thorough risk assessment and underwriting process to determine your specific rates, and several key elements play a significant role in this calculation.
Industry and Business Type
The type of business you operate is arguably the most influential factor in your insurance costs. Some industries inherently carry more risk than others, and insurers price their policies accordingly.
- High-risk industries: Businesses like construction (especially roofing, which has high workers’ comp rates), restaurants (with their kitchen hazards and high foot traffic), and transportation companies (due to vehicle exposure) typically face higher premiums. Their daily operations present more frequent opportunities for accidents, injuries, or property damage.
- Lower-risk industries: Conversely, businesses like consulting firms, e-commerce operations, or professional offices generally enjoy lower insurance costs because their risk exposure for physical injury or property damage is lower.
Insurers evaluate specific exposures. For example, a roofer will have significantly different workers’ compensation rates than an accountant, reflecting the danger level of their work. A restaurant will pay more for general liability due to the risk of customer slips, burns, or food-borne illness, compared to a tech startup.
Location, Location, Location
In Florida, “location, location, location” isn’t just about real estate value; it’s also a huge factor in your insurance premiums. Our beautiful state, with its extensive coastline, faces unique environmental risks that impact businesses.
- Coastal vs. Inland: Businesses located near the coast, like those in St. Petersburg, often face higher property insurance premiums due to the increased exposure to weather-related risks, particularly hurricanes and storm surge flooding. An inland business, while not immune to severe weather, generally experiences lower rates for property coverage.
- Flood Zones: If your business is in a designated flood zone, you’ll likely need separate flood insurance, which adds to your overall cost.
- Crime Rates: Areas with higher crime rates may see increased premiums for commercial property insurance due to a greater risk of theft or vandalism.
- Proximity to Fire Services: Businesses located closer to a fire station and with access to better fire hydrants might receive discounts on their property insurance, as the risk of extensive fire damage is reduced.
The specific geographic nuances within Florida mean that a business in St. Petersburg might have different rates than one further inland, even if they’re in the same industry.
Other Key Cost Factors for Business Insurance Florida
Beyond your industry and location, several other elements contribute to the final cost of your business insurance Florida policies:
- Number of Employees: More employees generally mean higher payroll and, consequently, higher workers’ compensation premiums. It also increases your overall liability exposure.
- Annual Revenue: Businesses with higher revenue often have more assets, more operations, and potentially greater exposure to claims, which can lead to higher premiums.
- Claims History: A history of frequent or large claims signals higher risk to insurers, often resulting in increased rates. Maintaining a clean claims record is one of the best ways to keep your premiums down.
- Coverage Limits and Deductible Amount: The higher your coverage limits (the maximum an insurer will pay out) and the lower your deductible (the amount you pay out-of-pocket before insurance kicks in), the higher your premiums will be. It’s a trade-off between premium cost and out-of-pocket exposure.
- Years in Business: Established businesses with a proven track record of stability and fewer claims may receive more favorable rates than brand-new ventures.
- Safety Protocols: Implementing strong safety programs, regular employee training, and robust risk management practices can demonstrate a commitment to safety, potentially earning you discounts.
Understanding these factors helps us explain why your quote is unique and how we can work together to find the most cost-effective yet comprehensive business insurance Florida solutions for your specific enterprise.
A Practical Guide to Lowering Your Florida Business Insurance Premiums
We understand that managing business expenses is a top priority for any Florida business owner. While insurance is a crucial investment, there are smart strategies you can employ to potentially reduce your premiums without sacrificing essential coverage. Our goal is to help you find the sweet spot between comprehensive protection and affordable rates.
1. Bundle Policies
One of the easiest ways to save on business insurance Florida is by bundling multiple policies with a single insurer. As we discussed, a Business Owner’s Policy (BOP) is a prime example of this, combining General Liability, Commercial Property, and Business Interruption into one package at a discounted rate. Many insurers also offer multi-policy discounts if you combine other coverages, such as commercial auto or professional liability, with your BOP. This not only saves you money but also simplifies your insurance management, as you’ll have fewer policies to keep track of and often a single point of contact for claims or questions.
2. Implement a Risk Management Program
Insurers love a business that takes proactive steps to minimize risks. By implementing a robust risk management program, you demonstrate a commitment to safety and loss prevention, which can translate into lower premiums. This includes:
- Workplace Safety Training: Regularly training your employees on safe practices, emergency procedures, and equipment operation can significantly reduce the likelihood of workers’ compensation claims.
- Regular Equipment Maintenance: Keeping your machinery, vehicles, and premises in good working order prevents breakdowns and accidents that could lead to property damage or liability claims.
- Data Security Protocols: For businesses handling sensitive customer data, strong cybersecurity measures can reduce the risk of costly data breaches, potentially lowering cyber liability insurance premiums.
- Written Safety Plans: Having documented safety procedures shows diligence and can be beneficial during the underwriting process.
Fewer claims mean lower costs for insurers, and they often reward businesses that help them achieve that goal.
3. Review and Adjust Coverage Annually
Your business is not static, and neither should your insurance policy be. As your Florida business grows and evolves, so too should your coverage. We recommend reviewing your policies annually to ensure they still accurately reflect your current operations.
- Have you added new services or products?
- Has your revenue significantly increased?
- Have you purchased new equipment or expanded your physical space?
Being underinsured leaves you vulnerable, but being overinsured means you’re paying for coverage you don’t need. An annual review helps you strike the right balance, ensuring you’re adequately protected without overpaying. It’s also an opportunity to discuss any changes with us and see if new discounts might apply.
4. Choose a Higher Deductible
This strategy involves a trade-off: accepting a higher deductible (the amount you pay out-of-pocket before your insurance coverage kicks in) can significantly lower your annual insurance premiums. If your business has a healthy financial buffer and you’re comfortable covering a larger initial expense in the event of a claim, opting for a higher deductible can lead to substantial long-term savings on your premiums. It’s a balancing act that requires careful consideration of your business’s financial health and risk tolerance.
5. Compare Quotes from Multiple Carriers
Perhaps the most impactful way to save money on business insurance Florida is to shop around and compare quotes from multiple insurance carriers. The insurance market is competitive, and rates can vary significantly between providers for the exact same coverage.
As an independent insurance agency, we specialize in doing this for you. We have access to a wide range of top-rated carriers, allowing us to gather and compare quotes on your behalf. This ensures you’re getting the best possible value – comprehensive coverage at the most competitive price – without the hassle of contacting multiple companies yourself. It’s like having a personal shopper for your insurance needs, ensuring you get the perfect fit every time.
Finding Reliable Resources and Expert Guidance
Navigating business insurance Florida can feel like a complex journey, especially with our state’s unique risks and regulations. But you don’t have to go it alone. There are numerous reliable resources and expert guides available to help you make informed decisions and secure the right protection for your venture.
Official State and Federal Resources
For foundational information and compliance details, we always recommend consulting official government sources. These entities provide accurate, up-to-date information on legal requirements and support for businesses:
- The Florida Small Business Development Center offers valuable assistance and resources for small businesses across the state, including guidance on various operational aspects.
- The U.S. Small Business Administration Florida District provides a wealth of information, from starting a business to understanding federal regulations and support programs.
- The Florida Department of Financial Services is another critical resource for understanding state-specific insurance regulations, licensing requirements, and consumer services. They are the ultimate authority on what’s required and how it’s regulated in our state.
These resources are invaluable for ensuring your business meets all legal obligations and stays informed about the latest requirements.
The Advantage of an Independent Insurance Agency
While direct carriers and online platforms offer convenience, working with an independent insurance agency like ours provides distinct advantages, especially for Florida businesses. We pride ourselves on being your trusted advisor, not just a salesperson.
- Access to Multiple Carriers: Unlike captive agents who can only sell policies from a single company, we partner with a wide network of top-rated insurance providers. This means we can shop around on your behalf, comparing numerous quotes to find the best coverage and rates custom specifically for your business.
- Unbiased Advice: Our loyalty is to you, our client. We provide objective recommendations based on your unique needs, not on a single company’s product offerings.
- Personalized Service: We take the time to understand your business, its operations, and its specific risks. This allows us to craft customized insurance solutions that truly protect what you’ve built.
- Local Market Knowledge: Operating right here in St. Petersburg, Florida, we possess an intimate understanding of the local market, including regional risks like hurricanes and specific regulatory nuances that might affect your business.
- Policy Customization: We can help you steer complex policy options, identify potential coverage gaps, and build a comprehensive insurance portfolio that fits your budget.
- Claims Assistance: In the unfortunate event of a claim, we act as your advocate, guiding you through the process and working with the insurer to ensure a fair and timely resolution.
Choosing an independent agency means you have a dedicated partner committed to securing your business’s future.
Understanding Your Options for Business Insurance Florida
When it comes to purchasing business insurance Florida, you have several avenues, each with its pros and cons:
- Direct Carriers: You can go directly to an insurance company (e.g., a large national brand) to get a quote. This can be straightforward if you know exactly what you need, but you’re limited to that company’s products.
- Captive Agents: These agents work exclusively for one insurance company. They are experts in their company’s offerings but cannot provide quotes from competitors.
- Online-Only Providers: Many digital platforms offer quick online quotes. While convenient, they might not offer the personalized advice needed for complex Florida risks or allow for in-depth customization.
- Independent Agents: This is where we shine. As an independent agency, we work with multiple insurance companies, offering you a broader selection of products and competitive pricing. We combine the convenience of online access with personalized, expert advice.
For Florida businesses, especially given our unique environmental challenges, the nuanced advice and broad market access offered by an independent agency can be invaluable in finding the right fit for your specific needs.
Conclusion: Secure Your Quote and Protect Your Business
Navigating the complexities of business insurance Florida doesn’t have to be daunting. By understanding the mandatory requirements, recognizing the key policies that offer comprehensive protection, and implementing smart strategies to manage costs, you can confidently safeguard your Sunshine State venture. Proactive protection isn’t just about compliance; it’s about ensuring the long-term stability and success of your business against Florida’s unique challenges, from the daily grind to the annual hurricane season.
Here at Florida All Risk Insurance, we specialize in providing personalized service and access to a wide range of carriers, ensuring custom coverage and competitive rates for clients across Florida. Our expertise in the local market, combined with our commitment to understanding your specific business needs, makes us your ideal partner in securing comprehensive business insurance Florida. We believe that custom coverage is key to true peace of mind.
Ready to protect your Florida business? Get a comprehensive, no-obligation quote custom to your unique needs. Contact us today to get started.
For a deeper dive into all available commercial coverage options, explore our complete guide to business insurance products.
Contact Us
Florida All Risk Insurance
Address: 123 Main Street, Saint Petersburg, FL 33701
Phone: (727) 555-1234
Email: [email protected]

