

Brevard County Home Insurance: The Complete Guide
Understanding the Cost of Protecting Your Space Coast Home
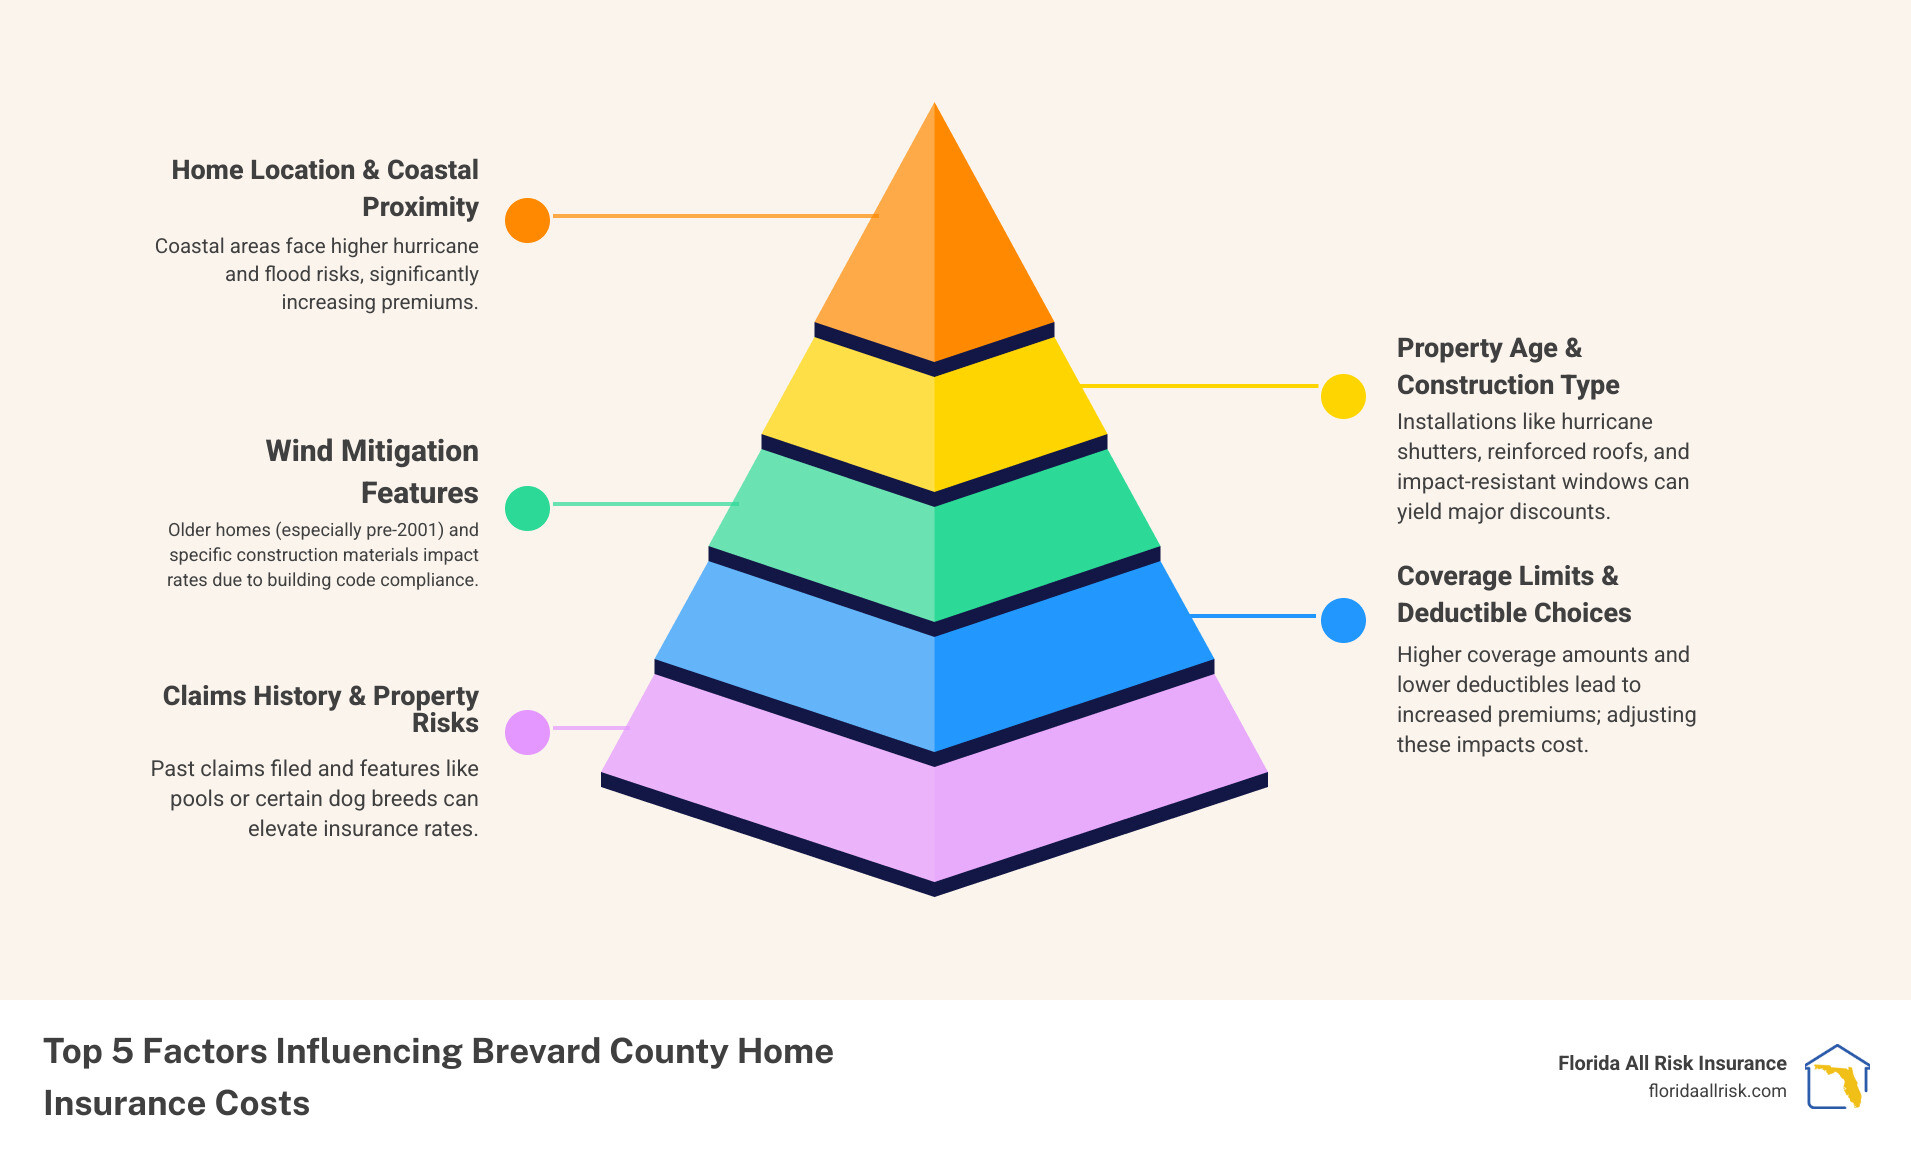
Brevard county home insurance costs vary based on your home’s location, age, and coverage. On average, annual premiums can range from $3,944 for a $150,000 home to over $12,539 for a $450,000 home. Key factors influencing your rate include coastal proximity, home age (pre-2001 homes cost more), and whether you have wind-mitigation features, which can cut rates by up to 62%.
Living on Florida’s Space Coast means facing unique risks like hurricanes and flooding, especially in low-elevation areas. It’s critical to know that standard homeowners insurance does not cover flood damage—a significant gap given Brevard County’s 72-mile coastline. Navigating hurricane deductibles, flood zones, and coverage options requires expert guidance to ensure you’re properly protected without overpaying.
I’m Jason Miller, an insurance professional with over 20 years of experience helping Florida homeowners. I specialize in brevard county home insurance and understand the challenges Space Coast residents face. My goal is to help you find the right solutions to protect your home.
Common brevard county home insurance vocab:
- homeowners insurance Florida
- homeowners insurance in pinellas county florida
- another home insurance company leaving florida
What Determines Home Insurance Rates in Brevard County?
Your brevard county home insurance premium is the result of a detailed assessment of your home’s unique risk profile. For example, a $150,000 home on Merritt Island might cost around $3,944 annually, while a $450,000 home could be $10,251. These rates reflect the cost to rebuild and are influenced by three main categories: your home’s characteristics, its location, and your policy choices.
Your Home’s Characteristics: The Core of Your Premium
An insurer’s primary concern is the physical nature of the property they are covering.
- Replacement Cost: This is the cost to rebuild your home from scratch, not its market value. It’s the most important factor in determining your dwelling coverage amount.
- Home Age & Construction: Homes built before 2001 often have higher premiums as they may lack modern hurricane-resistant features. Concrete block homes are typically cheaper to insure than wood-frame homes.
- Roof Condition: The age, material, and condition of your roof are critical. Many insurers are hesitant to cover roofs older than 15-20 years due to the high risk of failure.
- Square Footage: Larger homes cost more to rebuild, which leads to higher premiums.
The Florida Office of Insurance Regulation offers data on how these factors affect costs for homes in different value tiers.
Location, Location, Location: Brevard County’s Unique Risks
Our 72-mile coastline on the Space Coast presents specific risks that directly impact insurance rates.
- Hurricane Risk: Proximity to the coast increases the risk of damage from high winds and storm surge, leading to higher premiums.
- Flood Risk: Standard policies exclude flood damage. In low-lying areas like zip code 32937 (6 feet elevation), this is a major concern, as just one inch of water can cause over $20,000 in damage. Check your property’s status on a FEMA Flood Zone Map or an interactive flood map.
- Wildfire Risk: Brevard County’s long dry season (December-May) creates a significant wildfire risk, another factor insurers consider.
Policy Details and Personal Factors
Your choices and personal details also play a role in your final premium.
- Coverage Limits & Deductibles: Higher coverage limits increase your premium, while a higher deductible lowers it. You must balance protection with affordability.
- Claims History: A history of frequent claims can lead to higher rates or difficulty finding coverage.
- Attractive Nuisances & Dog Breeds: Features like pools and trampolines, or certain dog breeds, increase liability risk and can affect your premium. We can help you steer the specifics of homeowners insurance with dogs.
Decoding Your Brevard County Home Insurance Policy
Understanding your brevard county home insurance policy can save you money and prevent surprises during a claim. Most Florida policies use a standard HO-3 form. This covers your home’s structure for all risks except those specifically excluded, while your personal belongings are covered only for perils named in the policy. Knowing what’s included in your Florida Homeowners Insurance Products—and what isn’t—is key to being properly protected.
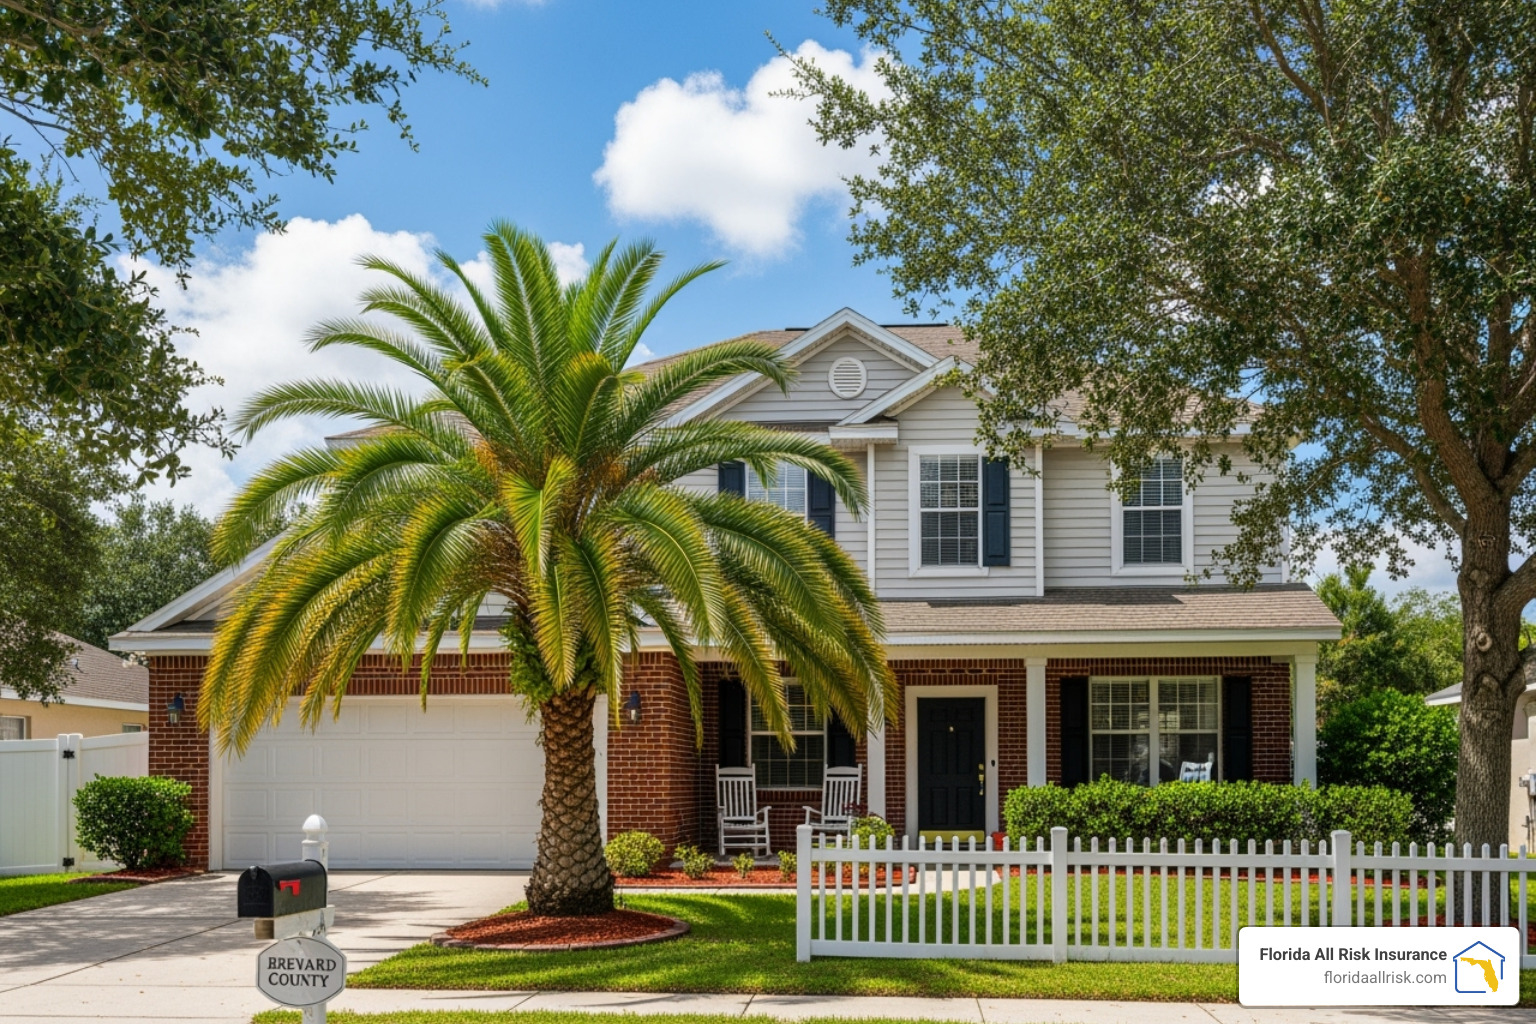
Standard Coverage: What’s Typically Included?
Your policy is a package of six core coverages:
- Coverage A: Dwelling: Protects the physical structure of your house, including the foundation, walls, and roof.
- Coverage B: Other Structures: Covers structures not attached to your home, like a detached garage, fence, or shed.
- Coverage C: Personal Property: Protects your belongings (furniture, clothes, electronics), even when they are outside your home.
- Coverage D: Loss of Use: Pays for additional living expenses like hotel stays and meals if your home is uninhabitable after a covered loss.
- Coverage E: Personal Liability: Protects your finances if you’re legally responsible for injuring someone or damaging their property.
- Coverage F: Medical Payments: Covers minor medical bills for guests injured on your property, regardless of fault.
Common Exclusions: Critical Gaps in Standard Policies
An HO-3 policy does not cover everything. Understanding these common exclusions is vital to identifying gaps in your protection:
- Flood Damage: This is the most critical exclusion in coastal Florida. Damage from rising water, storm surge, and sewer backup is not covered.
- Earth Movement: Sinkholes, earthquakes, and landslides require a separate endorsement.
- Neglect and Wear & Tear: Insurance covers sudden, accidental events, not routine maintenance issues or damage from neglect.
- Pest Infestations: Damage from termites, rodents, or other vermin is considered a preventable maintenance problem.
- Mold: Coverage is often limited or excluded unless the mold is the direct result of a covered, sudden event like a burst pipe.
- Nuclear Hazards & Government Action: These large-scale events are standard exclusions.
Essential Additional Coverage for Brevard County Homeowners
Standard policies have significant gaps, and in Brevard County, that means you need additional coverage to be fully protected. These protections are available as endorsements (add-ons to your policy) or as separate policies. It’s crucial to address these gaps before you have a claim.

Why Flood Insurance is Non-Negotiable on the Space Coast
Flood damage is completely excluded from standard homeowners insurance. This is a critical gap on the Space Coast, where storm surge and heavy rains pose a constant threat. Just one inch of floodwater can cause over $20,000 in damage. Even if you’re not in a high-risk zone where a lender would require it, flood insurance is strongly recommended.
You can obtain coverage through the National Flood Insurance Program (NFIP) or private insurers. Private options are often more competitive, with some providers offering rates significantly lower than the NFIP average. Exploring both avenues helps ensure you balance cost and protection.
Understanding Hurricane Deductibles and Windstorm Coverage
Hurricane deductibles are a vital part of your brevard county home insurance policy. Unlike a standard flat-dollar deductible, a hurricane deductible is a percentage of your dwelling coverage (typically 2 %, 5 %, or 10 %). For a $300,000 home with a 2 % deductible, you’d be responsible for the first $6,000 in damages from a named storm.
This deductible only applies to damage from a storm officially named by the National Hurricane Center. Windstorm coverage is an integral part of your policy, but you must have it in place before a storm is approaching. Insurers place moratoriums on new policies once a storm is a threat, so review your coverage well before hurricane season begins.
How to Lower Your Brevard County Home Insurance Premiums
While protecting your Space Coast home is essential, you don’t have to overpay for brevard county home insurance. A combination of home improvements and smart policy choices can significantly reduce your premiums without sacrificing important coverage.
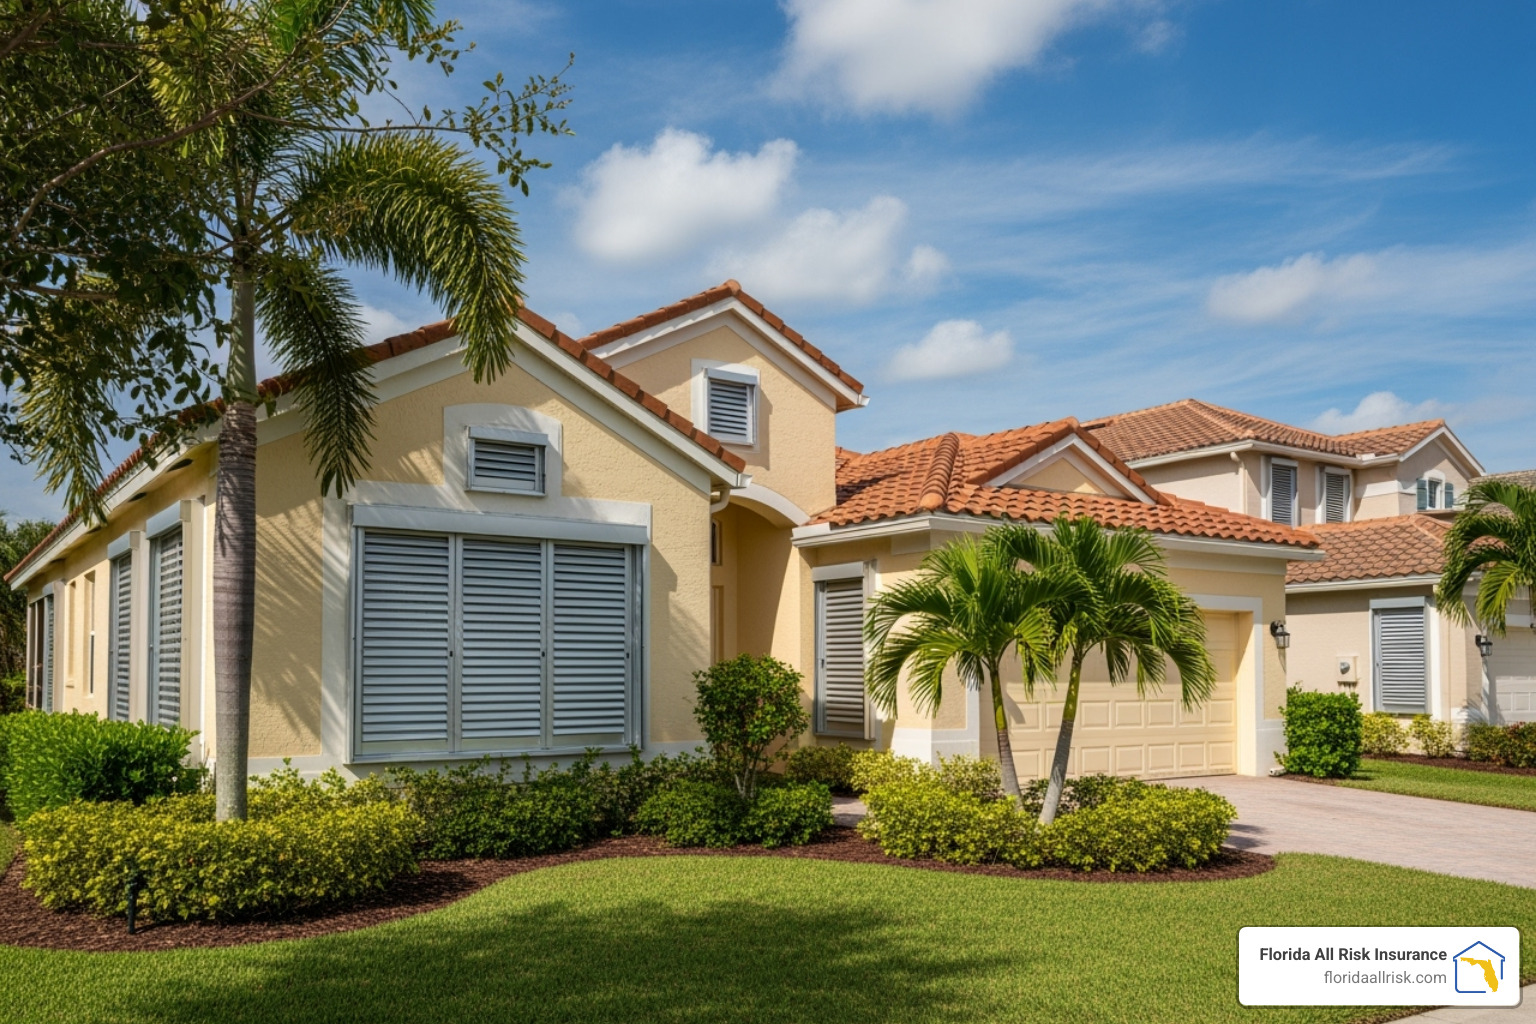
The Power of Wind Mitigation
Wind mitigation is the single most effective way to slash your insurance costs. These are features that strengthen your home against hurricane-force winds, and insurers reward them with sizable discounts—often up to 62 %, which can translate to thousands of dollars annually.
A licensed inspector can perform a wind-mitigation inspection to certify your home’s features, which include:
- Roof Shape: A hip roof (sloped on all four sides) is more wind-resistant than a gable roof.
- Roof-to-Wall Connections: Hurricane clips or straps that secure your roof to the walls.
- Impact-Resistant Openings: Hurricane shutters or impact-resistant windows and doors.
These improvements make your home safer and can pay for themselves through insurance savings.
Other Valuable Discounts and Savings Strategies
Beyond wind mitigation, you can stack other discounts to lower your costs:
- Multi-Policy Bundling: Combine your home and auto policies with one carrier for significant savings.
- Home Security: Monitored burglar and fire alarm systems can earn you a discount.
- Claims-Free History: Insurers reward homeowners who remain claim-free for several years.
- Higher Deductibles: Choosing a higher deductible will lower your annual premium, but ensure you can afford the out-of-pocket cost if you file a claim.
- Newer Home: Homes built to modern codes are cheaper to insure.
Working with an agent can help you identify every discount you qualify for and confirm that you are not sacrificing vital protection in the process.
Finding the Right Brevard County Home Insurance Provider
Shopping for brevard county home insurance is about more than finding the lowest price. You need a provider with comprehensive coverage, competitive pricing, and reliable service who will be there when you need to file a claim.
Comparing Insurance Companies and Policies
When evaluating insurers, look beyond the premium. Key factors include:
- Financial Stability: Check ratings from A.M. Best—look for A- or better—to ensure the company can pay claims even after a widespread disaster.
- Claims Handling: Research each carrier’s reputation for fair and timely claim settlements.
- Customer Satisfaction: High policyholder-retention rates often signal excellent customer service.
It’s also important to note that Brevard County has many residents insured by Citizens Property Insurance Corporation, the state’s insurer of last resort. While Citizens fills a crucial gap, its goal is to move policies back to the private market, which can lead to policy changes over time.
The Advantage of Working with an Independent Insurance Agency
Unlike captive agents who represent a single company, independent agents work with multiple carriers. This approach provides several advantages:
- Wider Choice: Comparing offers from a broad selection of insurers helps you find an option that fits your budget and risk profile.
- Objective Guidance: Because an independent agent is not tied to one carrier, recommendations are based on your needs—not corporate quotas.
- Personalized Service and Advocacy: An agent who knows the Florida market can explain policy language and stand beside you during claims.
Conclusion: Securing Your Peace of Mind on Florida’s Space Coast
Choosing and maintaining the right brevard county home insurance might feel daunting, yet it’s one of the most important investments you’ll ever make. By understanding how rates are calculated—replacement cost, wind mitigation, location, and deductible choices—you place yourself in a stronger position to balance affordability and protection. Just as importantly, filling policy gaps with flood coverage, carefully selecting your hurricane deductible, and keeping documentation up-to-date will speed up recovery if disaster strikes.
Brevard County’s beauty is inseparable from its risks: 72 miles of Atlantic shoreline bring world-class rocket launches and pristine beaches, but also storm surge, salt-spray corrosion, and near-annual brushes with tropical systems. A well-crafted policy serves as your financial backstop so you can focus on daily life, not looming weather charts. To that end, we recommend revisiting your coverage before every hurricane season, updating your home inventory with photos or video, and scheduling a wind-mitigation inspection whenever you improve your roof or openings.
Taking these proactive steps also fosters long-term savings. For example, investing in impact-rated windows might cost a few thousand dollars upfront, yet many homeowners recoup that expense in less than five years through premium reductions—while enjoying quieter rooms and better energy efficiency. Likewise, installing a centrally monitored smoke detector can earn a modest discount and, more importantly, shave precious minutes off emergency response times.
Insurance is only as good as the company and the team standing behind the policy. An independent agency can compare multiple carriers, confirm each provider’s financial strength through resources such as the National Association of Insurance Commissioners and deliver unbiased advice custom to your home’s construction, zip code, and personal risk tolerance.
Ready to Strengthen Your Coverage?
If you’d like a fresh look at your current policy, want to discuss flood or wind-mitigation options, or simply have questions about deductibles, our team is here to help. Reach out today for a no-pressure review and find how small adjustments can safeguard your biggest asset for years to come.
Contact Us
Florida All Risk Insurance
Address: Saint Petersburg, FL
Phone: (727) 489-6924
Email: [email protected]

