

Why Choosing the Right Auto Insurance Company Matters
Auto insurance companies are not all created equal. Finding the right one can save you hundreds of dollars annually while ensuring you’re properly protected on Florida’s roads. Auto insurance isn’t just a legal requirement—it’s your financial safety net. A fender bender, a stolen vehicle, or damage from a hurricane can cost thousands out of pocket without the right coverage.
So, how do you separate the excellent providers from the merely adequate? The answer lies in looking for key features: financial stability to pay claims, competitive rates with available discounts, flexible coverage options, and a reputation for great customer service and fast claims processing. The “best” company for your neighbor might not be the best for your unique situation.
This guide will walk you through everything you need to know about auto insurance companies, from decoding coverage types to smart savings strategies. We’ll also explore why working with an independent insurance broker can give you access to more options and better guidance than going directly to a single carrier.
I’m Jason Miller, and I’ve spent over 20 years helping Florida families steer the often-confusing world of auto insurance companies. My goal is to help you find coverage that protects what matters most without breaking your budget.
Understanding the Building Blocks of Auto Insurance Coverage
Think of auto insurance like building a house—you need a solid foundation, but you also want walls and a roof for full protection. Understanding what each coverage type does will help you build a policy that truly protects you. Here in Florida, the state minimums might not be enough when something goes wrong, leaving you dangerously exposed.
State Requirements vs. Optional Coverage
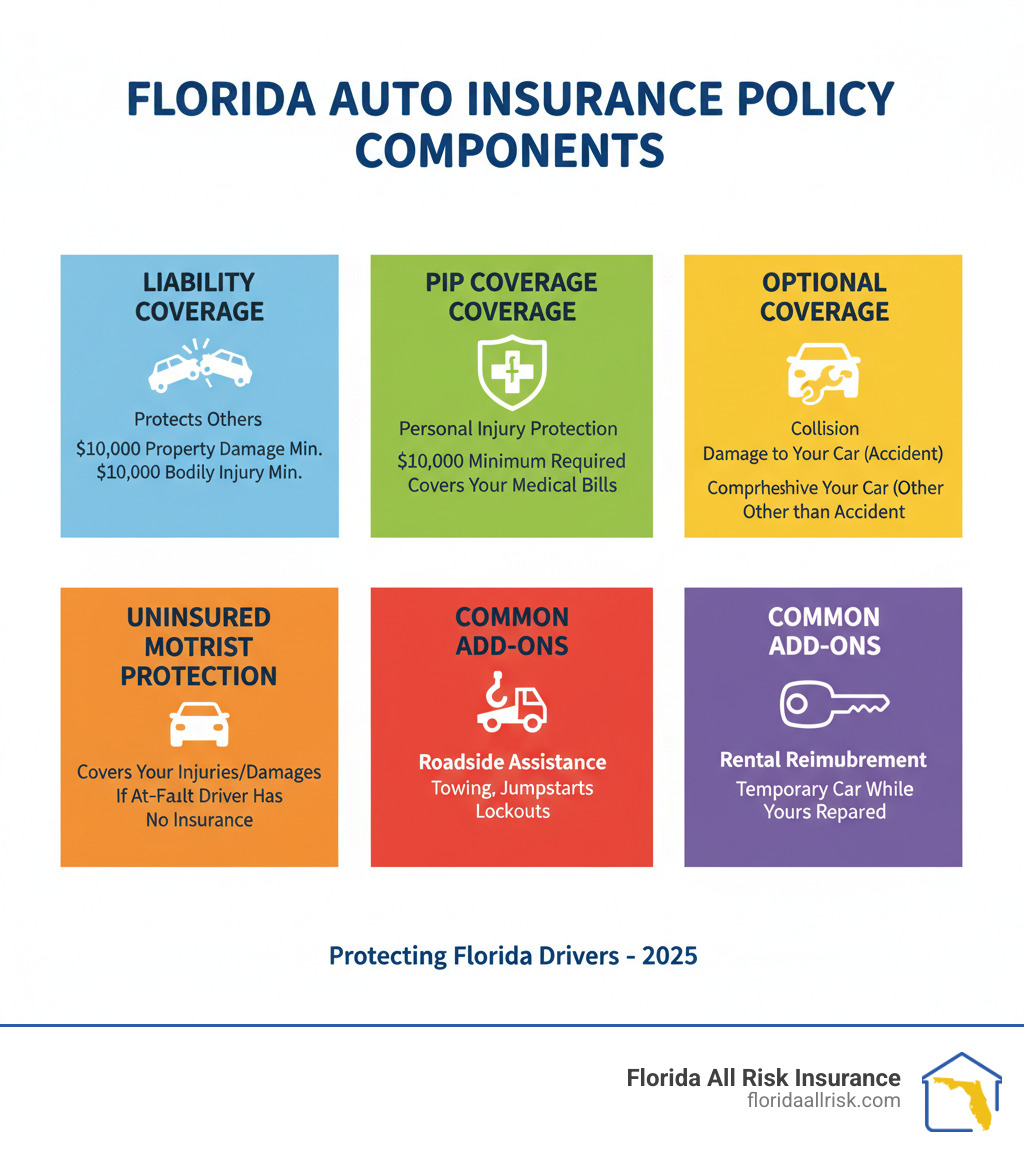
Florida operates under a “no-fault” system. This can be a confusing term. It doesn’t mean no one is ever at fault in an accident. It simply means your own insurance pays for your initial medical bills after an accident, regardless of who caused it. This helps you get treatment quickly without waiting for a lengthy fault determination. Because of this, Florida requires two specific coverages:
- Personal Injury Protection (PIP): You must carry at least $10,000 in PIP. It covers 80% of your eligible medical expenses and 60% of lost wages up to the limit. It’s important to note that $10,000 can be exhausted very quickly, even after a minor accident.
- Property Damage (PD) Liability: You must carry at least $10,000 to pay for damage you cause to other people’s property, like their car, a mailbox, or a fence. With the rising cost of vehicles, $10,000 is often insufficient to cover the full cost of a new car.
Surprisingly, Bodily Injury (BI) Liability is not required in Florida for most drivers. This coverage pays for someone else’s medical bills, lost wages, and pain and suffering if you cause an accident. Without it, you could be personally sued for hundreds of thousands of dollars, putting your savings, home, and future earnings at risk. We always recommend adding BI liability to your policy for this reason. You can learn more on our Liability Car Insurance Florida page.
Essential Optional Coverages
Driving with only the state minimums is a significant financial gamble. These optional coverages provide real protection for your assets and vehicle:
- Collision Coverage: Pays to repair or replace your car after a crash, whether you hit another car, a tree, or back into a pole. If you have a car loan or lease, your lender will almost certainly require it.
- Comprehensive Coverage: Protects your car from non-collision events. This includes theft, vandalism, fire, falling objects, and weather-related damage like hail or flooding from a hurricane—a must-have in Florida. Lenders also typically require this.
- Uninsured/Underinsured Motorist (UM/UIM) Coverage: This is critical. Florida has one of the highest rates of uninsured drivers in the nation. If one of them hits you and you’re injured, UM/UIM covers your medical bills, lost wages, and other expenses (including pain and suffering) when the at-fault driver has no insurance or not enough to cover your costs. We explain its importance on our Uninsured Motorist Coverage Florida page.
Additional Optional Add-ons
Consider these helpful extras to round out your policy and add convenience:
- Rental Reimbursement: Pays for a rental car while yours is in the shop for repairs after a covered claim. This can save you hundreds of dollars and significant hassle.
- Roadside Assistance: Provides 24/7 help for emergencies like flat tires, dead batteries, lockouts, or running out of gas.
- Accident Forgiveness: Prevents your rates from increasing after your first at-fault accident. Some companies offer this as a loyalty reward.
- Custom Parts and Equipment: Covers aftermarket additions like custom wheels, stereo systems, or lift kits that aren’t typically covered by standard collision or comprehensive.
Choosing the right combination is about matching coverage to your risks and budget. For a deeper look at all your choices, visit our Auto Insurance Coverage Options page.
Decoding Your Premium: What Factors Influence Auto Insurance Costs?
Ever wondered why your auto insurance premium is what it is? Auto insurance companies use a complex mix of factors to calculate your rate. Understanding these elements can empower you to make smarter decisions and find potential savings. Each insurer weighs these factors differently, which is why two companies can offer vastly different prices for the same driver.
Driving Record and History
This is one of the most significant factors. A history of at-fault accidents or traffic violations like speeding tickets, running red lights, or reckless driving signals higher risk to insurers, leading to higher premiums. Serious infractions like a DUI will cause the steepest increases and may even make it difficult to find coverage. If you’re navigating this difficult situation, we have resources to help at DUI Auto Insurance Florida. A pattern of frequent claims, even for non-fault incidents like glass or roadside assistance, can also raise your rates with some carriers.
Personal Demographics
Factors beyond your control also play a role:
- Age and Experience: Young drivers under 25 face the highest rates due to statistical risk and lack of experience. Premiums typically decrease with age and a clean record, though they may rise again for senior drivers in their late 70s and beyond.
- Location: Your zip code matters immensely. Urban areas with more traffic congestion, higher crime rates, and more accidents (like Miami or Orlando) generally have higher rates than quiet suburban or rural locations. In Florida, proximity to the coast can also be a factor due to hurricane risk.
Vehicle Details
What you drive directly impacts your premium:
- Make and Model: Sports cars and luxury vehicles cost more to insure due to higher purchase prices, expensive repair costs, and a higher likelihood of being stolen. Practical sedans, SUVs, and minivans are often cheaper to insure. The age of your vehicle is also a factor; older cars may be cheaper to insure, especially if you drop collision and comprehensive coverage.
- Safety and Anti-Theft Features: Cars with advanced safety features like automatic emergency braking, blind-spot monitoring, and anti-lock brakes can earn you discounts. Likewise, anti-theft devices like alarms or GPS tracking systems can lower your comprehensive coverage cost. You can learn more about vehicle safety ratings from authoritative sources like the IIHS.
- Repair Costs: Insurers look at how much a vehicle typically costs to repair. Electric vehicles (EVs) and cars with advanced driver-assistance systems (ADAS) can have higher repair costs for batteries and sensors, which can offset some of the safety discounts.
Your Policy Choices
You have direct control over these cost factors:
- Coverage Limits: Choosing higher liability limits (e.g., $100,000/$300,000 instead of the minimum) provides more protection but increases your premium. It’s wise to choose limits that are high enough to protect your personal assets.
- Deductibles: A higher deductible (the amount you pay out-of-pocket on a collision or comprehensive claim) will lower your premium. A common strategy is to choose the highest deductible you can comfortably afford to pay on short notice.
Annual Mileage
The more you drive, the greater your statistical risk of an accident. Low-mileage drivers often qualify for significant discounts. If you work from home, have a short commute, or are retired, be sure to let your insurer know as it could lead to substantial savings. We explore this in detail on our page about how low mileage can slash your Florida car insurance bill.
For a closer look at local trends, visit our Auto Insurance Rates Florida page.
Smart Strategies to Save Money on Your Car Insurance
You can significantly reduce your auto insurance costs without compromising protection. With a few strategic moves, you can keep more of your hard-earned money.
Bundling Policies: The Power of Package Deals
One of the easiest ways to save is by bundling. When you combine your home and auto insurance with the same provider, you can open up a multi-policy discount that often saves 5-25%. Insuring multiple vehicles with one company also triggers a discount, making it a smart move for families. For more tips, see our Auto Insurance for Families page.
Driver-Based Discounts: Rewarding Good Habits
Auto insurance companies reward responsible drivers. A clean driving record can earn you a safe driver discount. For students, good grades often lead to lower rates. Completing an approved defensive driving course can also provide a small discount. Learn more about how your good habits translate to savings on our Safe Driver Insurance Discounts page.
Usage-Based Insurance (UBI) and Telematics
Telematics programs use a smartphone app or a small device to track your actual driving habits. If you’re a safe, low-mileage driver, you could earn discounts of up to 35% or more. This personalizes your premium based on your real-world behavior, not just statistics. Explore this option on our Pay As You Drive Insurance Florida page.
Comparing Quotes: The Golden Rule of Savings
Never assume your current rate is the best. We recommend comparing quotes annually or after any major life event. When comparing, make sure you’re quoting the exact same coverage levels for an accurate comparison. While price is important, also consider a company’s customer service and claims reputation. For help finding competitive rates, visit our Cheap Auto Insurance Quotes Florida page.
Tips for New Drivers
Insurance for new drivers is expensive, but costs can be managed. Staying on a parent’s policy, driving a safe older car, completing driver’s education, and maintaining good grades all help. Choosing a higher deductible also reduces the premium, but ensure it’s an amount you can afford. Find more advice on our Auto Insurance for Young Drivers page.
| Discount Type | Potential Savings |
|---|---|
| Multi-Policy (Home & Auto) | 5% – 25% |
| Multi-Vehicle | 10% – 25% |
| Safe Driver (Clean Record) | 5% – 20% |
| Good Student | 5% – 15% |
| Telematics/UBI | Up to 35% |
| Defensive Driving Course | 5% – 10% |
| Anti-Theft Devices | 5% – 15% |
| Paid in Full | 3% – 7% |
| Paperless Billing | 1% – 5% |
Note: Discount percentages are estimates and vary by insurer.
Choosing Your Guide: Independent Brokers vs. Direct Insurers
When shopping for auto insurance, you can go straight to an auto insurance company or work with an independent insurance broker. Understanding the difference can have a real impact on your coverage, your wallet, and your peace of mind.
Direct Insurers and Captive Agents
Direct insurers are the big-name brands you see in commercials. They sell policies through their websites, call centers, or captive agents. A captive agent is an insurance professional who works exclusively for one company.
This can be a straightforward approach if you already know and like the brand. The main limitation, however, is the lack of choice. A captive agent can only offer you their company’s products and pricing. If you’re not a perfect fit for their underwriting model—perhaps you’re a young driver, have a spotty record, or own a unique vehicle—you might pay more than necessary. They are loyal to their employer and cannot check if another insurer could offer you a better deal or more suitable coverage.
Independent Insurance Brokers
An independent broker, like us at Florida All Risk Insurance, works for you, not for a single insurance company. We are appointed with multiple, carefully selected carriers to shop the market on your behalf.
Working with an independent broker provides several key advantages:
- Access to Multiple Carriers: We compare quotes from a wide range of auto insurance companies to find the best price and coverage for your specific profile. We know which companies are most competitive for different types of drivers and use that knowledge to your advantage.
- Unbiased Advice: Since we aren’t tied to one company, our recommendations are based purely on what serves your best interests. We’ll explain the differences between policies in plain English and ensure you’re not overpaying or underinsured.
- Personalized Service: We take the time to understand your unique needs, whether you’re adding a teen driver, insuring a classic car, or bundling with a new home. This local, personalized service makes all the difference. Learn more about our approach at Auto Insurance Broker St. Petersburg FL.
- Claims Advocacy: If you need to file a claim, we act as your advocate. We help guide you through the process, communicate with the adjuster, and work to ensure you receive a fair and prompt settlement. You have an expert in your corner when you need it most.
- Long-Term Relationship: Your needs change over time. We’re here to review your coverage annually, adjust your policy as your life evolves, and re-shop the market for you at renewal, ensuring you always have the best protection and value. You can find us among the top Insurance Agencies in St. Petersburg FL.
Navigating the Aftermath: Steps to Take After a Car Accident
No one plans for a car accident, but knowing what to do can make a stressful situation more manageable and protect your insurance claim.
Immediate Steps at the Scene
Your first priority is safety. Follow these steps:
- Ensure Safety: If possible, move your vehicle out of traffic and turn on your hazard lights. If you can’t move, stay inside with your seatbelt on until help arrives.
- Check for Injuries: Check on yourself, your passengers, and the occupants of the other vehicle(s).
- Call 911: Report the accident immediately. A police report is crucial documentation for your insurance claim in Florida, even for minor incidents.
- Exchange Information: Get the other driver’s name, phone number, insurance company and policy number, and driver’s license number. Also, note their vehicle’s make, model, and license plate.
- Document Everything: Use your phone to take photos and videos of the damage to all vehicles, the accident scene, skid marks, and traffic signs. If there are witnesses, get their contact information.
- Never Admit Fault: Stick to the facts when talking to the other driver. Let the police and insurance adjusters determine fault.
Reporting and Managing the Claim
Once the scene is secure, contact your insurer as soon as possible. Most auto insurance companies have 24/7 claims hotlines. Provide the information you collected and be prepared to give a factual account of what happened.
An adjuster will be assigned to investigate your claim. They will review the police report, statements, and photos to determine fault and assess the damages. While Florida is a no-fault state for initial injury benefits (PIP), fault is still determined for property damage and for serious injuries that exceed PIP limits. For a clear overview of the claims process, see this step-by-step guide on how to file an auto insurance claim from the Insurance Information Institute: https://www.iii.org/article/how-to-file-an-auto-insurance-claim
Communicate clearly with your adjuster and keep copies of all documentation. If you purchased your policy through an independent broker like us, we are here to act as your advocate throughout the claims process.
Finding the Best Auto Insurance Companies for Your Needs
The “best” auto insurance company isn’t a single top-ranked provider; it’s the one that best aligns with your specific needs, budget, and expectations for service.
Key Features to Look for in Top Insurers
When evaluating providers, focus on these critical aspects:
- Financial Stability: The company must have the financial strength to pay claims, especially after a widespread disaster like a hurricane. You can check a company’s health by looking at ratings from independent agencies like A.M. Best, which grades insurers on their financial solvency (an “A” rating or higher is excellent).
- Customer Service: Look for responsive, helpful, and knowledgeable representatives. How easy is it to get a real person on the phone to ask a question or make a policy change?
- Claims Reputation: The insurer should be known for a fair and efficient claims process. Research this by looking at the National Association of Insurance Commissioners (NAIC) website, which publishes a complaint index for each company. You can also consult annual studies from sources like J.D. Power that rank companies on claims satisfaction.
- Digital Tools: A user-friendly website and mobile app for managing your policy, paying bills, and viewing ID cards are essential in today’s world.
- Coverage Flexibility: The provider should offer the specific coverages and endorsements you need, from high liability limits to accident forgiveness.
- Available Discounts: Ensure they offer discounts you qualify for, like bundling, good student, or telematics rewards.
You can find general feedback on providers by checking Auto Insurance Reviews Florida.
How to Compare Quotes Effectively
Comparing quotes is about more than just the bottom-line price.
- Gather Your Information: Have your driver’s license, vehicle information (VIN), and current policy details (your declarations page) ready.
- Request Identical Coverage: To get a true “apples-to-apples” comparison, ask each company for a quote with the exact same coverage limits, deductibles, and add-ons.
- Look Beyond Price: A slightly higher premium from a company with a stellar claims reputation and excellent customer service might be worth it for your peace of mind.
- Ask About Discounts: Don’t assume discounts are applied automatically; always ask what you’re eligible for and confirm they’ve been included in the quote.
You can start your search for Car Insurance Quotes Florida or get specific St. Petersburg Auto Insurance Quotes with us.
Why a Local Agency Matters for St. Petersburg Drivers
Working with a local independent agency like ours offers distinct advantages. We live and work here, so we understand the specific risks St. Petersburg drivers face, from hurricane season and coastal flooding to local traffic patterns and tourist-heavy areas. This community knowledge allows us to provide personalized service and custom advice. As your local advocate, we’re here to help you steer the complexities of the Florida insurance market. Explore our local services on our St. Petersburg Car Insurance page and see why we strive to be among the St. Petersburg Best Auto Insurance Companies for service and value.
Conclusion
Finding the right auto insurance comes down to understanding your needs and knowing your options. You’ve learned about Florida’s required coverages like PIP and the essential protections of collision, comprehensive, and uninsured motorist coverage. You also know that factors like your driving record, vehicle, and policy choices influence your premium.
Most importantly, you’re equipped with strategies to save money, from bundling policies to comparing quotes. The key is to be proactive without sacrificing protection. We’ve also highlighted the value of an independent insurance broker. Unlike a captive agent who represents one company, we represent you. At Florida All Risk Insurance, we shop multiple auto insurance companies to find the best fit for your unique situation, providing unbiased advice and personalized service.
The “best” auto insurance company is the one that offers the right coverage at a fair price, backed by a solid reputation. That’s exactly what we help you find. As a local St. Petersburg agency, we understand the risks Florida drivers face and are committed to being your trusted advisor.
Ready to experience the difference that local, independent expertise can make?
Get a Quote today and find how straightforward and affordable comprehensive auto insurance can be.
Need short-term coverage? Explore temporary car insurance options in Florida for flexible solutions custom to your situation.
Contact Us
Florida All Risk Insurance
4500 4th Street North, St. Petersburg, FL 33703
Phone: (727) 345-6789
Email: [email protected]
Website: https://floridaallrisk.com/

